


Drug Delivery Devices Market Size
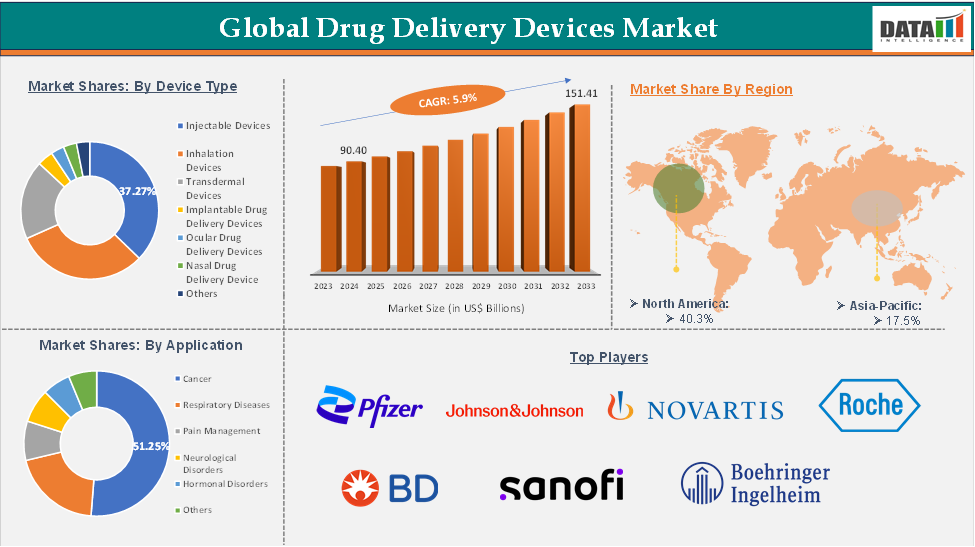
Drug Delivery Devices Market reached US$ 95.73 Billion in 2025 and is expected to reach US$ 151.41 Billion by 2033, growing at a CAGR of 5.9% during the forecast period 2025-2033.
The global drug delivery devices market is undergoing rapid evolution, driven by technological innovation, the rising burden of chronic diseases, and a stronger focus on patient-centered care. Advanced solutions such as smart inhalers, wearable injectors, and implantable systems are improving the accuracy and efficiency of drug administration, leading to better treatment adherence and outcomes.
The integration of digital health technologies, particularly artificial intelligence and the internet of things, is transforming the landscape by enabling real-time monitoring and tailored therapeutic approaches.
North America remains the dominant market, supported by a sophisticated healthcare infrastructure and high adoption of advanced medical technologies. The Asia-Pacific region is emerging as a key growth hub, fueled by increasing healthcare investments, greater health awareness, and a large, growing patient base. The trend toward home-based care and self-administration of medication is further driving demand, reflecting the broader movement toward decentralized healthcare models.
Executive Summary
For more details on this report, Request for Sample
Drug Delivery Devices Market Dynamics: Drivers & Restraints
Driver: Rise in technological advancements in devices
Technological advancements are transforming the drug delivery devices market, improving medication administration efficiency and precision. Key innovations include targeted drug delivery systems, which direct therapeutic agents to diseased tissues, minimizing side effects and improving treatment outcomes, especially in oncology. Oral drug delivery technologies are also addressing challenges like gastrointestinal tract degradation and variable absorption rates.
For instance, in April 2025, Berry Global Healthcare showcased its latest technologies for patient-centric solutions at this year’s RDD (Respiratory Drug Delivery) Europe Conference. The company’s Medical Devices team presented a wide range of ready-to-use platforms for inhalation therapies, which enhanced the patient experience through ease of use and accurate drug delivery, as well as providing faster-to-market solutions. As part of Berry’s ‘Dose Better’ initiative, all had been developed to deliver better healthcare outcomes by improving the quality of care, while helping to reduce costs.
By delivering analgesic agents directly into the cerebrospinal fluid, IDDS bypasses the blood-brain barrier, minimizing systemic exposure and side effects. Programmable pumps also allow for controlled medication release, ensuring consistent pain relief for extended periods.
Restraint: Regulatory challenges
The global drug delivery devices market faces numerous regulatory challenges, including varying regional requirements, lack of clear guidelines, and stringent regulations in markets like Japan. This can lead to increased development times and costs, especially for combination products that integrate drugs and devices. The lack of clear guidelines can cause confusion among manufacturers regarding compliance with specific standards.
As technology evolves, regulators place greater emphasis on software quality and cybersecurity, adding complexity to the approval process. Companies must also be prepared for increasing scrutiny on manufacturing quality and device performance, which is becoming a focal point for regulatory bodies globally. These challenges require strategic planning and collaboration between manufacturers and regulators for successful product development and market entry.
Drug Delivery Devices Market Segment Analysis
The global drug delivery devices market is segmented based on device type, application, end user, and region.
Device Type:
The injectable devices segment is projected to account for approximately 37.27% of the drug delivery devices market in 2025, maintaining its leading share by device type.
Injectable devices are a key player in the global drug delivery market, driven by the increasing prevalence of chronic diseases like diabetes, cancer, and autoimmune disorders. These devices offer advantages like targeted administration, rapid absorption, and improved patient compliance.
Technological advancements have led to the development of self-injectable devices and smart injectors, improving convenience and accuracy in medication delivery. The introduction of biologics and biosimilars further expands the market, as injectable systems provide precise dosing for these therapies.
For instance, in October 2024, UPM Biomedicals launched FibGel, a natural injectable hydrogel for permanent implantable medical devices. Made from birch wood cellulose and water, FibGel is a safe, sustainable, and biocompatible alternative for medical device developers. Designed and manufactured under ISO 13485 standards in Finland, it is poised to transform soft tissue repair, orthopaedics, and regenerative medicine fields.
Drug Delivery Devices Market Geographical Analysis
North America is expected to maintain its leading position in the global drug delivery devices market, accounting for an estimated 41.0% share in 2025.
North America holds a substantial position in the drug delivery devices market and is expected to hold most of the market share due to the novel product launches, adoption of innovative medical technologies, and the prevalence of chronic diseases like diabetes and cancer.
Regulatory support from organizations like the FDA encourages innovation and expedites the approval of advanced drug delivery systems. The presence of leading pharmaceutical and biotechnology companies and substantial R&D investments contributes to the development and commercialization of cutting-edge drug delivery solutions, making North America a major driver of growth.
For instance, in December 2024, NuGen Medical Devices launched its InsuJet needle-free insulin delivery device in Canada, generating $670,000 in revenue. Launched on November 15, the device uses a simple spring-loaded mechanism to release the drug as a fine jet stream of liquid, allowing it to penetrate the skin through a microscopic entrance. The device dispenses the drug safely and evenly in less than one-tenth of a second, with minimal pain or skin damage. The device is approved for sale in 42 countries.
Drug Delivery Devices Market Key Players
The major global players in the drug delivery devices market include Pfizer Inc., Johnson & Johnson, Novartis AG, F. Hoffmann-La Roche AG, Becton, Dickinson and Company, Sanofi, Boehringer Ingelheim, Merck & Co., Inc., Boston Scientific Corporation, Teva Pharmaceuticals Industries Ltd, and others.
Industry Key Developments
- In April 2026, Becton, Dickinson and Company expanded its advanced drug delivery portfolio by introducing next-generation prefillable syringe platforms designed to improve dosing accuracy and patient safety across biologics and specialty pharmaceuticals.
- In March 2026, West Pharmaceutical Services, Inc. announced advancements in elastomer and containment solutions aimed at enhancing the performance and compatibility of injectable drug delivery systems, particularly for high-viscosity biologics.
- In February 2026, Gerresheimer AG strengthened its global production capabilities for drug delivery devices by expanding manufacturing facilities focused on polymer-based injectable systems and on-body delivery solutions.
- In January 2026, Ypsomed Holding AG enhanced its autoinjector platform with improved connectivity features, supporting digital health integration and better patient adherence in chronic disease management.
Drug Delivery Devices Market Scope
Metrics | Details | |
CAGR | 5.9% | |
Market Size Available for Years | 2022-2033 | |
Estimation Forecast Period | 2025-2033 | |
Revenue Units | Value (US$ Bn) | |
Segments Covered | Device Type | Injectable Devices, Inhalation Devices, Transdermal Devices, Implantable Drug Delivery Devices, Ocular Drug Delivery Devices, Nasal Drug Delivery Devices, Others |
Application | Cancer, Respiratory Diseases, Pain Management, Neurological Disorders, Hormonal Disorders, Others | |
End User | Hospitals, Clinics, Homecare Settings, Ambulatory Surgical Centers (ASCs) | |
Regions Covered | North America, Europe, Asia-Pacific, South America, and the Middle East & Africa | |



























































