


Craft Vodka Market Size and Overview
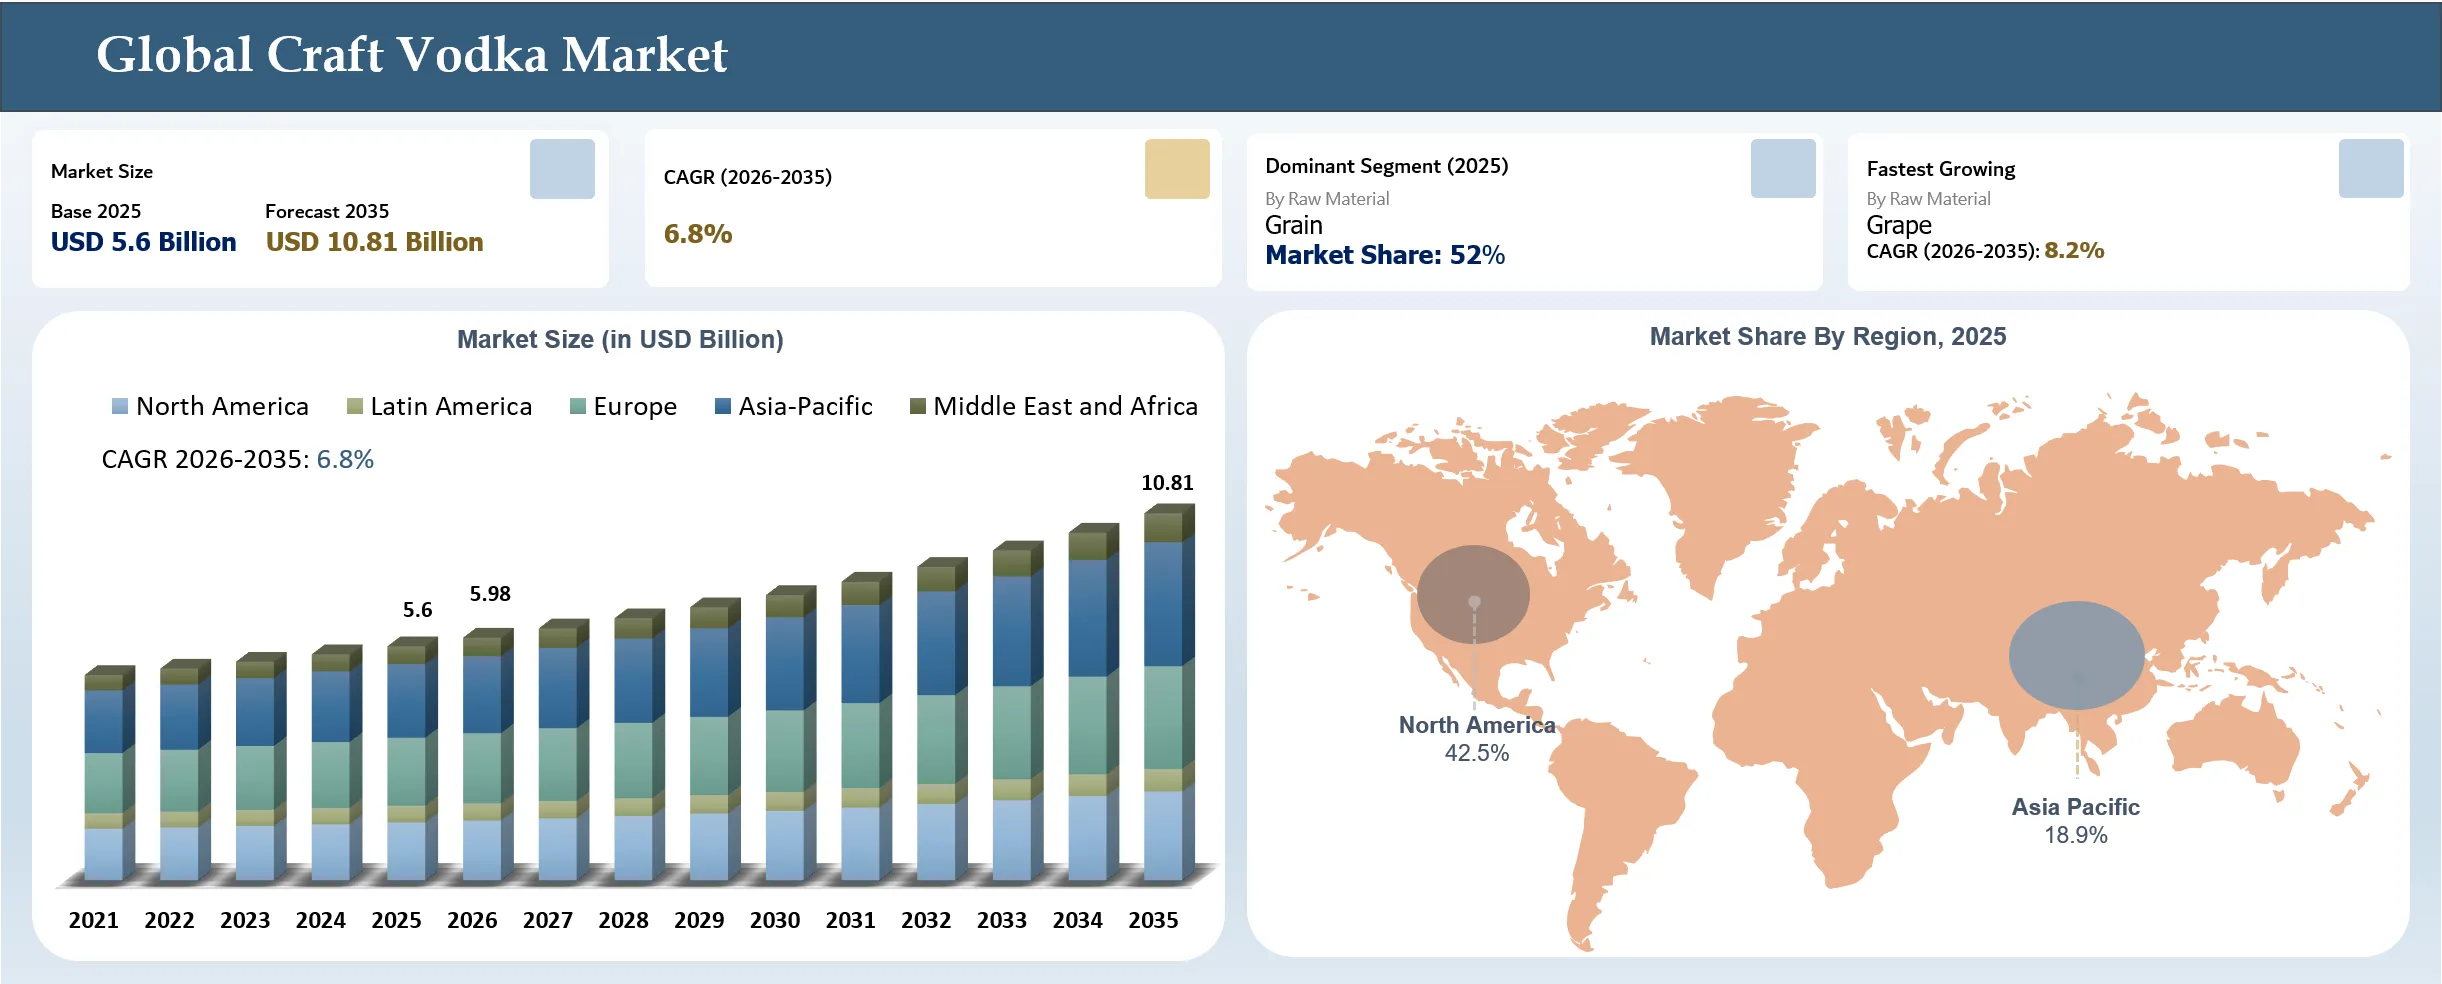
The global craft vodka market reached USD 5.6 billion in 2025 and is expected to reach USD 10.81 billion by 2035, growing with a CAGR of 6.8% during the forecast period 2026-2035. The craft vodka market is being shaped by small-batch distillation, distinctive local ingredients, premium positioning, and product experimentation. Craft distillers are differentiating through proprietary distillation processes, regional raw materials, limited releases, and distinctive flavor profiles. Greater emphasis on production transparency and origin is strengthening the positioning of independently produced vodka. These factors are expanding differentiation across premium and craft-oriented vodka offerings.
In July 2026, Breckenridge Distillery launched Breck Vodka Seltzer, extending its craft-distilled vodka portfolio into the ready-to-drink category. The product combines the distillery's vodka with a lower-calorie, sparkling format designed for convenient consumption. The launch demonstrates how craft vodka producers are extending beyond traditional bottled spirits into new consumption formats and adjacent product categories.
Craft Vodka Market Key Takeaways
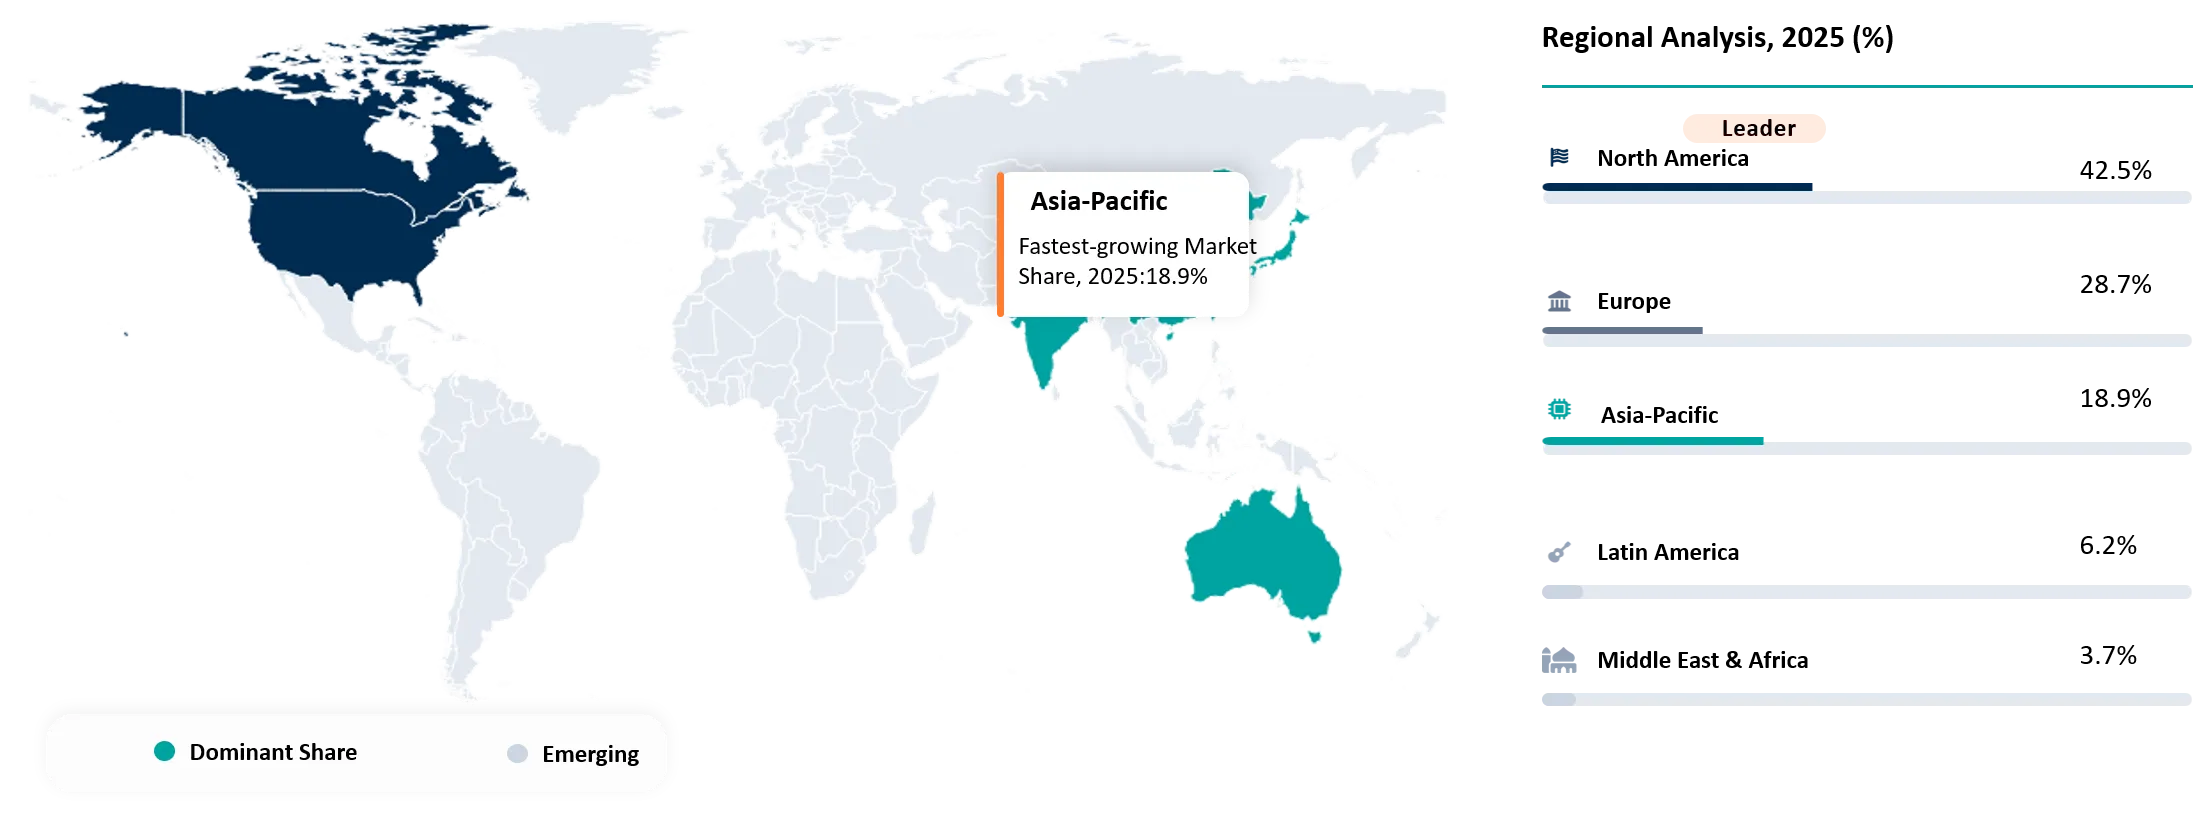
- North America captured the largest regional market share at 42.50% in 2025, supported by established craft distillery networks, premium spirits consumption, and strong availability of locally produced vodka. Asia-Pacific is projected to be the fastest-growing region, with 18.90% share in 2025, driven by indigenous ingredients, premiumization, and expansion of craft distilling.
- Grain-based craft vodka dominated by raw material, accounting for approximately 52.00% of the market in 2025, reflecting widespread use of wheat, corn, rye, and other grains in craft production. Grape-based vodka is projected to be the fastest-growing segment, with an estimated 8.20% CAGR, supported by premium positioning and distinctive fruit-derived production.
- Craft vodka producers are expanding into new production facilities and distillery operations, improving their ability to scale small-batch production while maintaining localized manufacturing.
- Distillers are introducing locally sourced and distinctive raw materials, including regional grains, rice, potatoes, fruits, and specialty agricultural ingredients, to differentiate craft vodka offerings.
- Producers are expanding premium and limited-edition vodka launches, using unique flavors, regional provenance, and specialized production methods to strengthen product differentiation.
Craft Vodka Market Industry Trends and Strategic Insight
- The shift toward premium spirits is increasing demand for craft vodka with distinctive ingredients, production methods, and provenance.
- Consumer preference for locally sourced ingredients is strengthening demand for regional grain, potato, grape, and specialty-based vodka expressions.
- Expanding cocktail culture is increasing demand for versatile craft vodka across premium bars, restaurants, hospitality venues, and home consumption.
- Growing distillery tourism is increasing demand for craft vodka linked to tasting experiences, local production, and direct consumer engagement.
- Expansion of online alcohol retail is improving accessibility to craft vodka products, particularly for independent distillers targeting geographically dispersed premium consumers.
Craft Vodka Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 5.6 Billion | |
| 2035 Projected Market Size | USD 10.81 Billion | |
| CAGR (2026-2035) | 6.8% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Raw Material | Grain, Potato, Grape, Corn, Others | |
| By Type | Flavored, Unflavored | |
| By Distiller Type | Large Distilleries, Medium Distilleries, Small Distilleries | |
| By Distillation Method | Column Distillation, Pot Still Distillation, Hybrid Distillation | |
| By Distribution Channel | On-Trade, Off-Trade | |
| By End User | Individual Consumers, Bars, Pubs & Restaurants, Hotels & Resorts, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, United Kingdom, France, Italy, Spain, Netherlands, Switzerland, Sweden, Norway, Denmark, Belgium, Poland, Austria, Ireland, Portugal, Greece, Finland, Rest of Europe | |
| Asia-Pacific | China, Japan, India, South Korea, Australia, New Zealand, Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines, Taiwan, Rest of Asia Pacific | |
| Latin America | Brazil, Argentina, Chile, Colombia, Peru, Rest of Latin America | |
| Middle East and Africa | Saudi Arabia, United Arab Emirates, Qatar, Kuwait, Oman, Bahrain, South Africa, Egypt, Nigeria, Morocco, Rest of Middle East & Africa | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Craft Vodka Market Disruption Analysis
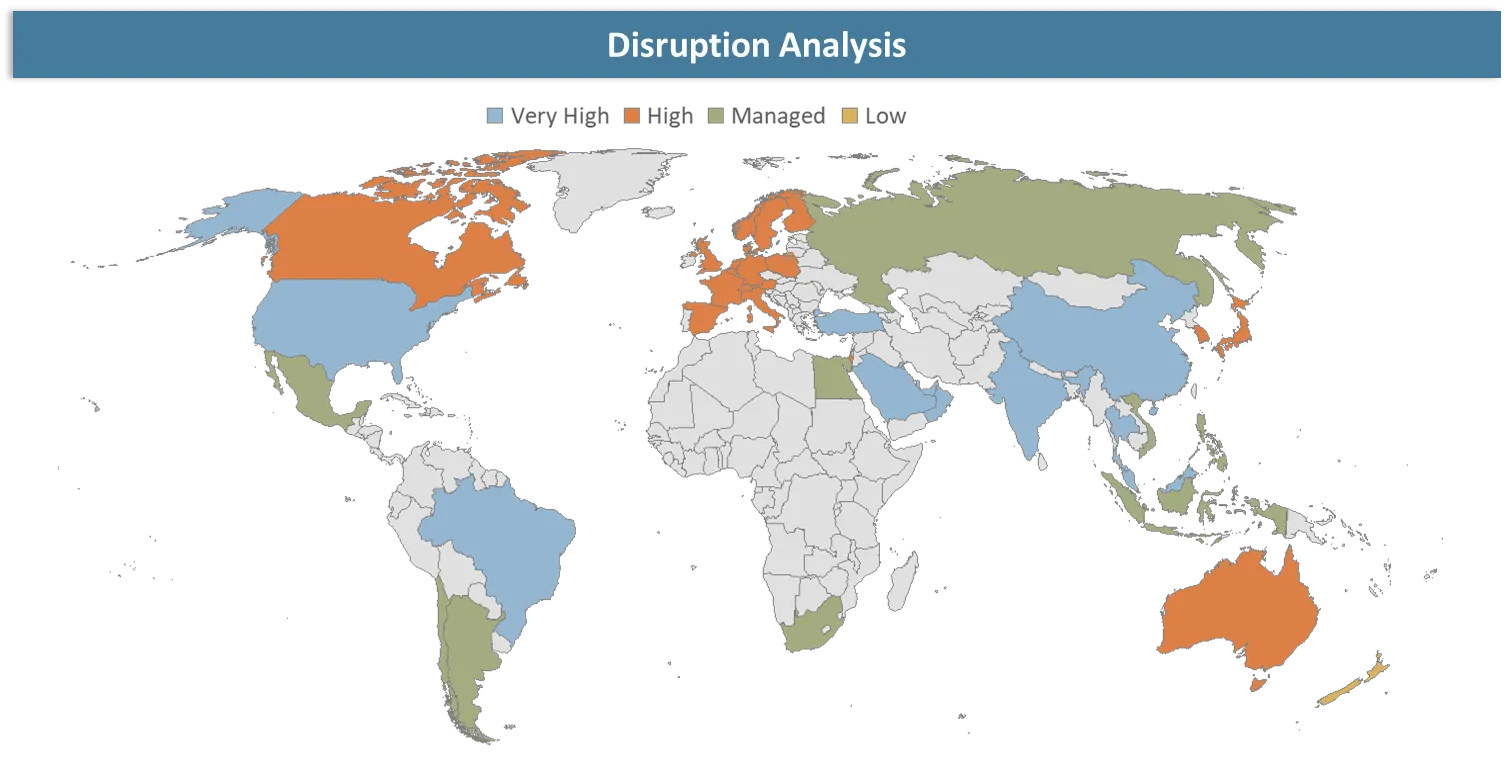
Shift Toward Experiential and Format-Expanded Craft Vodka
The craft vodka market is shifting from conventional bottled spirits toward experiential production, distinctive provenance, and broader consumption formats. Distillers are using local ingredients, specialized filtration, small-batch processes, and immersive distillery experiences to differentiate their products. This transition is expanding the role of craft vodka from a premium spirit proposition toward a broader product, experience, and lifestyle offering.
The shift is also encouraging craft distillers to develop new formats and production ecosystems around their vodka portfolios. In April 2026, Goodnight Loving Vodka announced a new distillery and tasting facility in Dripping Springs, Texas, bringing its spring-to-bottle production under one roof and planning production capacity exceeding one Billion cases annually. The development indicates movement toward integrated distillery experiences and scaled craft production, combining manufacturing, brand experience, and direct consumer engagement within a single operating model.
Craft Vodka Market BCG Matrix: Company Evaluation
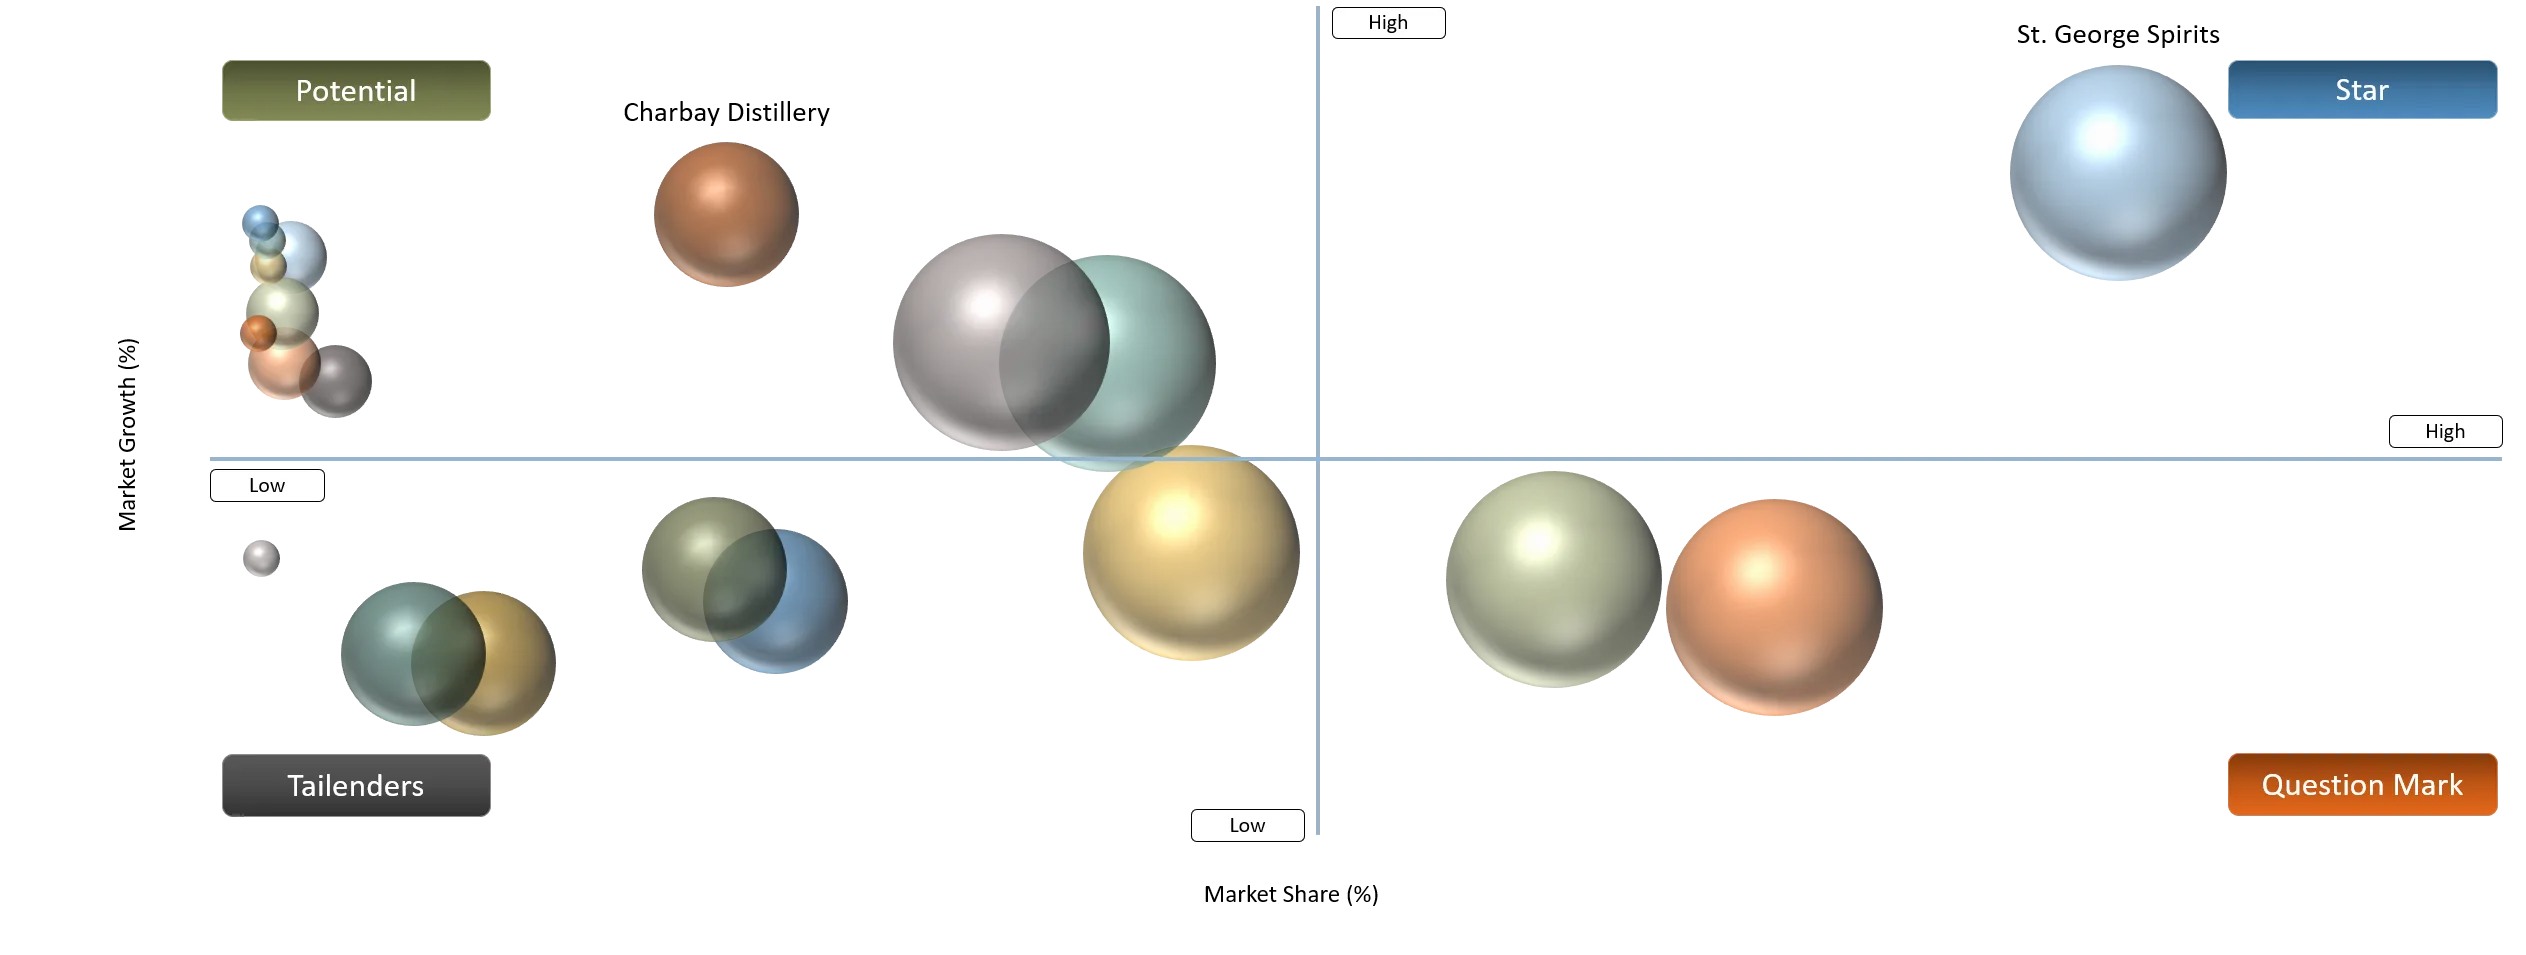
The Stars position is led by Fifth Generation, Inc. (Tito’s), St. George Spirits, Woody Creek Distillers, and Valentine Distilling Co., supported by established craft vodka production, strong product recognition, direct distillery operations, and differentiated production approaches. The Potential Companies category includes Charbay Distillery, Cardinal Spirits, Broken Shed Vodka, and Tommyrotter Distillery, supported by small-batch production, distinctive ingredients, and established craft-distilling capabilities.
The Question Marks category comprises Brewhouse Spirits Ltd. t/a Uncommon Distillery, Heart of Scotland Distillery, and 44 North Vodka, where smaller-scale distillery operations and regional positioning provide scope for wider market penetration.
Craft Vodka Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Premiumization drives consumer preference toward distinctive small-batch vodka offerings globally | 25% | High demand across premium spirits consumers seeking differentiated, artisanal, and higher-quality vodka products. | Premium cocktails, home consumption, gifting, upscale bars and restaurants. | Encourages craft distillers to expand premium portfolios, distinctive formulations, and higher-value product offerings. |
Consumer demand favors locally sourced ingredients and authentic production stories | 21% | Concentrated among consumers prioritizing provenance, regional identity, transparency, and artisanal production. | Retail purchases, tasting experiences, premium gifting, destination consumption. | Strengthens local sourcing strategies, origin-based branding, ingredient differentiation, and distillery-level storytelling. |
Cocktail culture expands demand for premium craft vodka products | 20% | Strong demand across cocktail-focused bars, restaurants, mixology venues, and premium home consumers. | Craft cocktails, premium mixed drinks, bars, restaurants, and hospitality venues. | Drives development of versatile vodka expressions, flavor variants, and bartender-focused product portfolios. |
Experiential drinking encourages exploration of artisanal spirits with unique profiles | 18% | Concentrated across distillery tourism markets, specialty retailers, tasting rooms, and premium hospitality. | Distillery tours, tastings, cocktail experiences, specialty retail, and gifting. | Encourages investment in visitor experiences, limited releases, distinctive profiles, and direct consumer engagement. |
Direct-to-consumer channels improve accessibility for independent craft vodka producers | 16% | Strongest among digitally engaged consumers and markets permitting online alcohol sales. | Online retail, direct distillery sales, subscription programs, and product discovery. | Expands consumer reach, improves brand visibility, and enables independent distillers to build direct customer relationships. |
Premiumization Driving Demand for Distinctive Craft Vodka
Premiumization is strengthening demand for craft vodka differentiated through regional ingredients, specialized production, limited releases, and distinctive flavor profiles. Consumers are placing greater emphasis on provenance and production authenticity, giving independent distillers opportunities to differentiate from standardized vodka offerings. This is also encouraging experimentation with locally sourced ingredients and small-batch production approaches.
In June 2026, Atlanta Distillery released its 2026 Dragon Con Vodka, a limited-edition small-batch vodka produced locally in Marietta, Georgia, with packaging featuring artwork selected through Dragon Con's annual bottle-art competition. The release demonstrates how craft vodka producers are combining limited production, local manufacturing, and experiential brand positioning to differentiate individual vodka expressions.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Higher production costs constrain craft vodka pricing competitiveness against mass-market brands | 24% | Production economics, pricing, and margin management | Premium retail, bars, restaurants, and mainstream spirits channels | Increases unit costs and limits pricing flexibility against large-scale vodka producers with greater production efficiencies. |
Limited production capacity restricts scalability for small independent distilleries | 21% | Manufacturing capacity, inventory availability, and order fulfillment | Retail expansion, hospitality supply, export orders, and seasonal demand | Constrains volume expansion and creates supply limitations when craft distilleries enter broader distribution markets. |
Stringent alcohol regulations increase compliance costs across international markets | 20% | Licensing, labeling, taxation, production, and market-entry compliance | Cross-border sales, exports, online alcohol sales, and retail distribution | Raises market-entry requirements and administrative costs, particularly for independent distillers entering new countries. |
Premium retail prices limit adoption among price-sensitive consumers globally | 19% | Consumer affordability, retail penetration, and product conversion | Household consumption, mainstream retail, and entry-level premium spirits | Restricts consumer conversion where craft vodka prices exceed established mainstream and premium vodka alternatives. |
Higher Production Costs Constraining Pricing Competitiveness
Higher production costs remain a significant restraint for craft vodka producers because small-batch distillation generally involves lower production volumes and less scale efficiency than large vodka manufacturers. Costs associated with premium ingredients, specialized distillation, filtration, labor, packaging, and energy can raise the finished product price. This limits pricing flexibility when craft vodka competes with established mass-market and premium vodka brands.
The impact is particularly relevant when independent distilleries expand beyond regional markets and enter mainstream retail or hospitality channels. Higher unit costs can compress margins if producers reduce prices to improve market penetration, while maintaining premium pricing can restrict consumer adoption. Consequently, craft distillers face a continuing balance between production economics, premium positioning, and broader distribution.
Craft Vodka Market Segment Analysis
The craft vodka segmentation is based on the raw material, type, distiller type, distillation method, distribution channel, end user, and region.
Grain-Based Vodka Maintains Dominance Through Heritage Ingredients and Craft Distillation
Grain remains the dominant raw material segment in craft vodka, supported by its broad use across wheat, corn, rye, and other cereal-based distillation. Craft producers are increasingly differentiating grain-based vodka through heritage varieties, organic sourcing, local provenance, and specialized distillation processes. This combination enables producers to retain traditional vodka production characteristics while creating distinctive premium expressions.
In May 2025, Piccadily Agro Industries launched CASHMIR, a small-batch luxury vodka made from heritage organic Indian winter wheat and Kashmir Valley water. The vodka undergoes seven-times distillation, combining a differentiated grain source with a specialized production process. The launch demonstrates how craft vodka producers are using premium and heritage grain varieties to strengthen product differentiation within the dominant grain-based segment.
Craft Vodka Market Geographical Penetration
North America Strengthening Through Craft Vodka Portfolio Development
North America dominates the craft vodka market due to its established independent distillery base, strong premium spirits culture, and broad availability of locally produced vodka. U.S. craft distillers are differentiating vodka through specialized distillation, filtration, distinctive formulations, and locally established distillery identities. The region also benefits from an established craft spirits infrastructure spanning tasting rooms, specialty retail, hospitality, and direct consumer engagement.
In March 2026, Sugarlands Distilling Company continued its High Rock Vodka partnership with JR Motorsports, extending the presence of its handcrafted vodka through a major U.S. sports platform. High Rock is produced by Sugarlands, a Tennessee craft distillery, using seven-times distillation and triple filtration through sugar-maple charcoal. The development demonstrates how U.S. craft vodka producers are combining specialized production techniques with broader domestic brand activation to expand the visibility of craft vodka offerings.
U.S. Craft Vodka Market Trends
The U.S. leads North America's craft vodka market through its large base of independent distilleries and strong product experimentation. Producers are using regional ingredients, specialized filtration, small-batch production, and differentiated formulations to establish distinctive vodka propositions. The country's established craft spirits infrastructure also provides producers with access to specialty retail, hospitality, and direct consumer channels.
In September 2026, Eastern Kille Distillery released its Graham Cracker Vodka, demonstrating continued experimentation with distinctive flavor profiles within U.S. craft vodka production. The release illustrates how American craft distilleries are expanding beyond conventional vodka profiles through limited and differentiated expressions.
Asia Pacific Strengthening Through Indigenous Ingredients and Craft Vodka Innovation
Asia Pacific is the fastest-growing craft vodka region, driven by expanding domestic premium spirits production and greater use of region-specific ingredients. Producers are combining local grains, traditional filtration techniques, and regional distilling expertise to create differentiated vodka expressions. Japan and India are emerging as notable markets for craft vodka development, particularly through rice- and heritage-grain-based production.
In September 2025, Globus Spirits launched TERAI India Craft Vodka, produced from locally sourced rice at its Behror, Rajasthan distillery and filtered through amethyst crystals. The launch demonstrates the region's emphasis on locally sourced agricultural inputs and distinctive production techniques within premium craft vodka.
Japan Craft Vodka Market
Japan's craft vodka segment is differentiated by the use of domestic rice and traditional Japanese production techniques. Japanese distillers are incorporating rice-based distillation, bamboo charcoal filtration, and regional craftsmanship into vodka production, creating products with distinct provenance. This positions Japan as a specialized craft vodka market within Asia Pacific.
In June 2025, Shinshu Shirakaba Craft Manufacturing announced development of YURAGI Japanese craft vodka, using sake lees-derived spirits from the Saku region, birch tea flavoring, and birch charcoal filtration. The development demonstrates how Japanese producers are incorporating regional agricultural by-products and locally distinctive filtration techniques into craft vodka production.
Craft Vodka Market Competitive Landscape
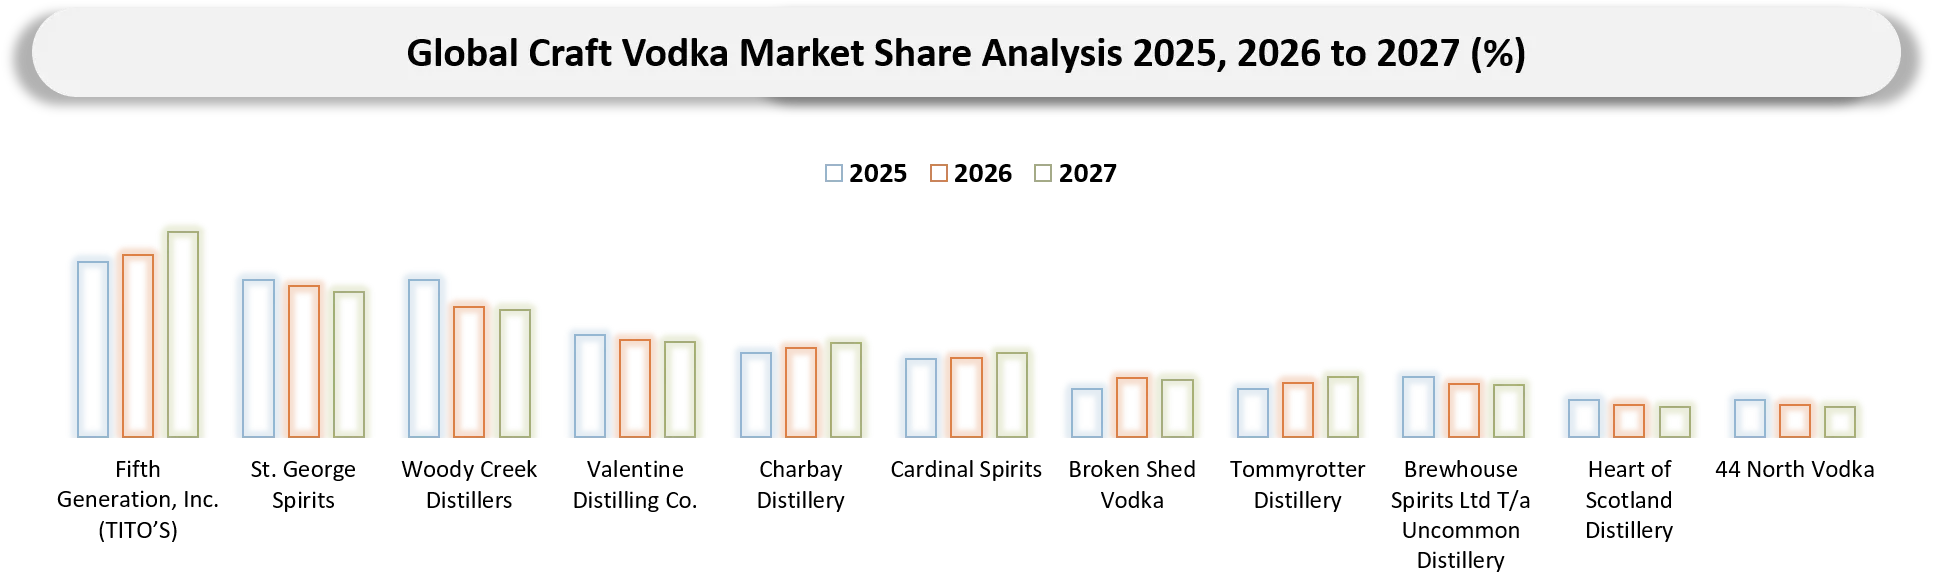
- Key players include Fifth Generation, Inc. (TITO’S), St. George Spirits, Woody Creek Distillers, Valentine Distilling Co., Charbay Distillery, Cardinal Spirits, Broken Shed Vodka, Tommyrotter Distillery, Brewhouse Spirits Ltd T/a Uncommon Distillery, Heart of Scotland Distillery, 44 North Vodka
Key Developments
- September 14, 2026: House of Suntory launched Haku Japanese Craft Vodka's first global brand campaign, emphasizing its 100% Japanese white rice production and Japanese craftsmanship. The development strengthens the positioning of rice-based Japanese vodka around regional provenance, specialized production, and premium cocktail applications.
- September 14, 2026: Sazerac completed the acquisition of UK-based Au Vodka for more than £300 Billion, expanding its premium vodka portfolio. The transaction demonstrates continued consolidation around differentiated vodka brands and strengthens the presence of established spirits companies in the premium vodka segment.
- September 2026: Adie Broswon Group launched MOOOZ Litchi Vodka in India, expanding its flavored vodka portfolio with a fruit-forward expression designed for straight serves and cocktails.
- February 2026: Boatman Spirits Co. launched its first spirits, including vodka produced on-site at its newly established Raleigh, North Carolina distillery, combining local production with an integrated restaurant and distillery model.
- May 2026: Piccadily Agro Industries launched CASHMIR as a small-batch luxury vodka made from heritage organic Indian winter wheat and Kashmir Valley water. The launch demonstrates the use of regional agricultural inputs and provenance-led production to differentiate premium craft vodka offerings.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organizations procuring craft vodka increasingly prioritize product quality, distinctive ingredients, production authenticity, and consistent flavor profiles across premium offerings.
- Procurement decisions among retailers, distributors, hospitality operators, and specialty alcohol buyers are increasingly influenced by brand differentiation, consumer appeal, pricing, packaging, production capacity, and regulatory compliance.
- Buyers evaluate craft vodka suppliers based on raw material quality, distillation method, product consistency, alcohol content, certifications, production capacity, packaging, shelf life, pricing, supply reliability, distribution coverage, and brand positioning when selecting vodka producers.
Why Choose DataM?
- Product Innovation: Evaluates advancements in craft vodka production, including specialized distillation, heritage grains, locally sourced ingredients, filtration techniques, flavor development, and small-batch manufacturing approaches that differentiate premium vodka offerings.
- Product Performance & Market Positioning: Assesses craft vodka products based on raw material quality, distillation method, flavor profile, alcohol content, production authenticity, packaging, pricing, and premium positioning, highlighting how distillers differentiate their portfolios.
- Real-World Evidence: Highlights craft vodka launches, new distillery facilities, production expansions, limited releases, awards, and regional ingredient initiatives, demonstrating how manufacturers are developing distinctive products and expanding consumer reach.
- Market Updates & Industry Changes: Tracks developments in craft distillery expansion, premium vodka launches, flavored vodka innovation, locally sourced ingredient adoption, ready-to-drink formats, experiential consumption, and regional craft spirits development across North America, Europe, and Asia-Pacific.
- Competitive Strategies: Analyzes how craft vodka producers strengthen market positions through product diversification, distinctive raw materials, small-batch production, direct-to-consumer channels, tasting experiences, strategic partnerships, limited releases, and geographic expansion.
- Pricing & Market Access: Explains pricing differences based on raw materials, production scale, distillation complexity, packaging, product positioning, and distribution structure, alongside market access through specialty retailers, liquor stores, hospitality establishments, tasting rooms, e-commerce, and distributors.
- Market Entry & Expansion: Identifies opportunities arising from premium spirits demand, regional ingredient differentiation, craft distillery development, flavored vodka innovation, direct-to-consumer sales, tourism-driven tasting experiences, and emerging craft spirits markets, while assessing distribution partnerships and localized production strategies.
Target Audience 2026
- Craft Vodka Distilleries and Manufacturers
- Independent and Small-Batch Distillers
- Premium Spirits Brands and Producers
- Alcohol Beverage Distributors and Importers
- Liquor Retailers and Specialty Spirits Stores
- Bars, Restaurants, Hotels and Hospitality Operators
- Spirits Wholesalers and E-Commerce Alcohol Retailers



























































