


Automotive Steel Market Size and Overview
The global automotive steel market reached USD 127.5 billion in 2025 and is expected to reach USD 174.7 billion by 2035, growing with a CAGR of 3.2% during the forecast period 2026-2035. The market is witnessing sustained demand as automakers increase the use of advanced high-strength steels (AHSS), press hardening steels, and low carbon steel by car manufacturers in order to ensure reduction of weight of the vehicle, crash performance, and reduce lifecycle emissions. According to ArcelorMittal has shown that there are various advanced steel grades used in the Emblème project in collaboration with Renault, where 56 components made from press hardening steel of weight 86.2kg, 16 components of martensitic steel of weight 28.7kg, 36 components of ferrite bainite of weight 19.2kg, 20 components of complex phase steel of weight 11.4kg, and 8 components of high formability steel of weight 5.7kg.
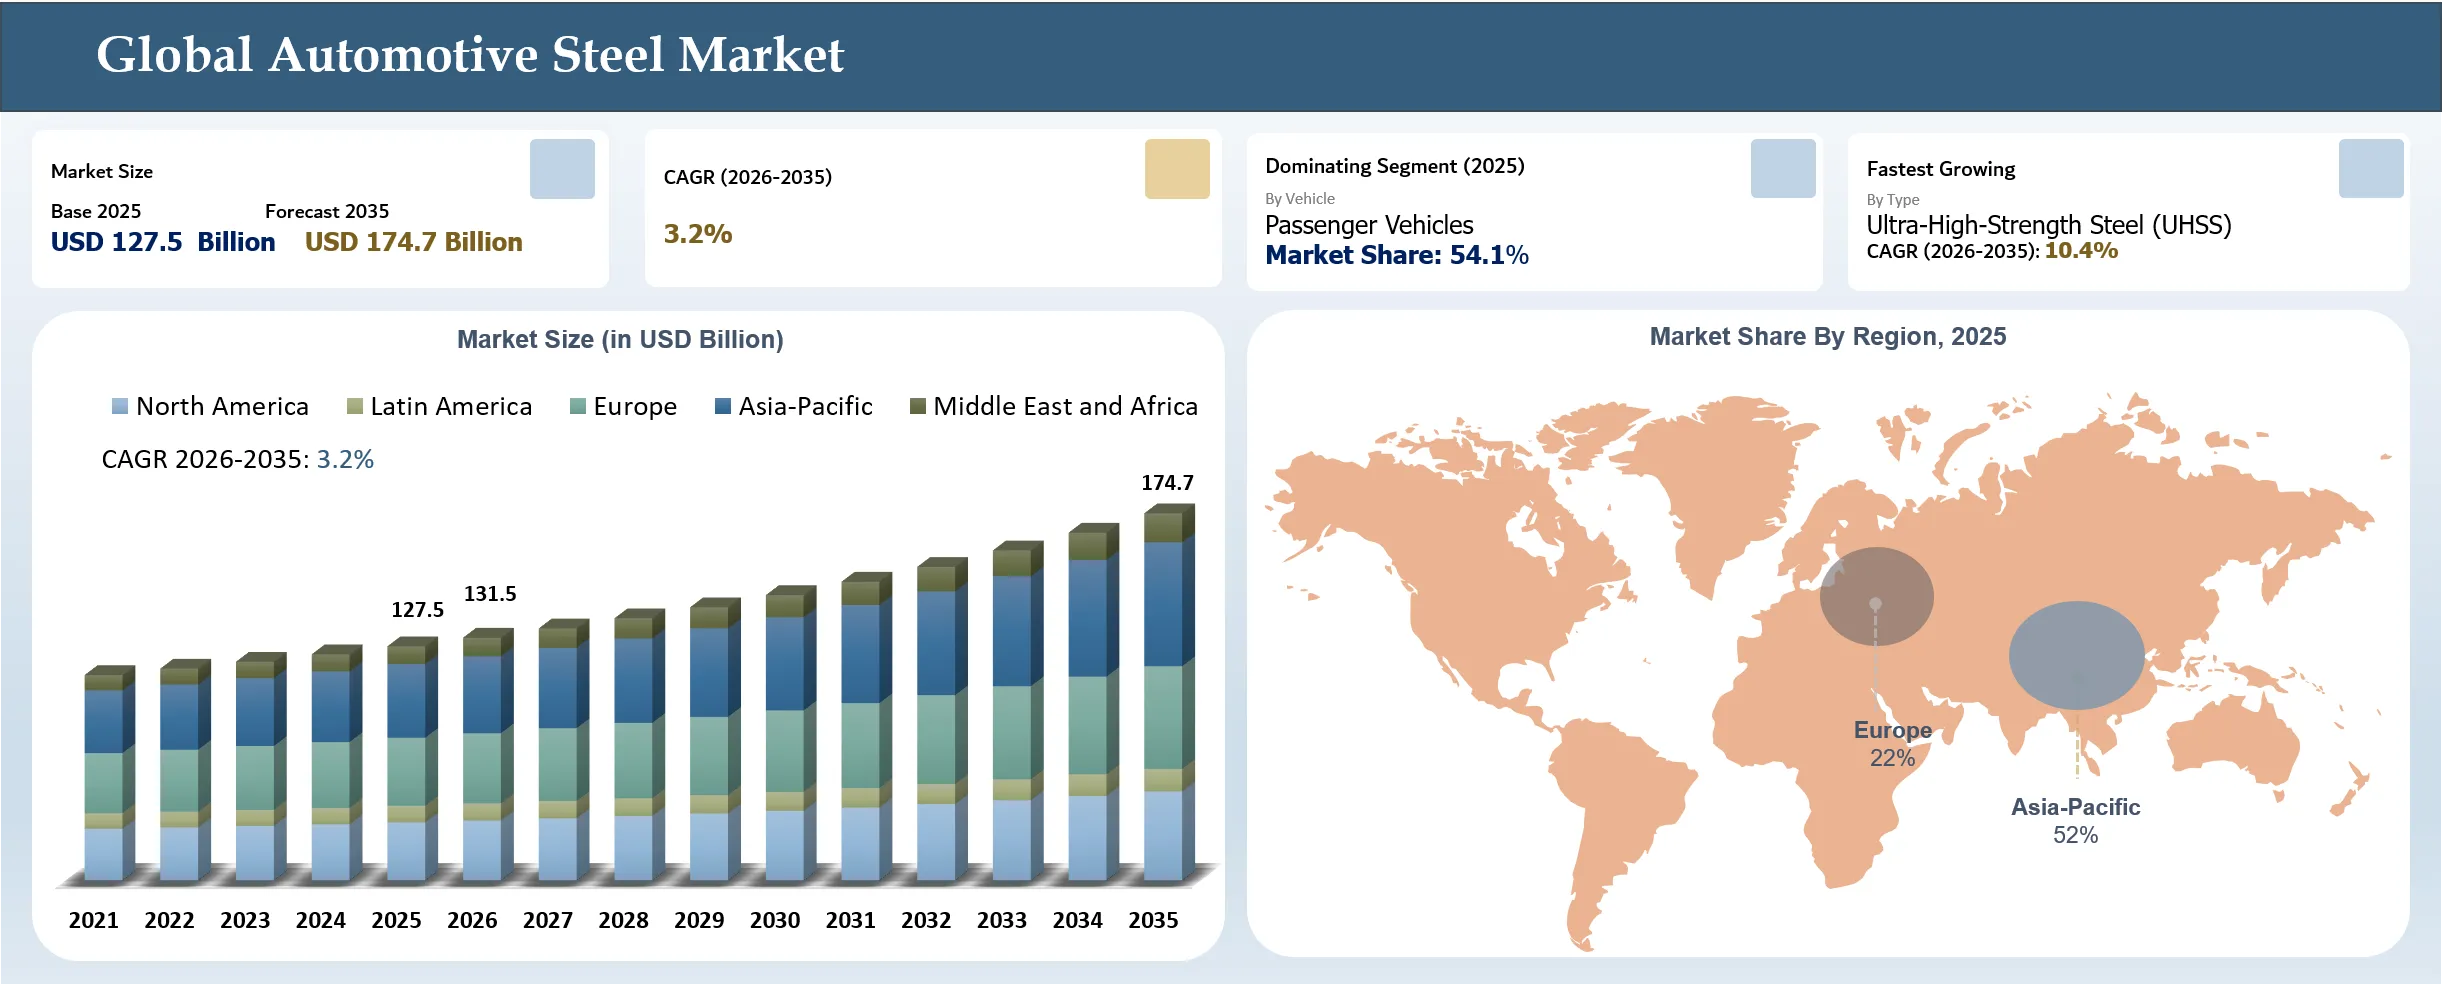
The use of these steels has ensured a reduction of CO2 emissions by 69% for the body in white in comparison with Renault's reference body in white, whereas the overall Emblème concept ensures a reduction of lifecycle CO2 emissions by 90%. Lower-carbon automotive steel is not only affecting how automobiles are made, but it is also playing a role in steel prices, steel manufacturing strategies, and purchasing deals. In August 2026, according to CHOSUNBIZ, POSCO and Hyundai Steel were discussing higher steel sheet prices for automakers due to higher raw material costs as well as higher operating costs.
The two companies have planned to increase their prices in the second half of 2026. POSCO had a KRW 490 billion (USD 355 million) operating profit in the first half of 2026, which represents a 43% decline from last year’s figures, whereas Hyundai Steel had a KRW 61.4 billion (USD 44.3 million) operating loss for the same period.
White-Space Opportunities for the Canadian Automotive Steel Market Driven by Government Funding and Regional Tariff Support
In May 2026, the Government of Canada announced C$1 billion (USD 714.9 million) in financing through the Business Development Bank of Canada (BDC) for Canadian companies producing or manufacturing products containing steel, aluminum, or copper and affected by U.S. tariffs, alongside an additional C$500 million (USD 357.4 million) through the Regional Tariff Response Initiative (RTRI) for tariff-impacted businesses.
Within the existing C$1 billion (USD 714.9 million) RTRI allocation, C$150 million (USD 107.2 million) was specifically carved out for steel producers and C$100 million (USD 71.5 million) for automotive, while the additional C$500 million (USD 357.4 million) includes C$200 million (USD 142.96 million) for SMEs affected by steel, aluminum and copper tariffs, making steel manufacturing and metal-intensive industrial production the most directly targeted investment area.
The additional RTRI funding is distributed across regional agencies, with the Federal Economic Development Agency for Southern Ontario receiving the largest allocation of C$215 million (USD 153.7 million), followed by Prairies Economic Development Canada at C$80 million (US$57.2 million), Canada Economic Development for Quebec Regions at C$105 million (USD 75.0 million), Pacific Economic Development Canada at C$50 million (USD 35.7 million), Atlantic Canada Opportunities Agency at C$30 million (USD 21.4 million), Federal Economic Development Agency for Northern Ontario at C$15 million (USD 10.7 million), and Canadian Northern Economic Development Agency at C$5 million (USD 3.6 million).
The investment is creating opportunities across Canada’s steel and metal manufacturing ecosystem, particularly in steel fabrication, structural steel production, automotive components, metal processing, advanced manufacturing, and automation. Companies such as Ocean Steel & Construction Ltd., Fabrication Beauce-Atlas Inc., Métal Perreault Inc., and Canada Steel Corporation can benefit from opportunities to expand steel fabrication capacity, modernize production lines, improve processing efficiency, and adopt automated manufacturing technologies.
In the automotive-steel segment, ArcelorMittal, Algoma Steel, Stelco, Dofasco, Magna International, Linamar, Martinrea International, and Multimatic can benefit through opportunities involving automotive-grade steel production, lightweight vehicle structures, stamping, body components, metal forming, and localized automotive supply chains. Steel-processing and advanced manufacturing companies such as Samuel, Son & Co., Russel Metals, Varsteel, Walters Group, and AGF Steel can capture opportunities in steel distribution, processing, structural fabrication, precision manufacturing, and downstream value-added products.
Automotive Steel Market Key Takeaways
- Asia-Pacific dominated the market with a 52% global share in 2025. Asia-Pacific vehicle production grew 7.6% to 59.2 million units, accounting for 61% of global production.
- Passenger vehicles led the overall automotive steel market by capturing a 54.1% market share in 2025. Growth targets emission reductions and structural lightweighting across body components.
- Vingroup established VinMetal in October 2025 with VND 10 trillion (USD 380 million) in initial investment capital. Phase 1 aims to establish a capacity of 5 million tonnes per year in Vietnam.
- Canada launched C$1 billion (USD 714.9 million) in BDC financing in May 2026 for metal businesses impacted by tariffs. An additional C$500 million (USD 357.4 million) was provided through the Regional Tariff Response Initiative.
Automotive Steel Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 127.5 Billion | |
| 2035 Projected Market Size | USD 174.7 Billion | |
| CAGR (2026-2035) | 3.2% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | Europe | |
| By Type | Low-Strength Steels, High Strength Steel (HSS), Ultra-High-Strength Steel (UHSS), Advanced High Strength Steel (AHSS), Others | |
| By Vehicle | Passenger Vehicles, Commercial Vehicles, Others | |
| By Application | Structural Assembly & Closures, Bumpers, Suspension, Rims, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Automotive Steel Market BCG Matrix: Company Evaluation
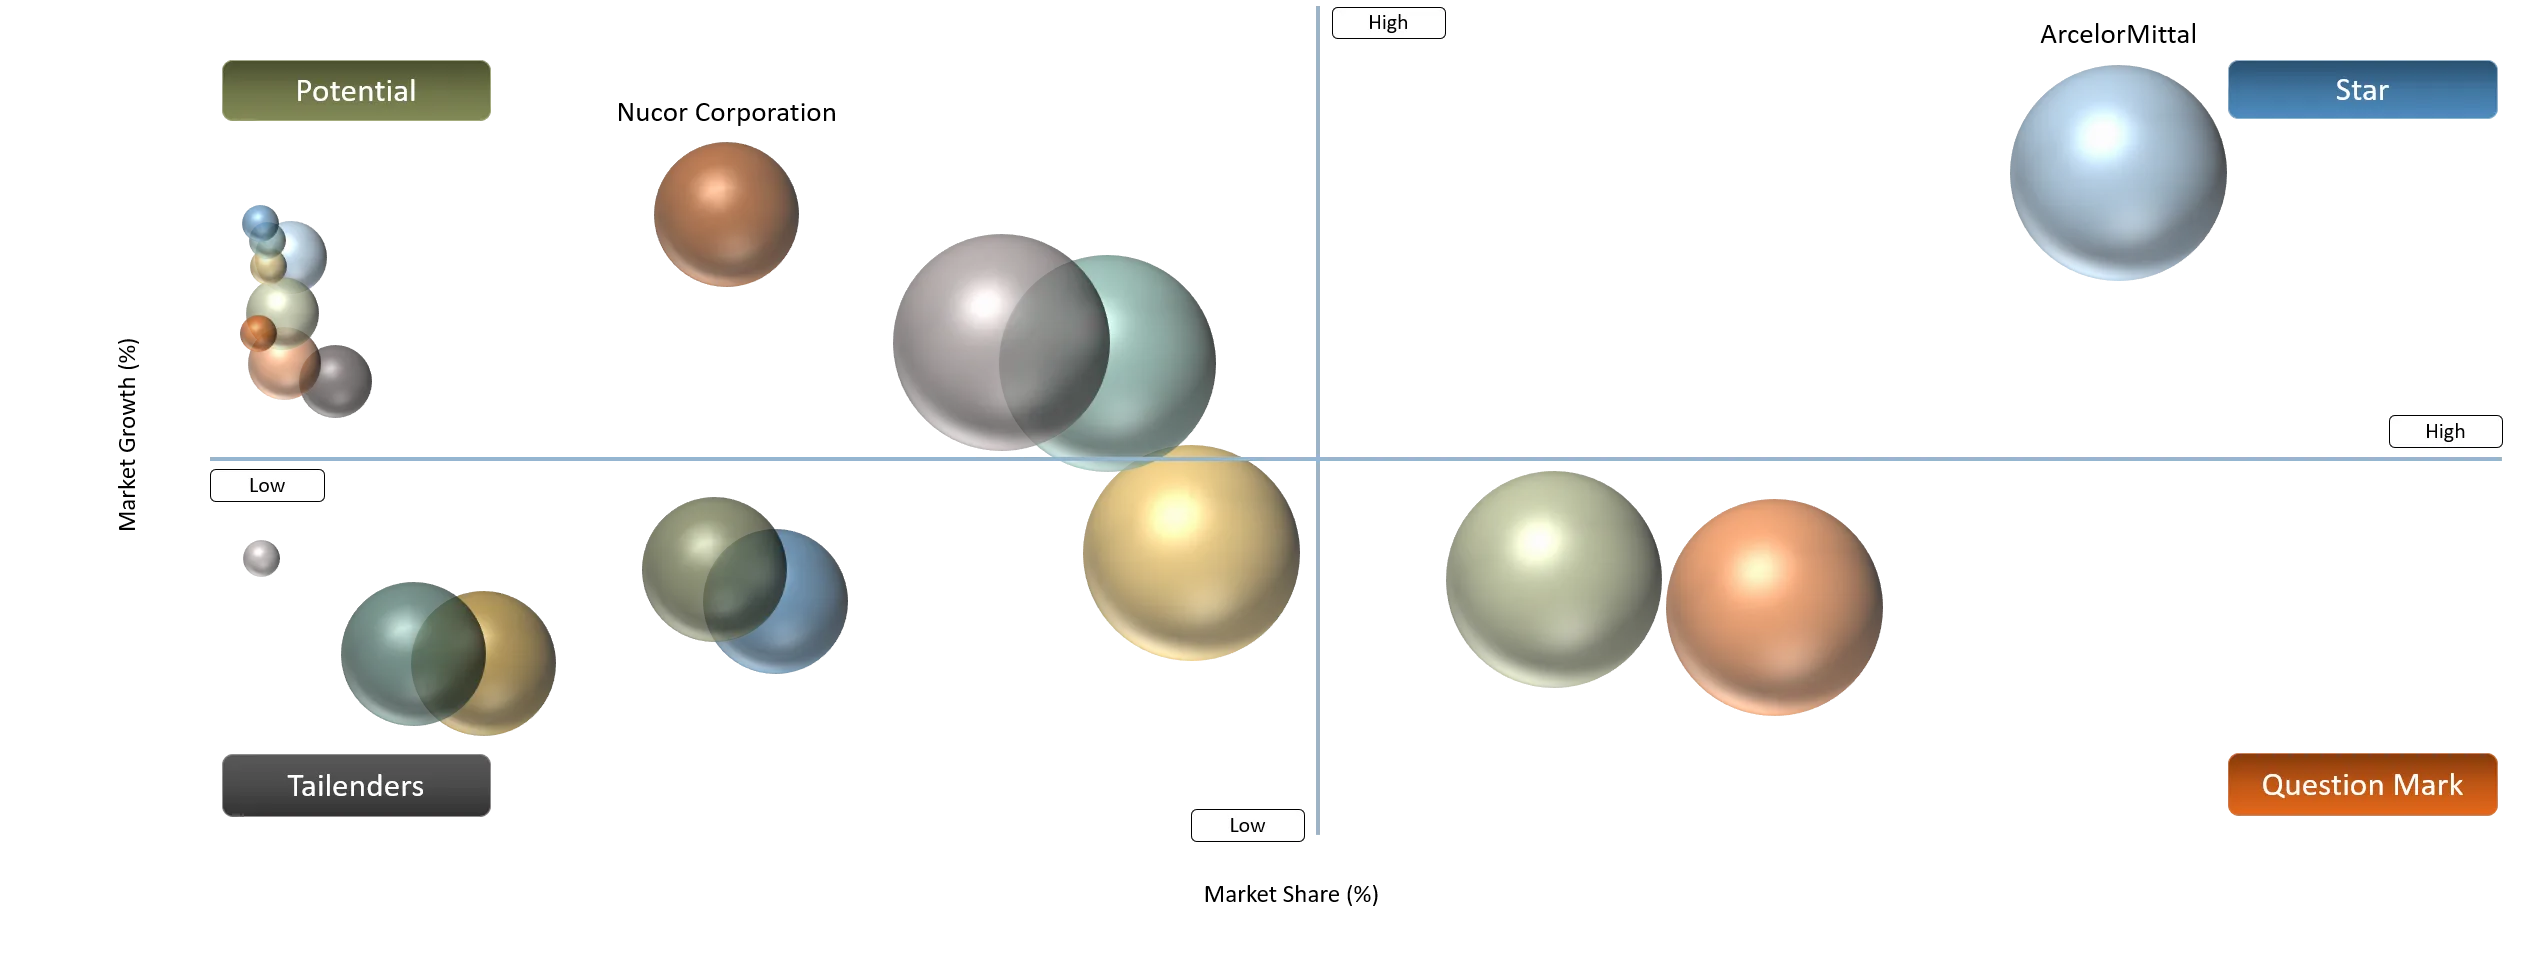
Stars include ArcelorMittal, Nippon Steel Corporation, POSCO, and Baosteel because they have strong positions in automotive-grade steel and broad capabilities across advanced high-strength steel (AHSS), ultra-high-strength steel (UHSS), coated steel, and other automotive applications. Question Marks include HBIS Group, JFE Steel Corporation, Tata Steel, and Hyundai Steel Company. The companies have established automotive steel businesses and are expanding their capabilities in AHSS, automotive sheets, lightweight materials, and lower-carbon steel.
Potential includes Nucor Corporation, which has a significant North American steel manufacturing presence and is expanding its automotive sheet-steel capabilities. Tailenders include U.S. Steel Corporation, reflecting its comparatively narrower global automotive-steel footprint following its position within the U.S. steel industry.
Automotive Steel Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Rising adoption of advanced high-strength steel (AHSS) and ultra-high-strength steel (UHSS) is enabling automakers to reduce vehicle weight. | 30% | Passenger vehicles, EVs, body structures and safety components | Body-in-White (BIW), structural assemblies, closures, bumpers and suspension | Accelerates substitution of conventional grades with higher-strength steel, supporting lightweight vehicle design while maintaining crash performance. |
Growing automotive decarbonization targets are driving automakers toward low-carbon and recycled steel produced through electric-arc-furnace and renewable-electricity routes. | 25% | Europe, North America and major global automotive production hubs | Body structures, closures, chassis and other high-volume steel components | Increases demand for low-carbon automotive steel and strengthens steelmaker–OEM collaboration around emissions reduction and recycled-content procurement. |
Increasing demand for lower-carbon automotive supply chains is encouraging automakers to establish steel procurement. | 20% | Global OEM supply chains, particularly Europe and North America | Automotive sheet steel, structural components and body panels | Creates opportunities for long-term supply agreements, certified low-emission steel and traceable material sourcing, strengthening differentiation among steel suppliers. |
Stricter vehicle safety requirements are supporting demand for advanced steel grades capable of improving crash resistance while controlling structural weight. | 25% | Passenger vehicles and commercial vehicles; safety-critical vehicle structures | Crash-management systems, pillars, rails, bumpers, doors and passenger-cell structures | Supports continued penetration of AHSS, UHSS and press-hardened steel, encouraging development of stronger grades with improved formability and energy absorption. |
Rising adoption of advanced high-strength steel (AHSS) and ultra-high-strength steel (UHSS) is enabling automakers to reduce vehicle weight
The rapid adoption of Advanced High Strength Steels (AHSS) and Ultra-High Strength Steels (UHSS) by the auto industry has been growing in recent times as the industry looks for ways to lighten up vehicles while retaining their structural soundness and crash resistance. In November 2025, according to WorldAutoSteel, the number of AHSS grades commercially available increased from 38 in 2017 to almost 70 due to the ongoing trend within the industry of using light and strong steel.
In parallel, the lightweighting advantages of advanced automotive steel are becoming more compelling, thus encouraging the use of these materials in future vehicles. According to the U.S. Department of Energy (DOE), Lightweight and Propulsion Materials, a 10% reduction in vehicle mass translates to a 6%-8% improvement in fuel economy, and substitution of high-strength steel and other lightweight materials for heavy steel components results in a 10%-60% weight reduction of the components. In addition, the DOE points out the significance of lightweight materials for hybrid, plug-in hybrid, and electric vehicles due to the increased weight of the batteries and electric motors.
Automotive Steel Market Segment Analysis
The global automotive steel market is segmented based on type, vehicle, application, and region.
Passenger Vehicles Dominating the Automotive Steel Market Through High-Volume Vehicle Production and Lightweighting Demand
The passenger vehicles segment dominates the automotive steel market, contributing a 54.1% market share in 2025. The market leadership of this segment can be attributed to the widespread application of automotive steel in passenger cars for body structures, closures, crash management systems, suspension components, and other parts critical to the safety of the vehicle.
The strong concentration of global vehicle manufacturing in Asia-Pacific is supporting sustained demand for automotive steel. In April 2026, according to the International Organization of Motor Vehicle Manufacturers (OICA), the Asia-Pacific region was still the biggest manufacturer of cars, having increased car production by 7.6% to 59.2 million units, which was 61% of worldwide production. China made 34.53 million cars, whereas India made 6.49 million cars and had domestic sales of 4.6 million passenger cars in fiscal year 2025-26. Japan also made 8.41 million cars. The presence of so many car manufacturers is an indication that there is continuous demand for automotive steel, especially for use in passenger cars.
Automotive Steel Market Geographical Penetration
Asia-Pacific Dominance Driven by Expanding Vehicle Production and Automotive Manufacturing Capacity
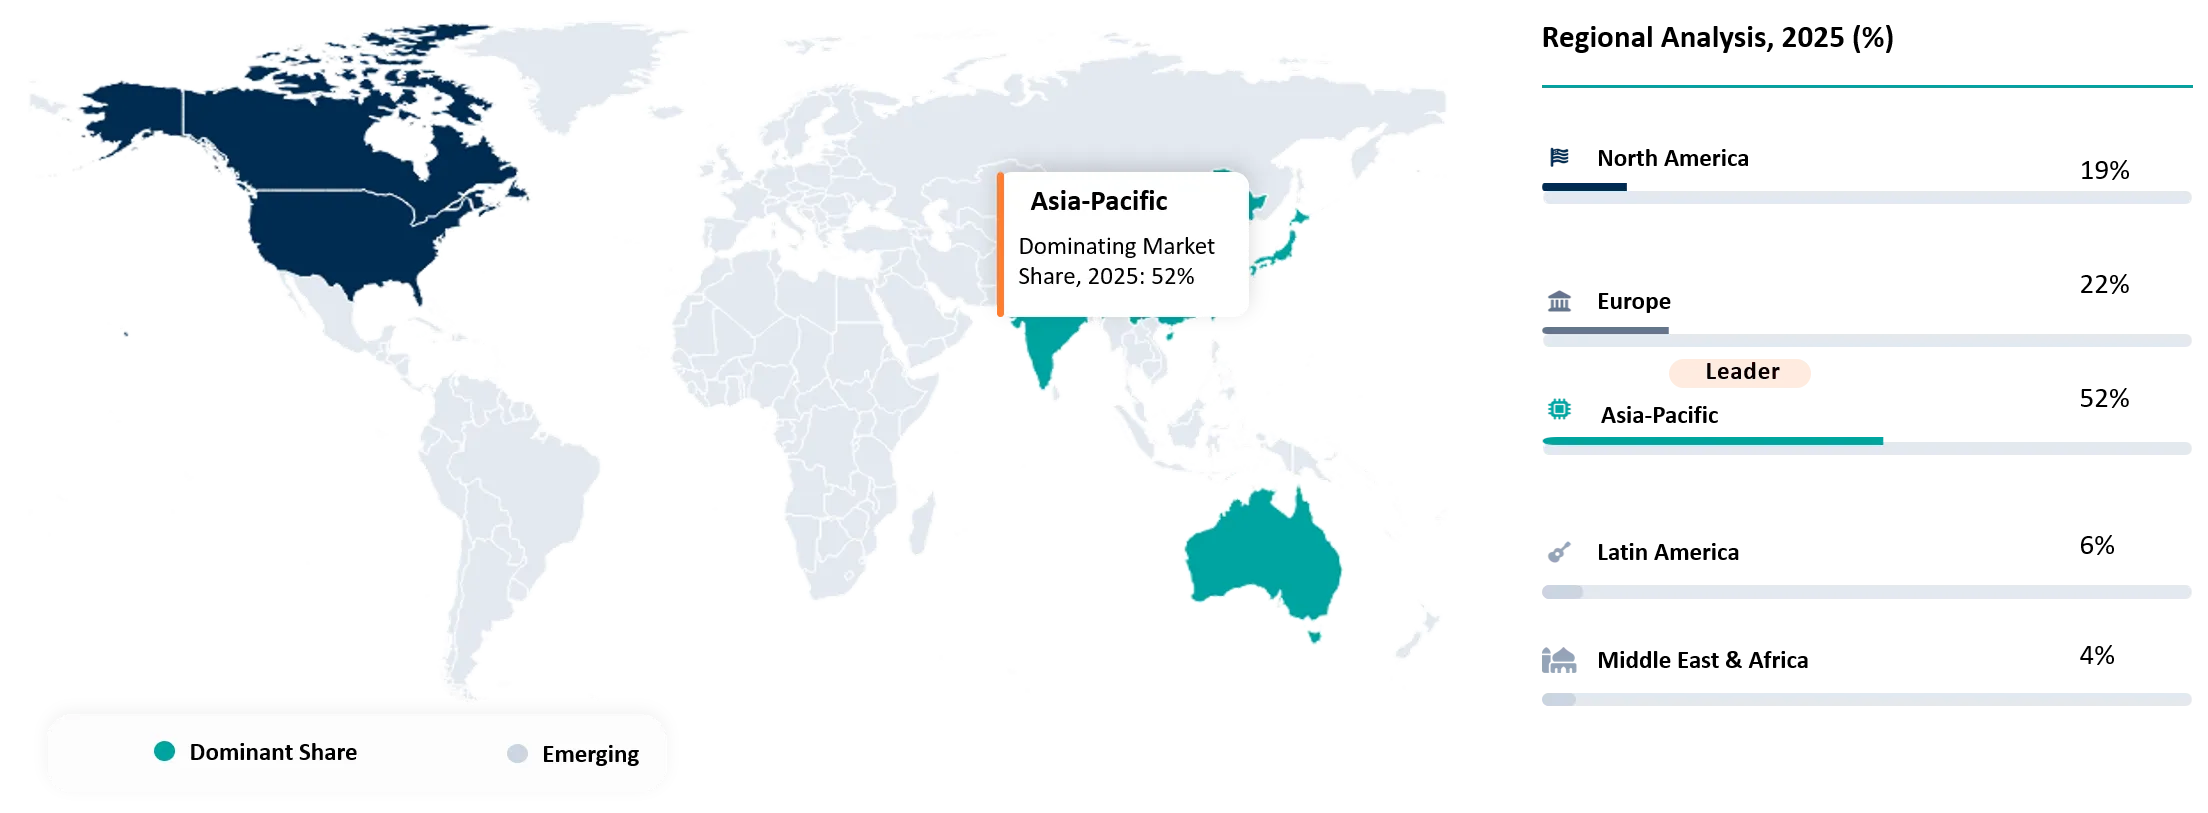
Asia-Pacific region dominated the automotive steel market, with a market share of 52% in 2025, driven by the presence of a huge automotive manufacturing industry in the region, growth in vehicle production, and increasing usage of advanced vehicle technology. The presence of several countries in the Asia-Pacific region that manufacture vehicles on a large scale, like China, Japan, and India, leads to the need for automotive steel for applications such as bodies, closures, chassis, crash management, suspension parts, and other safety-critical applications.
Vingroup’s expansion into steel manufacturing is expected to strengthen Vietnam’s domestic automotive-steel supply chain and reduce reliance on external steel sources. In October 2025, Vingroup JSC, a Vietnam-based conglomerate, established VinMetal Trading and Production JSC, a Vietnam-based steel manufacturing company, with Vingroup holding 98% of its charter capital. VinMetal plans to develop a high-tech steel complex in Vung Ang, Ha Tinh, Vietnam, with VND 10 trillion (USD 380 million) in initial investment capital and Phase 1 capacity of around 5 million tonnes per year.
China Automotive Steel Market Trends
China holds a dominant position in the Asia Pacific automotive steel market due to the presence of a large automobile manufacturing base, large steel manufacturing capacities, and quick growth in NEV manufacturing. China’s well-integrated auto & steel industry helps in providing automotive-grade steel in bulk for body structure, closure, chassis, crash management systems, and electric vehicle (EV) specific structural components. The ongoing investments in vehicle electrification have increased the importance of high-strength & lightweight steel grades.
China’s automotive steel sector is seeing greater consolidation and investment in advanced stainless-steel production capabilities. In July 2025, Tsingshan Group, a China-based stainless-steel producer, completed the acquisition of an 82.5% equity stake in POSCO Zhangjiagang Stainless Steel, a China-based stainless-steel manufacturing company owned by POSCO Holdings, a South Korea-based steel producer. The eight-month cross-border transaction strengthens Tsingshan’s position in high-end stainless-steel applications, including automotive exhaust systems, while providing access to POSCO’s international certifications, customer base, overseas sales network, and patented ferritic stainless-steel technologies.
Japan Automotive Steel Market Outlook
Japan is one of the major countries in the Asia Pacific automotive steel market, owing to its vehicle manufacturing infrastructure, steel manufacturing skills, and globally integrated automotive manufacturing companies. The country’s automotive industry has a sustained demand for high-quality automotive steel, which includes high-strength as well as advanced grades of steel used in car bodies, chassis, safety structures, closures, and lightweight components, among others.
Japan’s automotive steel industry is increasingly focusing on lightweighting while maintaining vehicle safety and structural performance. In October 2025, Nippon Steel Corporation, a Japan-based steel manufacturer, and Mazda Motor Corporation, a Japan-based automotive manufacturer, strengthened their collaboration under a new manufacturing model for the development of the all-new Mazda CX-5 crossover SUV. By integrating Nippon Steel’s NSafe-AutoConcept ECO³ next-generation automotive steel concept with Mazda’s model-based development technologies, the companies achieved a 10% reduction in total steel weight compared with the previous CX-5 while maintaining body rigidity and collision safety.
Automotive Manufacturing and Advanced Steel Capacity Strengthen North America’s Position
North America is one of the key regions in the automotive steel market, with a 19% market share in 2025 owing to the presence of an existing base of automobile manufacturing facilities in the region, along with the rising demand for light-weight and safe-structure vehicles and growing production of advanced steel grades in the domestic market. It is attributed to the existence of an integrated system between auto-makers and steelmakers in the U.S., Canada, and Mexico, which will enable the supply of AHSS, press-hardened steel, and coated automotive sheets for passenger cars and electric cars.
North America’s automotive steel supply chain is attracting major investments to expand localized, low-carbon steel production capacity. In September 2026, Hyundai Steel Company, a South Korea-based steel manufacturer and Hyundai Motor Group affiliate, began construction of a USD 5.8 billion electric-arc-furnace (EAF) integrated steel mill in Ascension Parish, Louisiana, U.S., operated by HYUNDAI-POSCO Louisiana Steel LLC (HPLS), a joint venture involving Hyundai Steel, POSCO (South Korea-based steel manufacturer), Hyundai Motor Company (South Korea-based automaker), and Kia Corporation (South Korea-based automaker).
U.S. Automotive Steel Market Trends
The U.S. holds a dominant position in the North American automotive steel market, supported by its large vehicle manufacturing base, established steelmaking industry, and increasing deployment of advanced high-strength and low-carbon automotive steels. The country has a well-developed ecosystem connecting automakers and steel producers, enabling domestic supply of AHSS, press-hardened steel, coated sheet, and other grades used in lightweight vehicle structures and safety-critical components.
The U.S. automotive steel industry is witnessing greater consolidation and investment in advanced flat-rolled steel production capacity. In June 2025, ArcelorMittal, a Luxembourg-based steel manufacturer, completed the acquisition of Nippon Steel Corporation’s, a Japan-based steel manufacturer, 50% equity stake in AM/NS Calvert in Alabama, U.S., making ArcelorMittal the sole owner of the facility, which was renamed ArcelorMittal Calvert. The facility has an annual flat-rolled steel capacity of approximately 5.3 million metric tons and produces advanced high-strength steels (AHSS), galvanized, galvannealed, aluminized, and cold-rolled steels, with more than USD 2 billion invested since 2014 to strengthen its capabilities for U.S. automotive and energy markets.
Automotive Steel Market Competitive Landscape
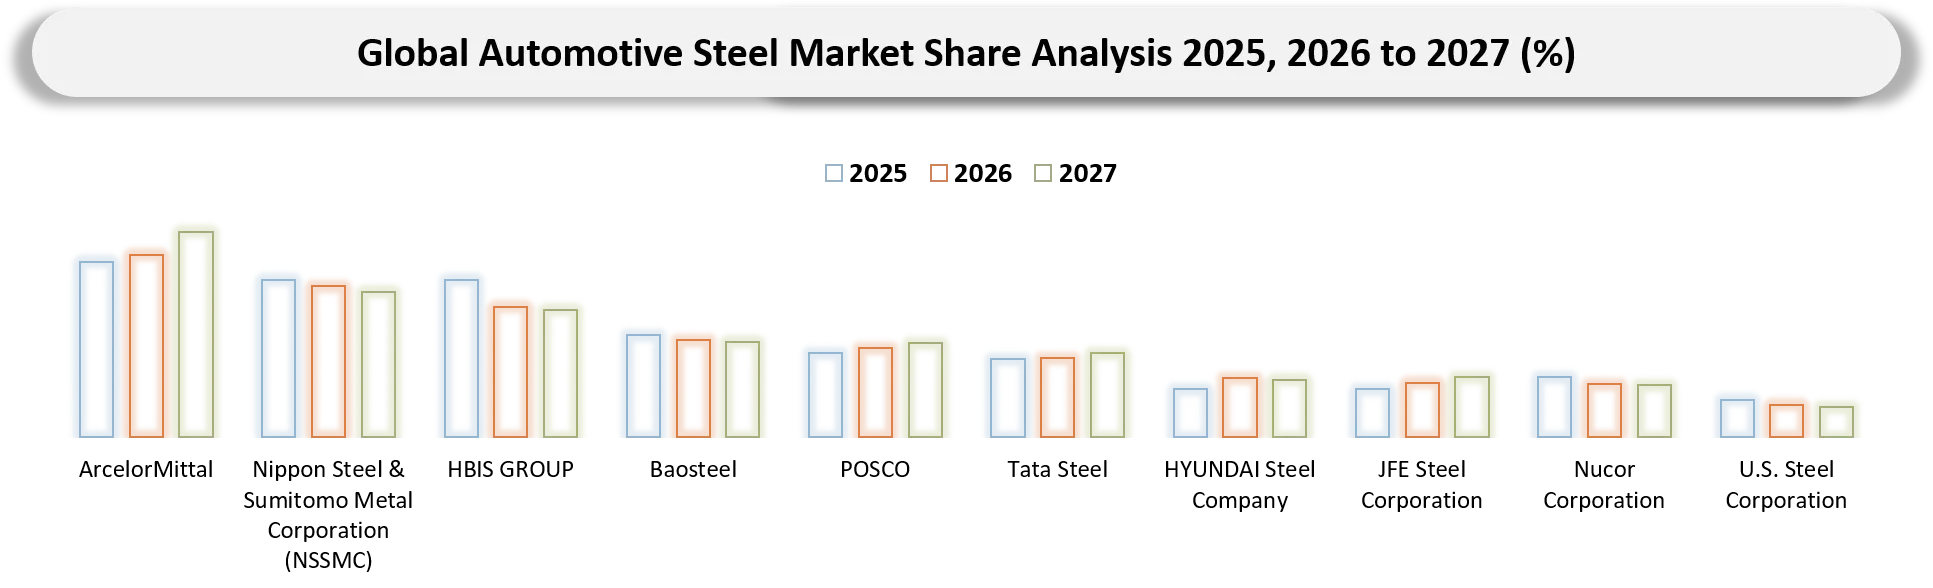
- The market is characterized by three key participant groups: global integrated steelmakers, advanced automotive-steel specialists, and regional steel producers with dedicated automotive-grade portfolios. ArcelorMittal, Nippon Steel & Sumitomo Metal Corporation (NSSMC), POSCO, Baosteel, JFE Steel Corporation, and HBIS Group compete through advanced high-strength steel (AHSS), ultra-high-strength steel (UHSS), galvanized and coated automotive steels, and lightweighting solutions; Tata Steel and Hyundai Steel Company focus on automotive-grade steel development and close integration with vehicle manufacturers; while Nucor Corporation and U.S. Steel Corporation strengthen the North American automotive supply base through flat-rolled and advanced steel products. It’s creating a technology- and supply-chain-driven landscape where advanced grades, product quality, geographic reach, customer collaboration, and low-carbon steel capabilities shape competitiveness.
- Key players include ArcelorMittal (Luxembourg), Nippon Steel & Sumitomo Metal Corporation (NSSMC) (Japan), HBIS Group (China), Baosteel (China), POSCO (South Korea), Tata Steel (India), Hyundai Steel Company (South Korea), JFE Steel Corporation (Japan), Nucor Corporation (U.S.), and U.S. Steel Corporation (U.S.).
Key Developments
- November 2025: Ansteel Group, a China-based steel manufacturer, launched ANautoS, its automotive steel solutions brand, integrating core resources from Anshan Iron & Steel, Pangang Group, Benxi Steel, Linggang Steel, and Ansteel United across five production bases.
- October 2025: Cleveland-Cliffs Inc., a U.S.-based steel manufacturer, completed a production trial with a major U.S. automotive manufacturer in which its exposed steel parts were stamped using the automaker’s existing aluminum-forming equipment with no defects and without modifications to the stamping line.
- July 2025: ArcelorMittal Nippon Steel India (AM/NS India), an India-based joint venture between ArcelorMittal, a Luxembourg-based steel manufacturer, and Nippon Steel Corporation, a Japan-based steel manufacturer, commissioned a new Continuous Galvanising Line (CGL) at its Hazira, Gujarat plant.
- September 2026: POSCO, a South Korea-based steel manufacturer, began construction of its new 8CGL (Continuous Galvanizing Line) at Gwangyang Steelworks in South Korea, investing KRW 480 billion (USD 350 million).
- February 2026: POSCO, a South Korea-based steel manufacturer, launched an “One Team” project structure for eight strategic steel products, integrating R&D, production and sales activities to accelerate commercialization.
- February 2026: Hyundai Steel, a South Korea-based steel manufacturer and Hyundai Motor Group affiliate, began mass production of low-carbon steel sheets using a hybrid process combining blast-furnace molten metal with electric arc furnace operations.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organizations procuring automotive steel increasingly select suppliers based on their ability to provide consistent-quality steel grades that meet requirements for strength, lightweighting, formability, corrosion resistance, weldability, and crash performance across vehicle body and structural applications.
- The procurement decision-making process is increasingly influenced by the transition toward electric vehicles, vehicle lightweighting, stricter safety requirements, and lower-carbon vehicle manufacturing, increasing demand for AHSS, UHSS, press-hardened, galvanized, and low-carbon automotive steel solutions.
- Buyers consider factors such as steel grade and mechanical properties, dimensional and surface quality, consistency, formability, coating performance, weldability, corrosion resistance, delivery reliability, and total material cost when selecting an automotive steel supplier.
Why Choose DataM?
- Advanced Steel Technologies: Explores developments in automotive steel, including AHSS, UHSS, press-hardened steel, high-formability grades, galvanized steel, and lightweight steel solutions, supporting vehicle safety, weight reduction, durability, and structural performance.
- Product Performance & Market Positioning: Evaluates automotive steel grades based on strength-to-weight ratio, formability, crash performance, weldability, corrosion resistance, surface quality, and cost efficiency, highlighting how leading steelmakers differentiate their products across passenger and commercial vehicles.
- Real-World Applications: Highlights the use of automotive steel in body-in-white structures, closures, chassis, suspension, bumpers, wheels, crash-management systems, and EV battery enclosures, demonstrating its role in lightweighting, occupant protection, durability, and vehicle efficiency.
- Market Updates & Industry Changes: Tracks developments such as automotive-grade steel capacity expansions, new AHSS and UHSS grades, low-carbon steel production, EAF investments, recycling initiatives, and regional automotive manufacturing developments across Asia-Pacific, North America, and Europe.
- Competitive Strategies: Analyzes how leading steelmakers expand through advanced-grade development, production-capacity expansion, automaker partnerships, localized supply chains, recycling, and low-carbon steel technologies to strengthen their position in automotive applications.
- Pricing & Market Access: Examines automotive steel pricing factors including steel grade, alloying requirements, coating, processing complexity, raw-material costs, energy costs, and production location, along with supply access through integrated steelmakers, service centers, and direct OEM relationships.
- Market Entry & Expansion: Identifies growth opportunities driven by EV production, vehicle lightweighting, stricter safety requirements, advanced steel adoption, low-carbon manufacturing, and circular steel supply chains, while outlining strategies such as regional capacity expansion, technology differentiation, OEM collaboration, and sustainable steel production.
Target Audience
- Automotive Steel Manufacturers
- Automotive OEMs
- Electric Vehicle Manufacturers
- Automotive Component Manufacturers
- Steel Service Centers & Distributors
- Steel Technology & Equipment Providers
- Recycling & Circular-Steel Companies



























































