


Terahertz Components and Systems Market Size and Overview
The global Terahertz Components and Systems market reached an estimated US$ 0.62 billion in 2025 and is expected to reach approximately US$ 2.52 billion by 2035, growing at a CAGR of about 15.05% during 2026-2035. Growth is being supported by expanding use of THz spectroscopy and imaging in material analysis and non-destructive testing, increasing semiconductor inspection requirements and rapidly accelerating sub-THz research for 6G communications.
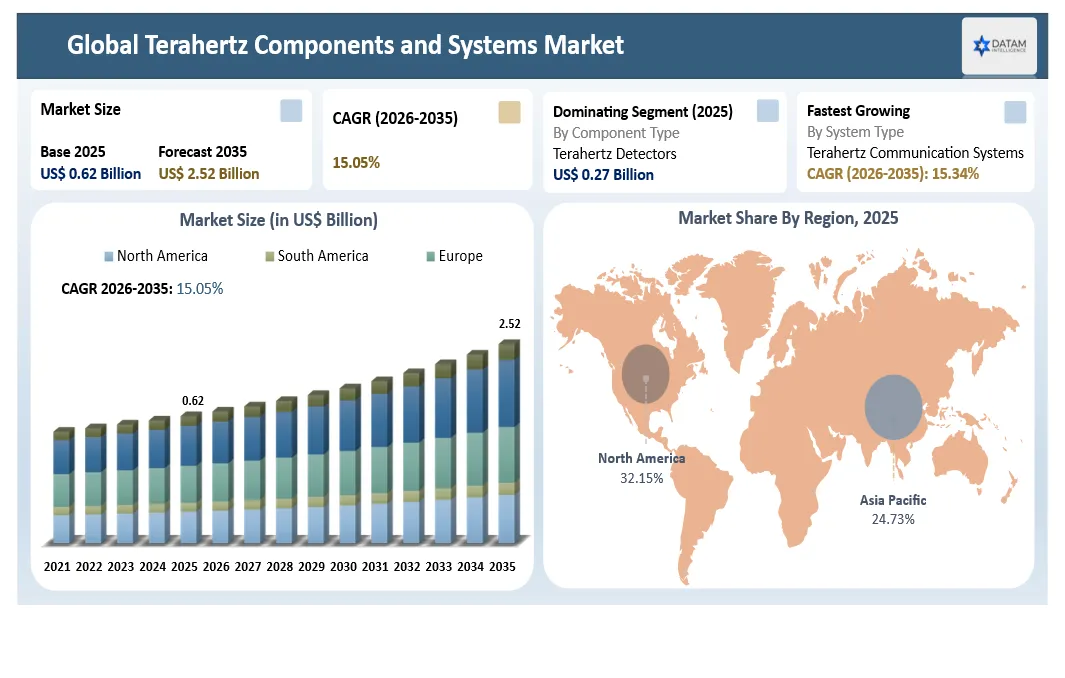
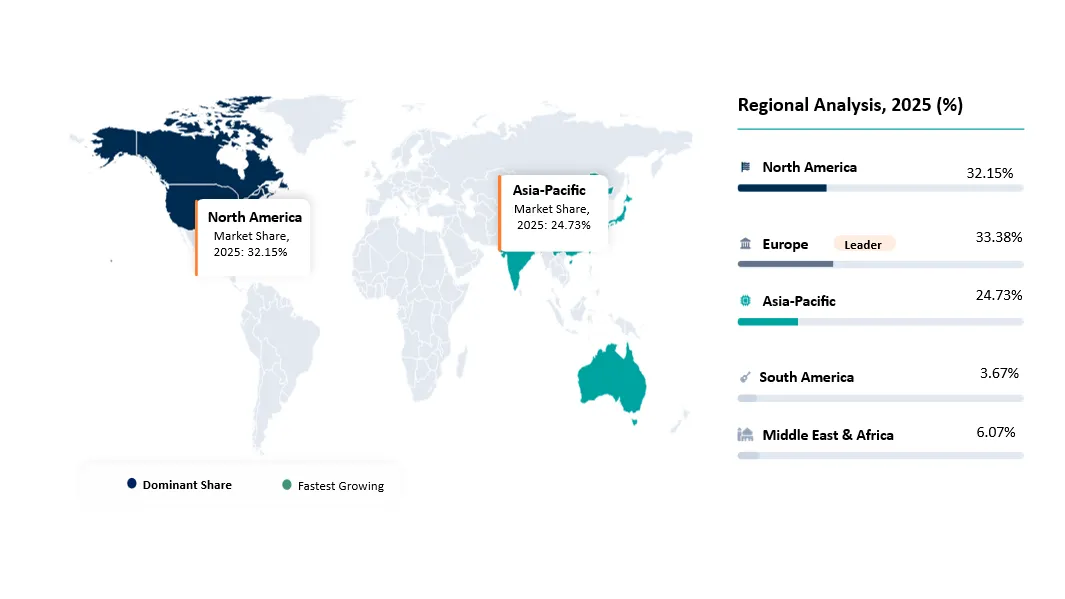
North America is the largest market because of advanced defense and security R&D, strong analytical-instrument demand, semiconductor research and a dense ecosystem of RF, microwave and photonics companies. Asia-Pacific is expected to grow fastest as China, Japan, South Korea and Taiwan increase investments in semiconductor metrology, high-frequency test, university research and 6G development.
The market is moving from laboratory-centered systems toward compact, more integrated solutions. Photonic generation remains important for broadband time-domain spectroscopy, while electronic and semiconductor approaches are improving output power, integration, cost and portability at lower THz and sub-THz frequencies. This convergence is expanding the addressable market from research laboratories into factory inspection, communications testing and embedded sensing.
Representative Commercial and Research Platforms
| Company / Platform | Primary Capability | THz Relevance | Strategic Importance |
| Keysight Technologies | High-frequency test, vector signal analysis and sub-THz measurement | Frequency extension and signal analysis for 6G, THz interconnect and research | Bridges RF test infrastructure with emerging THz communications. |
| TeraView | Terahertz time-domain spectroscopy and imaging | Material analysis, coating inspection, pharmaceuticals and NDT | Specialist commercial THz system provider with application depth. |
| Menlo Systems | THz time-domain spectroscopy and photonic sources | Broadband THz generation, spectroscopy and research systems | Strong position in photonic THz research instrumentation. |
| Hamamatsu Photonics | THz sensors, wave plates and terahertz spectrometer | Detection, optics and spectroscopy | Combines component manufacturing with complete photonic instrumentation. |
| Virginia Diodes | Frequency multipliers, extenders and sources | Millimeter-wave and THz test hardware | Critical enabling supplier for sub-THz and THz measurement chains. |
Terahertz Components and Systems Market Key Takeaways
- North America remains the largest market, supported by defense, telecommunications, advanced research and instrumentation demand.
- Asia-Pacific is expected to record the fastest growth as semiconductor inspection, 6G research and photonics manufacturing expand.
- Terahertz spectroscopy systems currently represent one of the largest system categories because they have mature research and industrial material-characterization use cases.
- The 0.1-0.3 THz and 0.3-1 THz ranges benefit most from 6G, radar, test and semiconductor device development because electronic generation and measurement are more commercially accessible.
- Non-destructive testing and semiconductor inspection are important near-term commercial applications because THz can reveal dielectric layers, defects and material characteristics without ionizing radiation.
- The main technical constraints remain limited source power, detector sensitivity, atmospheric attenuation, alignment complexity, cost and lack of standardized component interfaces.
- Integrated CMOS, SiGe and III-V solutions are expected to improve portability and cost while photonic systems retain advantages for broadband spectroscopy and high dynamic range.
- Future competition will increasingly depend on software, automation, AI-based image interpretation and application-specific workflows rather than hardware performance alone.
Terahertz Industry Trends and Strategic Insights
- 6G research is increasing demand for sub-THz channel emulation, signal generation, analysis, antennas and frequency extenders.
- AI data-center research is creating a new use case for THz interconnects and ultra-high-speed chip-to-chip or rack-scale links.
- Semiconductor metrology is becoming a stronger commercialization pathway as advanced packaging, HBM, chiplets and dielectric stack complexity increase.
- Industrial users are seeking real-time and inline inspection instead of laboratory-only scanning, favoring compact sources, fast detectors and automated interpretation.
- Security and defense applications continue to support research in passive imaging, concealed-object detection, stand-off sensing and high-resolution radar.
- The ecosystem remains highly collaborative, with specialist THz companies frequently partnering with larger RF-test, photonics and semiconductor-equipment suppliers.
Terahertz Components and Systems Market Scope
| Metrics | Details |
| 2025 Market Size | US$ 0.62 Billion |
| 2035 Projected Market Size | US$ 2.52 Billion |
| CAGR (2026-2035) | 15.05% |
| Largest Market | North America |
| Fastest Growing Market | Asia-Pacific |
| By Component Type | Sources, Detectors, Waveguides/Optics, Modulators/Frequency Converters, Antennas/Front-End Modules and Others |
| By System Type | Spectroscopy, Imaging, Radar & Sensing and Communication Systems |
| By Technology | Photonic, Electronic, Quantum Cascade Laser, CMOS/SiGe/III-V Integrated and Others |
| By Frequency Range | 0.1-0.3 THz, 0.3-1 THz, 1-3 THz and Above 3 THz |
| By Application | NDT, Material Characterization, Security, Semiconductor Inspection, Biomedical, 6G Communication Research, Process Monitoring and Others |
| By End Use Industry | Telecom, Semiconductor & Electronics, Aerospace & Defense, Healthcare & Pharmaceuticals, Industrial, Research & Academia, Security and Others |
| By Sales Channel | Direct, Distributors/VARs, OEM Integration and Research Procurement |
| By Portability | Benchtop/Laboratory, Portable/Field and Embedded/On-Chip |
| Report Insights Covered | Market Size, Share, Growth, Technology, Ecosystem, Competitive Landscape and Company Profiles |
Why does this report matter in 2026?
The year 2026 is a transition point because sub-THz and THz technologies are moving closer to systems-level engineering. Keysight announced in March 2026 that AttoTude adopted enhanced vector signal analysis capabilities to accelerate characterization of THz interconnect technology for AI and hyperscale data centers. In July 2026, Keysight and IEMN reported a sub-THz dual-polarization non-line-of-sight communication demonstration using a reflective intelligent surface, illustrating how THz research is becoming increasingly application-focused.
At the same time, AI-driven semiconductor investment is increasing demand for advanced photonics and inspection. Hamamatsu reported strong industrial demand in the first half of FY2026, including semiconductor manufacturing, failure analysis and non-destructive testing. These trends matter because the commercial opportunity for THz is no longer tied only to academic spectroscopy. The addressable market is widening into electronics validation, industrial inspection, communications and embedded sensing.
Terahertz Components and Systems Market White Space & Investment Opportunities
- Compact room-temperature THz sources and detectors that reduce system size and cooling requirements.
- Integrated on-chip THz transceivers, mixers, antennas and waveguides for 6G and high-speed interconnect research.
- Inline semiconductor and advanced-packaging inspection using fast scanning and AI-based defect interpretation.
- Portable non-destructive testing for composites, coatings, foams, batteries, aerospace structures and cultural heritage.
- Software-defined THz instruments with automated calibration, spectral libraries and application-specific analytics.
- High-volume optical and electronic packaging that lowers alignment cost and improves repeatability.
Terahertz Future Market Transformation
The market is expected to shift from specialist laboratory platforms toward a layered ecosystem of components, integrated modules and application-specific systems. Broadband photonic spectroscopy will continue to support research and materials analysis, while compact electronic and semiconductor platforms expand in communication, radar and embedded sensing. Higher integration will reduce alignment burden, improve repeatability and allow OEMs to incorporate THz capability into semiconductor, pharmaceutical and security equipment.
Software will become increasingly important. Automated waveform processing, AI-assisted image reconstruction, spectral fingerprinting and digital-twin models can turn THz measurements into pass/fail decisions rather than raw laboratory data. This is critical for factory adoption because industrial users buy throughput, yield and defect reduction rather than frequency performance alone.
Terahertz Components and Systems Market Buyer Decision-Making Criteria
Buyers evaluate usable frequency range, dynamic range, source power, detector sensitivity, acquisition speed, spectral resolution, imaging resolution, calibration stability, scan area, portability, software integration and total system cost. Research users prioritize flexibility and bandwidth, while industrial users prioritize repeatability, uptime, automated analysis and integration with production lines.
For communication and semiconductor applications, buyers also consider phase noise, modulation bandwidth, vector accuracy, frequency-extension compatibility, probe and waveguide interfaces and support for automation. Suppliers with strong application engineering, calibration services and reference workflows can reduce adoption risk and command higher value.
Terahertz Components and Systems Market Economic & Investment Analysis
Commercial economics are shaped by low production volumes, specialist components and relatively high engineering content. A meaningful portion of system value is therefore linked to intellectual property, calibration, integration and software. Scale economics improve when components are reused across multiple applications, particularly in semiconductor test, high-frequency communications and general spectroscopy.
Investment is increasingly attracted to platforms that can cross application boundaries. Frequency-extender and detector suppliers can serve telecommunications, semiconductor and defense customers, while photonic THz systems can address materials, pharmaceutical and academic markets. The strongest business models combine recurring service, software or accessory revenue with high-value hardware.
Terahertz Investment Trends in the Market
- Capital is moving toward semiconductor-integrated THz sources, detectors and transceivers that improve manufacturability.
- 6G research programs are funding sub-THz test systems, channel characterization, antennas and reflective intelligent surface experiments.
- Semiconductor and AI infrastructure investment is strengthening demand for high-frequency metrology and advanced inspection.
- Defense and security programs continue to support passive imaging, radar and stand-off sensing development.
- Specialist vendors are partnering with larger test-and-measurement and photonics companies to gain distribution, calibration and application reach.
Strategic Indicators For the Terahertz Components and Systems Market
High Regulation Impact
Export controls, defense-use restrictions, radio-spectrum policies, laser safety rules and medical-device requirements can affect product design, shipment and application approval. Communication applications also depend on future spectrum allocation and standards.
High Investment Activity
Public and private R&D investment remains high because THz sits at the intersection of 6G, semiconductors, photonics, imaging and quantum technologies. Funding is concentrated in platform technologies that can support multiple applications.
Supply Chain Disruption
Specialty semiconductors, precision optics, ultrafast lasers, frequency multipliers and detector materials can have long lead times. Geopolitical restrictions on advanced RF and semiconductor technology increase sourcing complexity.
Pricing Volatility
System prices vary widely by bandwidth, power, detector technology, scan configuration and software. Research systems can command high prices because of customization and low volumes, while integrated electronic approaches are expected to lower cost over time.
Procurement Pressure
Industrial buyers increasingly require measurable throughput, reproducibility, service support and integration capability. Academic and government procurement remains specification-driven and can involve long tender cycles.
New Technology Adoption
CMOS, SiGe, III-V devices, photomixing, quantum cascade lasers, plasmonic structures and advanced metamaterials are widening the range of source and detector architectures.
Regional Expansion Opportunity
Japan, South Korea, Taiwan and China offer strong growth potential because of semiconductor manufacturing and 6G research. Europe remains important in photonics and spectroscopy, while North America leads in test, defense and startup activity.
Government Policy Support
National 6G programs, semiconductor incentives, defense research and advanced-manufacturing initiatives indirectly support THz commercialization by funding test infrastructure and device development.
Pricing Intelligence
Benchtop spectroscopy systems retain premium pricing, frequency extenders and analyzers are priced based on bandwidth and metrology performance, while future integrated modules should see faster cost declines as semiconductor volumes increase.
Disruption Analysis of Terahertz Components and Systems Market
The largest disruption is the migration from discrete optical laboratory systems toward integrated electronic and photonic architectures. As source power and detector performance improve, functions that previously required large optical tables can move into compact modules. This expands addressable applications but also shifts competitive advantage toward semiconductor design, packaging and software.
A second disruption is the convergence of THz with AI. Higher-speed acquisition generates large spectral and imaging datasets that can be interpreted with machine learning. This can improve defect classification, material identification and signal processing, making THz more useful in industrial environments where expert interpretation is scarce.
Terahertz Components and Systems Market BCG Matrix: Company Evaluation
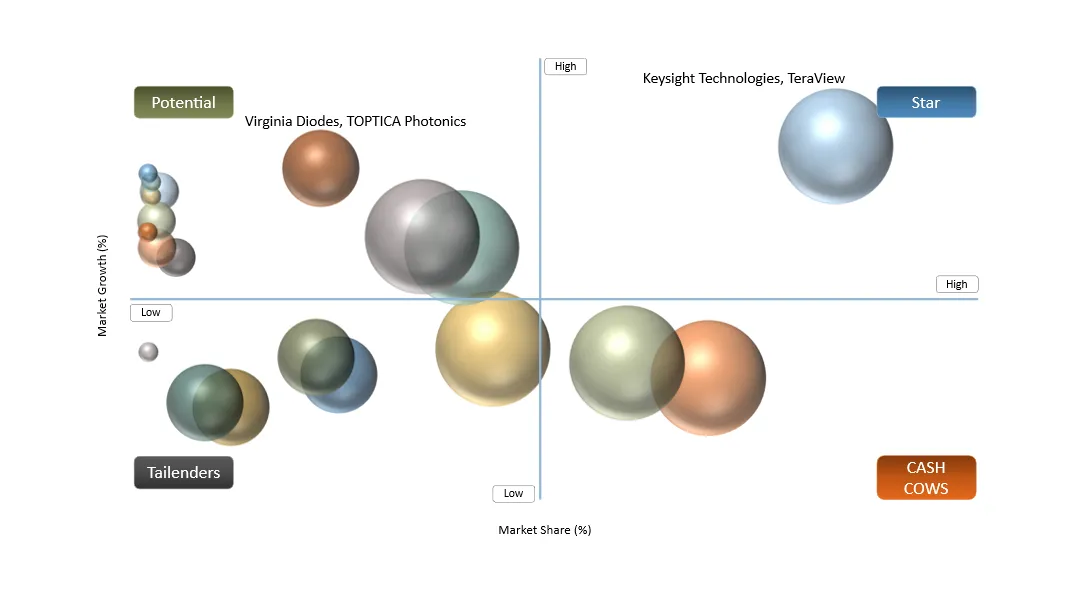
STAR
Keysight Technologies, TeraView, Menlo Systems and Hamamatsu Photonics are positioned as strong strategic participants because they combine meaningful technology depth with established commercialization channels. Keysight benefits from high-frequency test infrastructure and 6G relationships, TeraView and Menlo Systems offer dedicated THz platforms and Hamamatsu spans sensors, optics and spectroscopy.
POTENTIAL
Virginia Diodes, TOPTICA Photonics, TeraSense, Bakman Technologies and semiconductor-focused entrants represent high-potential participants. Their market position can strengthen as integrated sources, detectors, extenders and application-specific modules move from research into industrial and communications deployment.
Terahertz Components and Systems Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact | Demand Concentration | Impacted Use Case | Strategic Impact |
| 6G and sub-THz research | High | Telecom, test and academia | Channel sounding, signal generation, antennas, transceivers | Expands demand for extenders, analyzers and integrated front ends. |
Semiconductor inspection and advanced packaging | High | Semiconductor fabs and equipment suppliers | Dielectric inspection, failure analysis, package characterization | Creates high-value industrial adoption with strong ROI. |
Non-destructive testing and quality control | Medium-High | Aerospace, plastics, batteries, coatings | Layer inspection, void detection, thickness and moisture | Moves THz from laboratories into production and field inspection. |
Improving compact sources and detectors | Medium-High | Broad market | Portable and embedded sensing | Reduces system cost and integration complexity. |
Driver: Accelerating 6G and Sub-THz Communication Research
Research into 6G is expanding the commercial relevance of frequencies above conventional millimeter-wave bands. Sub-THz links can offer extremely large bandwidths, but they require new channel models, antennas, frequency extenders, signal analyzers, semiconductor devices and propagation-control techniques. This creates demand across the full THz ecosystem before mass-market 6G commercialization occurs.
Restraint Impact Analysis
| Restraint | Drag on Market Growth | Primary Impact Area | Impacted Use Case | Strategic Impact |
| High system and component cost | High | Commercial adoption | Industrial and healthcare systems | Slows deployment outside high-value applications. |
| Limited source power and detector sensitivity | High | Performance | Longer-range imaging and communications | Restricts range, speed and signal-to-noise ratio. |
| Atmospheric absorption and path loss | Medium-High | Wireless systems | Outdoor links and stand-off sensing | Requires shorter links, beam control and careful frequency selection. |
| Lack of standards and integration interfaces | Medium | OEM adoption | Embedded systems and production tools | Increases engineering time and vendor dependence. |
Restraint: Cost, Power and Integration Constraints
THz systems remain expensive relative to mature optical and RF instruments because many sources, detectors, optics and frequency-conversion components are produced in low volumes. Performance also varies strongly across frequency. Improving integration, packaging and room-temperature operation is therefore essential for broader commercial adoption.
Terahertz Components and Systems Market Segment Analysis
The global Terahertz Components and Systems market is segmented based on Component Type, System Type, Technology, Frequency Range, Application, End Use Industry, Sales Channel, Portability and region.
By Component Type
Terahertz Sources Will Remain a Critical High-Value Component Segment
Sources are fundamental because available power and tunability determine useful range, scan speed and signal-to-noise performance. Photoconductive antennas, multiplier chains, photomixers, quantum cascade lasers and semiconductor oscillators address different frequency and power requirements. Detectors grow strongly alongside sources as faster imaging and room-temperature operation improve.
By System Type
Terahertz Spectroscopy Systems Will Retain Leadership While Communication Systems Grow Fastest
Spectroscopy has the most established commercial base in materials, pharmaceuticals and research. Communication systems grow from a smaller base as 6G, data-center interconnect and high-frequency device research expand. Imaging and radar systems also gain traction in NDT, security and defense.
By Technology
Electronic and Integrated Semiconductor Technologies Will Gain Share
Photonic systems remain important for broadband time-domain spectroscopy, but electronic THz generation using multiplier chains, SiGe, CMOS and III-V devices is improving rapidly at sub-THz frequencies. Integrated semiconductor approaches can lower cost, size and alignment complexity and therefore have strong long-term growth potential.
By Frequency Range
0.1-0.3 THz Will Maintain the Largest Near-Term Commercial Base
Lower THz and sub-THz frequencies benefit from more mature microwave electronics, lower atmospheric losses and growing 6G interest. The 0.3-1 THz range is expected to grow quickly as device performance improves. Above 1 THz remains important for spectroscopy and scientific applications where molecular signatures and broadband measurements are valuable.
By Application
Non-Destructive Testing and Semiconductor Inspection Will Drive Commercial Adoption
NDT offers a practical value proposition because THz can inspect dielectric materials, coatings and composite structures. Semiconductor inspection is increasingly attractive as packaging structures become more complex. Communications research is the fastest-growing application from a smaller base.
By End Use Industry
Telecommunications and Semiconductors & Electronics Will Expand Fastest
Research and academia remain major users, but telecom and semiconductor industries are becoming increasingly important sources of demand. Aerospace and defense continue to support high-performance sensing and radar, while healthcare and pharmaceuticals use THz for spectroscopy, imaging research and quality control.
By Sales Channel
Direct Sales Will Dominate High-Value Systems
Complex THz platforms typically require application engineering, calibration and installation, making direct sales important. Distributors support regional reach for components, while OEM integration becomes more important as THz is embedded into industrial and semiconductor equipment.
By Portability
Portable and Embedded Systems Will Record the Fastest Growth
Benchtop systems dominate today because of optical alignment and laboratory use. Portable platforms expand field inspection, while embedded or on-chip devices offer the strongest long-term opportunity if semiconductor integration reaches sufficient power, sensitivity and manufacturability.
Terahertz Components and Systems Market Geographical Penetration
U.S. Terahertz Components and Systems Market Landscape
The U.S. leads commercial demand through defense research, semiconductor engineering, university laboratories, telecom development and a strong test-and-measurement ecosystem. Keysight, Virginia Diodes and several specialist technology companies support high-frequency measurement and component development. Federal research programs and AI infrastructure investment reinforce demand for sub-THz characterization and advanced sensing.
Germany Terahertz Components and Systems Market Outlook
Germany has a strong photonics, industrial automation and scientific-instrument base. Demand is supported by research institutes, automotive and aerospace NDT, semiconductor development and university photonics laboratories. Domestic strengths in laser systems and precision instrumentation support a high-value ecosystem rather than mass-volume production.
Japan Terahertz Components and Systems Market Trends
Japan is an important market through Hamamatsu Photonics, Advantest and a large semiconductor and electronics research base. Investment in advanced packaging, photonics, communications and industrial metrology supports demand for detectors, optical components, spectroscopy and high-frequency test systems.
China Terahertz Components and Systems Market Outlook
China is expanding rapidly through 6G research, semiconductor localization, university programs and industrial sensing. The market benefits from a large electronics manufacturing base, although access to certain advanced RF and semiconductor technologies can be affected by export controls. Domestic component development is therefore strategically important.
South Korea and Taiwan Market Outlook
South Korea and Taiwan are important because of advanced semiconductor manufacturing, memory, foundry and packaging ecosystems. THz inspection and sub-THz test demand can grow alongside HBM, chiplet and advanced packaging investment. Telecom research also supports demand for high-frequency measurement infrastructure.
Middle East and Africa Market Outlook
Demand remains smaller but includes university research, defense and security, oil and gas inspection and high-end scientific infrastructure. Gulf countries provide the strongest near-term opportunities through research investment and technology diversification programs.
Terahertz Components and Systems Market Competitive Landscape
- The market is fragmented between specialist THz vendors and large photonics, analytical-instrument and RF-test companies.
- Specialist firms such as TeraView, Menlo Systems, Virginia Diodes and TeraSense compete through application depth, flexibility and component specialization.
- Large public companies such as Keysight, Bruker, Hamamatsu and Teledyne benefit from global sales channels, calibration infrastructure, R&D budgets and adjacent technology portfolios.
- Competition is shifting toward integrated solutions that combine hardware, software, signal processing and application-specific workflows.
- Partnerships are common because complete THz systems require capabilities spanning RF electronics, photonics, optics, semiconductors, packaging and software.
Public Company Q1-Q2 2026 Performance Comparison
| Public Company | Q1-Q2 2026 Performance Indicator | Terahertz Market Exposure | Factors Supporting Growth |
| Keysight Technologies, Inc. | Fiscal Q2 2026 revenue reached US$1.72 billion versus US$1.31 billion a year earlier; orders exceeded US$2 billion. Communications Solutions revenue increased 35% and Electronic Industrial Solutions increased 24%. | Sub-THz test, vector signal analysis, frequency extension, channel characterization and THz interconnect development. | 6G R&D, aerospace/defense demand, semiconductor test, AI data-center interconnect research and strong commercial communications investment. |
| Teledyne Technologies Incorporated | Q2 2026 net sales were US$1.6625 billion, up 9.8% year over year; the company reported record quarterly orders, sales and operating profit. | Advanced imaging, detectors, instrumentation and sensing technologies relevant to THz-adjacent and high-frequency systems. | Infrared and advanced detector demand, aerospace and defense systems, unmanned platforms, scientific instrumentation and acquisitions. |
| Hamamatsu Photonics K.K. | FY2026 first-half sales were ¥112.4 billion, up 5.4% year over year; industrial sales were ¥39.2 billion, up 4.5%, while measuring sales increased 22.1%. | THz sensors, terahertz wave plates, terahertz spectrometers, photonic sources and detectors. | Generative-AI-driven semiconductor investment, inspection and NDT demand, photonics integration and broader detector/laser portfolio. |
| Bruker Corporation | Q1 2026 revenue was US$823.4 million, up 2.7% reported; Bruker Scientific Instruments bookings grew high-single digits organically and book-to-bill remained above 1.0x. | Spectroscopy, material characterization and advanced analytical instrumentation adjacent to THz research workflows. | Industrial research tools, semiconductor metrology, security detection, post-genomic science and recovery in scientific-instrument bookings. |
| Advantest Corporation | FY2026 first-quarter results were released on July 29, 2026 and the company revised its fiscal-year earnings forecast upward; FY2026 full-year net sales guidance is ¥1.42 trillion. | High-frequency semiconductor test, device characterization, interconnect testing and metrology that overlap with sub-THz device development. | AI/HPC semiconductor demand, advanced packaging, silicon photonics test, memory and SoC complexity and expanding design-to-test automation. |
Source note: company investor-relations releases from Keysight (Q2 FY2026), Teledyne (Q2 2026), Hamamatsu Photonics (FY2026 first half), Bruker (Q1 2026) and Advantest (FY2026 first-quarter reporting and full-year guidance). Terahertz-specific revenue is not separately disclosed by these companies; exposure descriptions are based on product portfolios and adjacent high-frequency/photonics activities.
Market Ecosystem Analysis
| Value Chain Sector | Representative Companies | Role in the Ecosystem | Growth Relevance |
| Semiconductor & Material Platforms | GlobalFoundries, TSMC, Tower Semiconductor, imec, Fraunhofer institutes | Provide CMOS, SiGe, III-V and advanced research process platforms for THz ICs and devices. | Integration and manufacturing scale are essential for low-cost on-chip THz. |
| THz Sources & Frequency Extenders | Virginia Diodes, Keysight, Menlo Systems, TOPTICA Photonics, Bakman Technologies | Generate CW, pulsed or frequency-multiplied THz signals. | Source power and tunability remain core bottlenecks and value drivers. |
| Detectors & Optical Components | Hamamatsu Photonics, TeraSense, Gentec-EO, Thorlabs | Provide THz sensors, optics, wave plates, detectors and supporting photonic components. | Improved sensitivity and room-temperature operation expand commercial use. |
| Spectroscopy & Imaging Systems | TeraView, Menlo Systems, Hamamatsu Photonics, TeraSense | Deliver complete THz-TDS, spectroscopy and imaging platforms. | Commercial anchor for research, materials, pharmaceuticals and NDT. |
| RF / Microwave Test & Measurement | Keysight, Anritsu, Rohde & Schwarz, Advantest | Provide signal generation, analysis, network analysis, semiconductor test and high-frequency validation. | 6G and sub-THz communications create a large adjacent growth pool. |
| Analytical Instrumentation | Bruker, Thermo Fisher Scientific, HORIBA | Serve spectroscopy and materials-analysis customers with complementary analytical platforms. | Cross-selling and workflow integration can accelerate adoption. |
| Semiconductor & Electronics Users | Intel, Samsung Electronics, SK hynix, TSMC, Micron, NVIDIA ecosystem | Develop and manufacture high-speed devices, packages and AI hardware. | Advanced packaging and interconnect complexity create new inspection and test needs. |
| Telecom & 6G Research | Ericsson, Nokia, Samsung, NTT DOCOMO, Keysight ecosystem, universities | Develop channels, antennas, waveforms and radio architectures for sub-THz networks. | Primary driver for communications-system growth. |
| Industrial NDT & Security Integrators | Evident, Waygate Technologies, defense primes, airport-security integrators | Integrate sensing into inspection and screening workflows. | Turns THz from laboratory measurement into operational systems. |
| Research & Standards Bodies | IEEE, 3GPP ecosystem, NIST, ETSI, national metrology institutes | Develop standards, metrology, spectrum frameworks and reference methods. | Standardization lowers adoption risk and supports interoperability. |
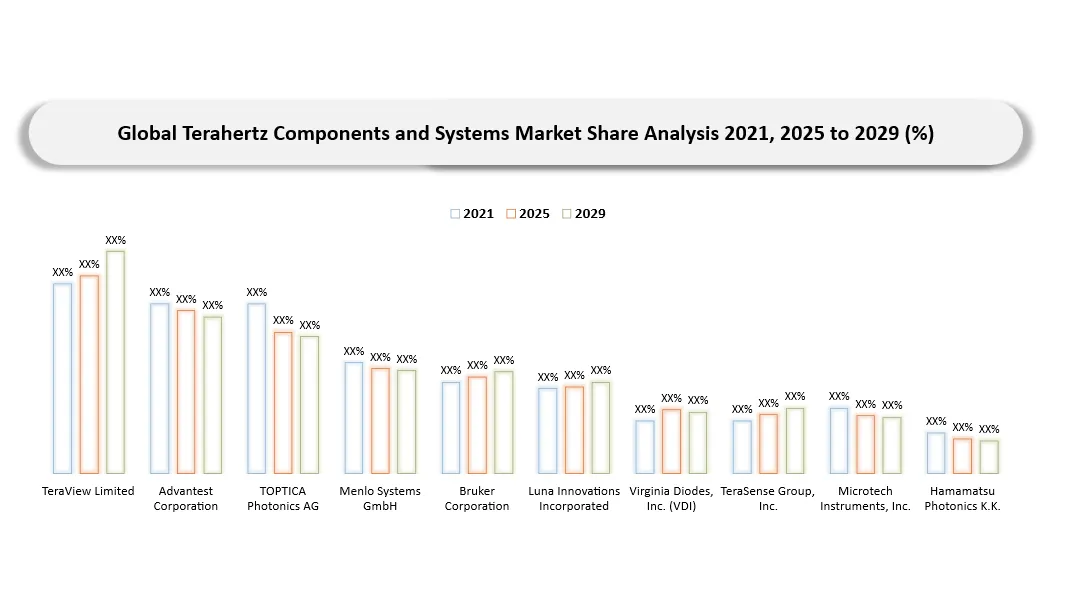
Key Companies of the Terahertz Components and Systems Market
- Keysight Technologies, Inc.
- Advantest Corporation
- Bruker Corporation
- Hamamatsu Photonics K.K.
- TeraView Limited
- Menlo Systems GmbH
- TOPTICA Photonics AG
- Virginia Diodes, Inc.
- TeraSense Group, Inc.
- Thorlabs, Inc.
- Teledyne Technologies Incorporated
- Anritsu Corporation
- Microtech Instruments, Inc.
- Bakman Technologies LLC
- Luna Innovations Incorporated
Company Profiles
Keysight Technologies, Inc.
Keysight is a leading electronic design and test company with strong relevance to sub-THz and THz communications. Its portfolio includes signal analyzers, vector signal analysis software, network analysis and frequency-extension solutions. The company is positioned to benefit from 6G channel research, semiconductor characterization and THz interconnect development. Its 2026 collaborations with AttoTude and IEMN demonstrate an active role in translating THz research into communications and data-center applications.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Advantest Corporation
Advantest is a major semiconductor test-equipment company. Its relevance to the THz market comes from high-frequency device test, advanced packaging, silicon photonics and design-to-test infrastructure. As THz transceivers and front ends move into integrated semiconductor technologies, automated test capability becomes critical for commercialization and manufacturing scale.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Bruker Corporation
Bruker is a scientific instrumentation company with broad spectroscopy, materials research and semiconductor metrology capabilities. While it does not separately disclose a THz business, its customer base and analytical workflows overlap strongly with THz spectroscopy and materials characterization. Its scientific-instrument bookings and semiconductor metrology exposure provide useful commercial context for the market.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Hamamatsu Photonics K.K.
Hamamatsu Photonics manufactures photodetectors, light sources, lasers, optical components, THz sensors, terahertz wave plates and a terahertz spectrometer. This breadth gives it direct participation in both component and system layers of the THz value chain. Strong 2026 industrial demand tied to semiconductors and NDT reinforces its strategic position.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
TeraView Limited
TeraView is a specialist terahertz company focused on time-domain spectroscopy and imaging systems. Its solutions are used for coating and layer measurement, materials analysis, pharmaceuticals, semiconductor applications and NDT. The company benefits from deep application expertise and an installed base built around practical commercial use cases.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Menlo Systems GmbH
Menlo Systems is a photonics instrumentation company known for frequency-comb, ultrafast laser and terahertz time-domain solutions. Its THz platforms are used in research, materials analysis and spectroscopy. The company is well positioned in high-performance photonic systems where broadband bandwidth and precision are more important than low cost.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
TOPTICA Photonics AG
TOPTICA develops laser and photonics systems used in scientific and industrial research. Its technology is relevant to photomixing and THz generation architectures. The company participates in the broader ecosystem through precision laser sources, frequency control and application partnerships.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Virginia Diodes, Inc.
Virginia Diodes is a key specialist supplier of millimeter-wave and terahertz components, frequency multipliers, sources, receivers and frequency extenders. Its products are widely used with high-end test equipment for spectroscopy, communications and device characterization. The company is strategically important because it addresses one of the hardest parts of THz systems: efficient frequency generation and extension.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
TeraSense Group, Inc.
TeraSense develops terahertz imaging and detector technologies aimed at industrial and scientific applications. Its compact detector arrays and imaging solutions support NDT, security, process monitoring and material inspection. The company represents the shift toward simpler and more application-specific THz imaging platforms.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Thorlabs, Inc.
Thorlabs supplies a broad range of photonics components, optomechanics, lasers, detectors and instrumentation used in THz research laboratories. Its value is primarily as an ecosystem enabler rather than a dedicated full-system THz vendor. Broad distribution and catalog depth reduce procurement complexity for research users.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Teledyne Technologies Incorporated
Teledyne operates in digital imaging, instrumentation, aerospace and defense electronics. Its detector, imaging and scientific-instrument capabilities are relevant to THz-adjacent sensing and advanced imaging markets. Record Q2 2026 orders and strong digital-imaging growth provide a favorable backdrop for high-performance sensing technologies.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Anritsu Corporation
Anritsu is a global test-and-measurement supplier with strong exposure to wireless communications, spectrum analysis, network analysis and high-frequency components. Its expertise is relevant to sub-THz communications research and future 6G measurement. The company can benefit as standards work expands from millimeter-wave toward higher frequencies.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Microtech Instruments, Inc.
Microtech Instruments develops terahertz and infrared spectroscopy components and systems for research and analytical applications. Its niche positioning supports customized deployments where users need flexible sources, detectors and system integration rather than standardized high-volume instruments.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Bakman Technologies LLC
Bakman Technologies is a specialist provider of terahertz spectroscopy and related scientific instrumentation. The company participates in research-intensive applications and supports adoption through compact system design and application support. Smaller specialists such as Bakman remain important because they can iterate rapidly around emerging use cases.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Luna Innovations Incorporated
Luna Innovations has historically participated in advanced photonics, optical test and sensing technologies. Its relevance to THz is primarily through adjacent photonic instrumentation, fiber-based systems and R&D capabilities. Competitive significance depends on continued portfolio focus and participation in high-frequency optical sensing markets.
Competitive priorities include product performance, system integration, application-specific validation, calibration support, channel reach and the ability to lower total cost of ownership for research and industrial customers.
Terahertz Components and Systems Market Major Pain Points
- High component and system costs compared with mature optical and microwave technologies.
- Limited source power and detector sensitivity across parts of the THz spectrum.
- Atmospheric absorption and severe free-space path loss for communication applications.
- Alignment complexity and calibration requirements in photonic systems.
- Lack of standardized interfaces and limited interoperability between specialist components.
- Slow procurement cycles in academic, defense and government research markets.
- Difficulty converting laboratory demonstrations into high-throughput industrial workflows.
- Limited installed base of field technicians and application specialists for THz systems.
Terahertz Components and Systems Market Recent Developments
- July 2026: Keysight and IEMN, together with Virginia Diodes and Micro Harmonics, reported a dual-polarization non-line-of-sight sub-THz communication link using a reflective intelligent surface for 6G research.
- June 2026: Advantest partnered with OpenLight to develop silicon photonics test solutions for high-volume manufacturing, reinforcing test infrastructure relevant to high-speed photonic and future THz-integrated devices.
- June 2026: Hamamatsu Photonics announced a memorandum of understanding on development and industrialization of advanced photonic systems for quantum computing, highlighting continued investment in precision photonics platforms.
- March 2026: Keysight announced that AttoTude adopted enhanced 89600 VSA capabilities to accelerate development of THz interconnect technology for AI and hyperscale data centers, with operation up to 1 THz.
- February 2026: Teledyne highlighted continued expansion of vertically integrated advanced imaging and detector capabilities across defense, professional and autonomous systems.
Analyst View / Opinion on Terahertz Components and Systems Market
- The market has moved beyond a purely academic phase, but adoption remains uneven by application. Spectroscopy and research are established, while communications, semiconductor inspection and inline industrial imaging are the strongest areas for accelerated commercialization.
- The most attractive growth opportunities are in platforms that reduce complexity: integrated sources and detectors, frequency-extender modules, automated spectroscopy, AI-assisted imaging and semiconductor-test workflows.
- 6G will be an important demand catalyst before mass deployment because device companies, telecom vendors and universities must build measurement infrastructure years in advance.
- Semiconductor inspection may become one of the most defensible industrial opportunities because advanced packaging creates high-value defects that justify premium metrology.
- Specialist THz vendors will remain important, but large test, photonics and instrumentation companies can gain share as the market requires global support, calibration, software and integration.
- Long-term leadership will depend on repeatable application outcomes rather than record laboratory frequency alone. Suppliers that demonstrate throughput, sensitivity, reliability and integration will capture the greatest commercial value.
Terahertz Components and Systems Market Target Audience
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| Test & Measurement | Product managers, RF engineers, strategy and business development teams | Assess sub-THz and 6G test demand, component partnerships and technology roadmaps. |
| Semiconductor & Electronics | Device makers, fabs, packaging companies and metrology teams | Evaluate THz inspection, device characterization and future integrated transceiver opportunities. |
| Photonics & Optics | Laser, detector, optics and component suppliers | Identify demand for THz sources, detectors, waveguides and optical components. |
| Telecommunications | 6G research teams, network vendors and operators | Understand sub-THz test, channel, antenna and signal-analysis requirements. |
| Aerospace & Defense | Prime contractors, sensing teams and research laboratories | Assess radar, imaging, security and stand-off sensing opportunities. |
| Industrial NDT | Inspection companies, OEMs and quality-control teams | Evaluate THz for dielectric materials, composites, coatings and process monitoring. |
| Investors & Consulting | Private equity, venture capital, corporate strategy and consultants | Support technology screening, partnership analysis and commercialization assessment. |
Why Choose DATAM?
- Data-driven insights combining market sizing, technology segmentation, competitive analysis and buyer requirements.
- Post-purchase analyst consultations for market entry, partnership strategy, product positioning and custom segmentation.
- Annual updates covering major product launches, research milestones, funding, standards and competitive developments.
- Specialized coverage of emerging applications such as 6G, semiconductor metrology and AI data-center interconnects.
- Actionable analysis connecting component performance with system economics and application adoption.
What DATAM Uniquely Provides
- Ten-year forecasts across eight segmentation categories and five major regions.
- Detailed value-chain analysis covering semiconductor platforms, THz sources, detectors, optics, system integrators, test companies and end users.
- Public-company Q1-Q2 2026 performance context for five listed companies with relevant high-frequency, photonics, imaging or analytical exposure.
- A market ecosystem table mapping representative companies across each sector of the terahertz value chain.
- Buyer-focused analysis of dynamic range, power, sensitivity, portability, software and system-integration requirements.
- Country-level views connecting 6G research, semiconductor investment, defense activity and scientific infrastructure.



























































