


Small-Scale LNG Market Size and Overview
The global small-scale LNG market reached USD 21.89 billion in 2025 and is expected to reach USD 44.12 billion by 2035, growing with a CAGR of 7.26% during the forecast period 2026-2035. The market expansion is supported by the increasing availability of LNG along with the creation of flexible natural gas supplies for the transportation, industry, power generation and marine sectors. According to the International Energy Agency (IEA), around 300 billion cubic meters per year (bcm/yr) of additional LNG export capacity would be installed across the world by 2030, and global LNG supply could rise by around 250 bcm by 2030. The increasing number of suppliers will be helpful in ensuring the supply of cheaper natural gas, especially in price-sensitive LNG-importing countries.
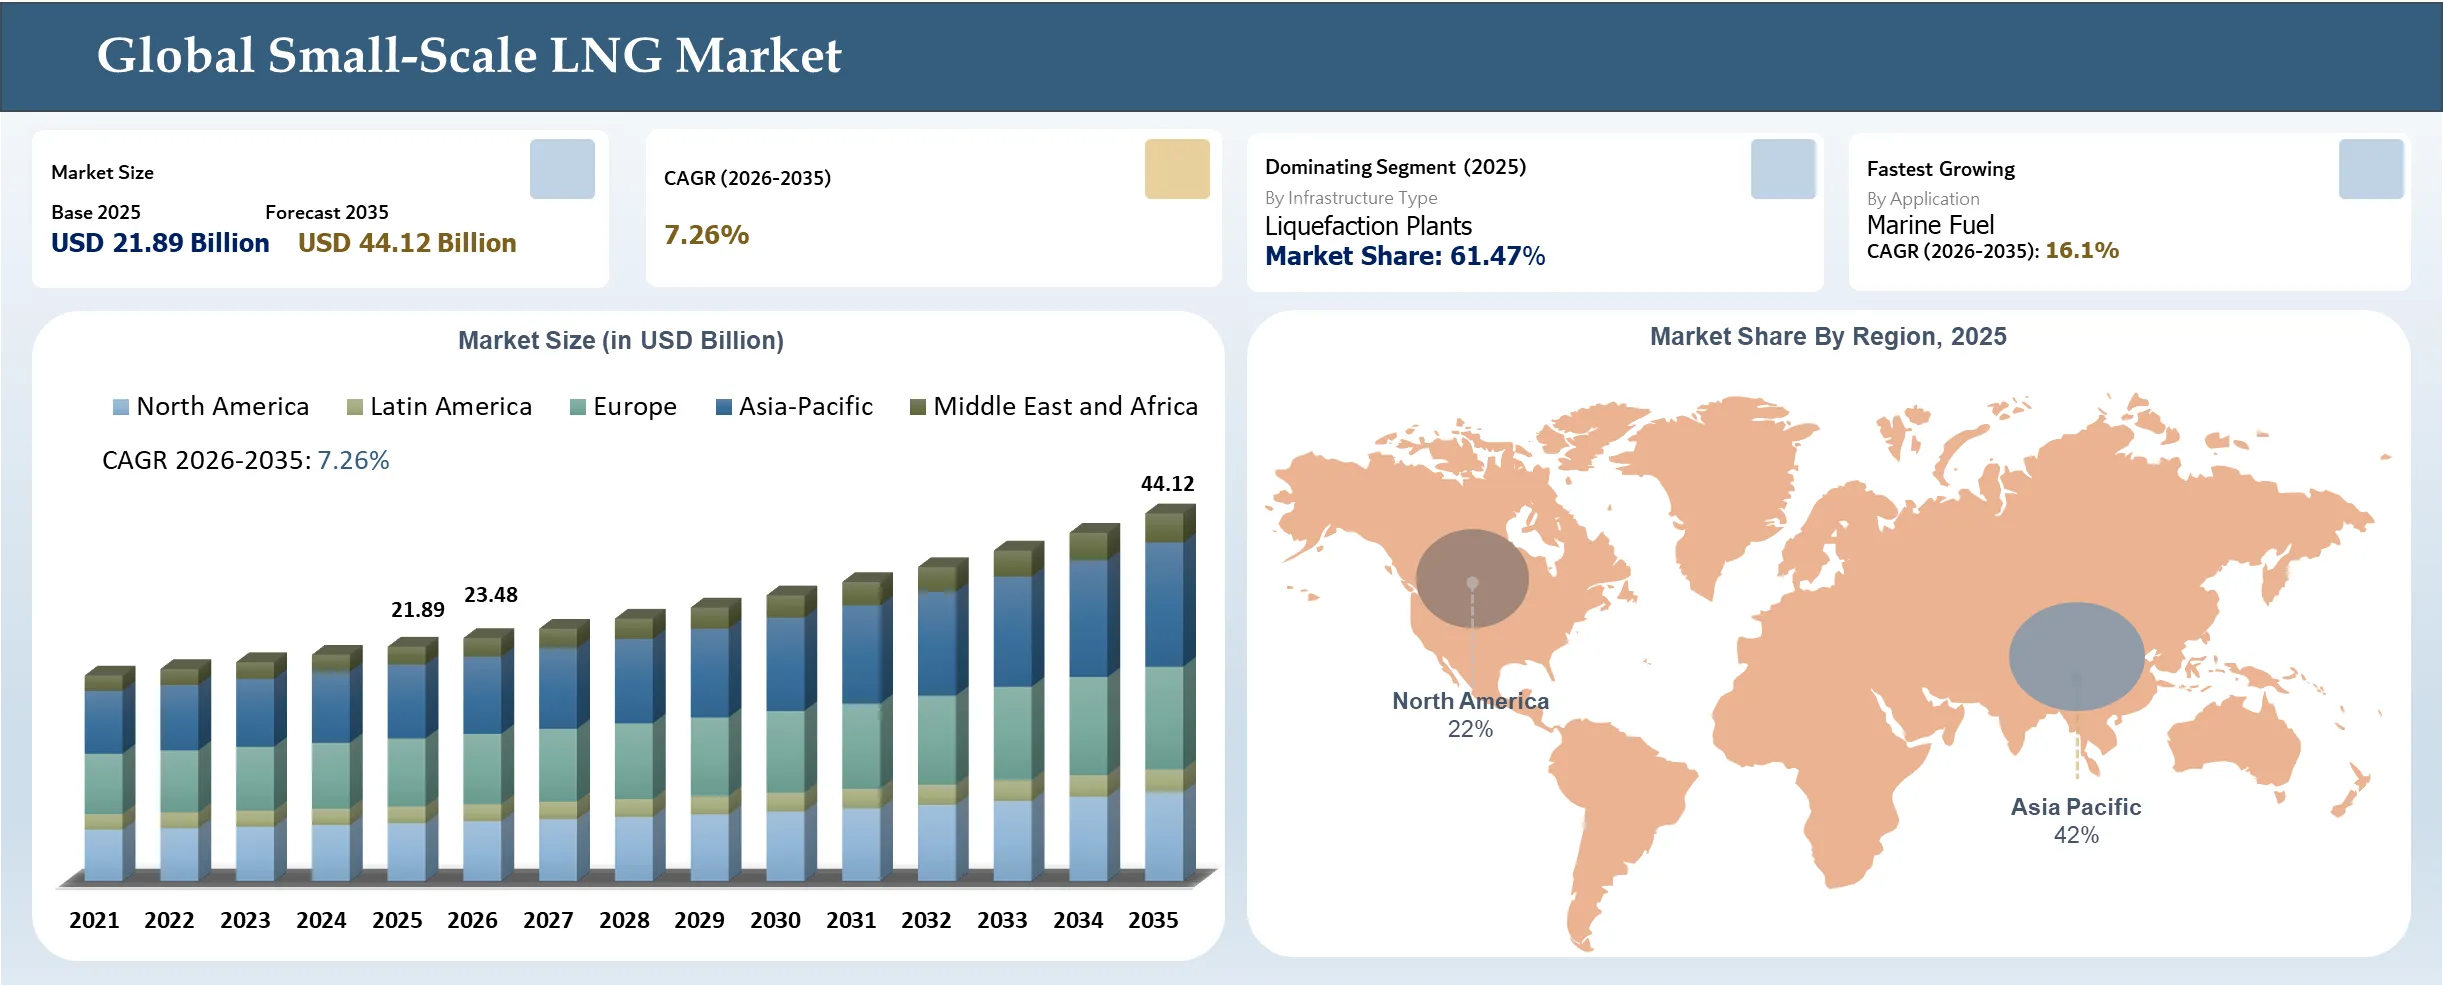
The market is further supported by rising LNG use in transport and marine applications, thus increasing the demand for decentralised LNG distribution and bunkering networks. According to the IEA, the global consumption of natural gas is estimated to rise by 380 bcm by 2030. The demand for natural gas in the Asia-Pacific region will account for half of the growth in the global market of natural gas; on the other hand, natural gas consumption in the transport sector will see an increase of about 35 bcm annually, and LNG consumption in maritime transport will see an annual increase of 15 bcm through 2030. Moreover, more than 90 bcm annually of liquefied natural gas capacity has reached FID by 2025, of which 80 bcm/yr is from the US alone.
White-Space Opportunities for Small-Scale LNG Distribution and Remote Power Generation
In March 2025, Indonesia launched a USD 1.5 billion small-scale LNG initiative led by PLN Energi Primer Indonesia (PLN EPI) to replace diesel-fired power generation across the country's islands, making LNG distribution and hub-and-spoke infrastructure the highest-investment opportunity within the project. The investment is focused on developing main LNG receiving terminals, small LNG tanker transportation, satellite regasification facilities, and gas-delivery infrastructure for power plants, with four infrastructure clusters already tendered to serve 41 existing and new power plants with a combined capacity of 2,148 MW.
The project is expected to begin operations between late 2026 and 2027, create demand for at least 29 LNG cargoes (approximately 2 million tonnes of LNG), displace around 2.3 million kilolitres of diesel annually, and generate approximately USD 300 million in annual savings.
LNG demand represents a significant recurring supply opportunity beyond the initial infrastructure expenditure. PLN EPI benefits from expanded LNG procurement and logistics, while AG&P LNG is positioned in small-scale LNG infrastructure and cluster development; Pertamina can benefit from LNG supply, transportation, and downstream gas infrastructure, while JERA can participate in LNG procurement and supply optimisation.
In marine LNG transportation, companies such as MISC Berhad, Mitsui O.S.K. Lines (MOL), NYK Line, and Kawasaki Kisen Kaisha (K Line) can benefit from demand for small LNG carriers and inter-island LNG distribution. In regasification, storage, and terminal infrastructure, Excelerate Energy, Höegh Evi, Golar LNG, and Pertamina can benefit from FSRU, LNG storage, and regasification requirements, while Air Products, Chart Industries, and Wärtsilä can benefit from LNG handling, storage, regasification, and related equipment requirements.
In pipeline connections and gas distribution, PGN, Pertamina Gas, and Gas Entec can benefit from gas transportation and distribution infrastructure, while Siemens Energy, GE Vernova, Mitsubishi Heavy Industries, and Kawasaki Heavy Industries can benefit from power-generation conversion and gas-fired generation equipment.
Small-Scale LNG Market Strategic Takeaways
- The Asia-Pacific region held the largest market share at 42% in 2025 due to rapid gas adoption. It stands as both the largest and fastest-growing regional market for small-scale LNG globally.
- Liquefaction plants dominated the infrastructure segment by capturing a 61.47% market share in 2025. Modern modular construction reduces peak site labour from 10,000 workers to under 2,000 while shifting over 10 million man-hours offsite.
- By 2025, more than 90 bcm annually of liquefied natural gas capacity reached Final Investment Decision (FID) globally. The United States accounted for the vast majority of this milestone, contributing 80 bcm/yr alone.
- Indonesia launched a USD 1.5 billion initiative to convert 41 islands from diesel-fired power to small-scale LNG. The infrastructure buildout targets 2,148 MW of combined capacity to displace 2.3 million kilolitres of diesel annually and yield USD 300 million in annual savings.
Small-Scale LNG Market Industry Trends and Strategic Insight
- Decentralised LNG distribution is becoming a core industry model, with truck-based delivery, ISO containers, satellite regasification, and small receiving facilities extending LNG access beyond conventional pipeline networks.
- LNG bunkering is emerging as a strategic demand centre, encouraging suppliers to develop ship-to-ship transfer capabilities, marine LNG terminals, and flexible bunkering networks along major shipping corridors.
- Modular and scalable infrastructure is gaining importance, allowing LNG suppliers to match liquefaction, storage, regasification, and transportation capacity with localised demand rather than relying exclusively on large centralised projects.
- Asia-Pacific is becoming a critical strategic focus for decentralised LNG supply, as expanding gas demand, uneven pipeline coverage, industrial fuel switching, and infrastructure development create opportunities for flexible LNG delivery models.
- Small-scale LNG projects are increasingly being designed for scalability, allowing operators to expand storage, liquefaction, regasification, or distribution capacity progressively as local demand develops rather than committing to oversized infrastructure at the initial stage.
Small-Scale LNG Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 21.89 Billion | |
| 2035 Projected Market Size | USD 44.12 Billion | |
| CAGR (2026-2035) | 7.26% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | Asia-Pacific | |
| By Infrastructure Type | Liquefaction Plants, Satellite Regasification Terminals, LNG Storage Infrastructure | |
| By Liquefaction Technology | Mixed Refrigerant Liquefaction, Nitrogen Expansion Liquefaction, Modular/Skid-Mounted Liquefaction, Others | |
| By Distribution Mode | Trucking / Virtual Pipeline, Small LNG Carriers & Coastal Shipping, Rail Transport, Bunkering Vessels | |
| By Application | Power Generation, Heavy-Duty Transport Fuel, Marine Fuel, Industrial Fuel, Commercial & Residential Energy, Others | |
| By End-Use | Utilities & Power Producers, Oil & Gas Operators, Mining & Metals, Industrial Manufacturing, Shipping & Maritime, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Small-Scale LNG Market Disruption Analysis
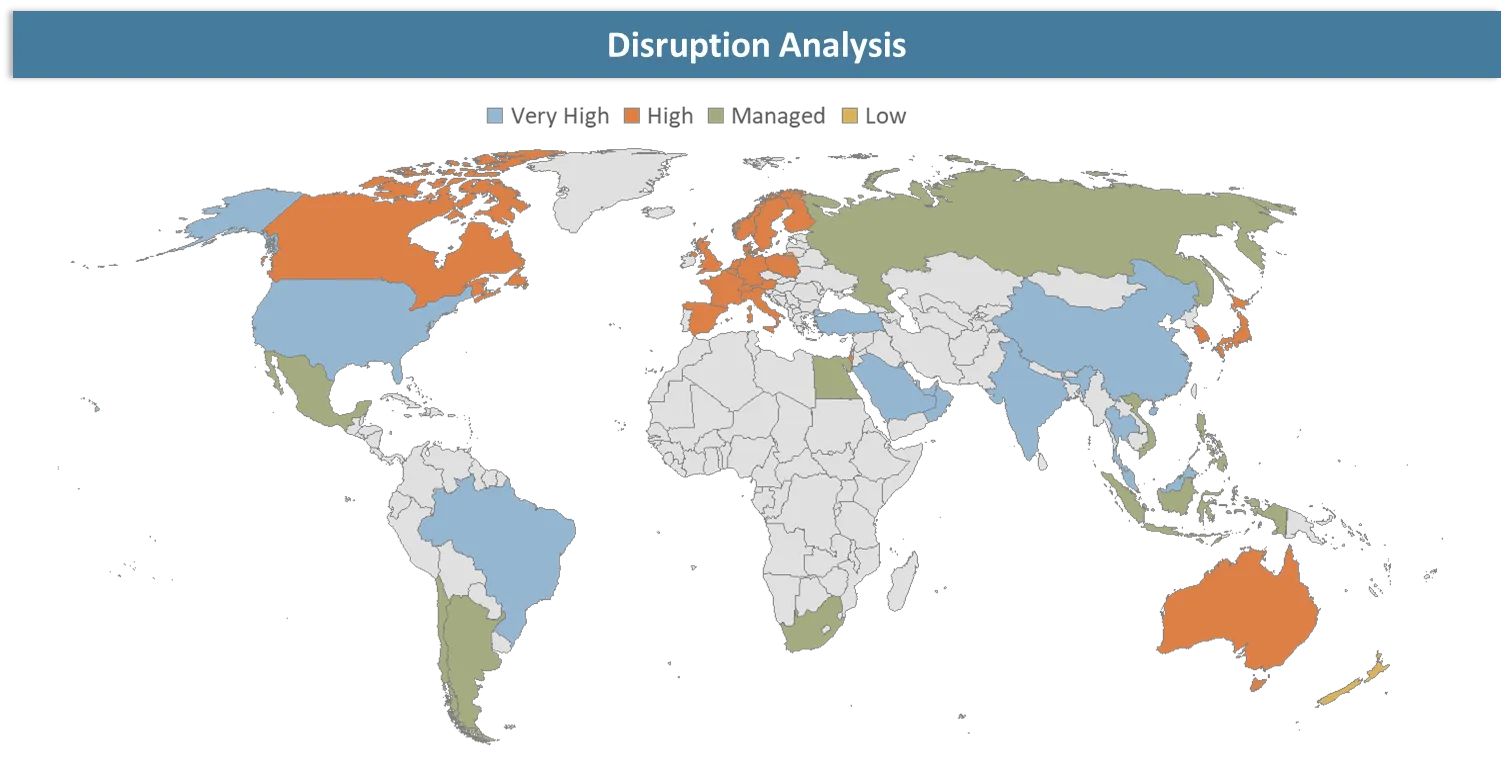
Shift Toward Decentralized LNG Supply Networks Reshaping the LNG Distribution Landscape
The disruption in the small-scale LNG market is primarily associated with the rapid shift from centralised LNG terminals and pipeline-dependent gas distribution toward decentralised LNG supply networks. The use of virtual pipelines, LNG trucking, ISO container deliveries, satellite re-gasification, and modular LNG systems is enabling LNG suppliers to provide LNG deliveries to industrial, power plants, transportation, and distant customers without any need to be connected to conventional pipe-bound gas logistics. It is shifting the existing LNG logistics model from centralised and volumetric deliveries to modular and customer-focused LNG logistics.
In addition, rapid growth in LNG supplies and flexible LNG trade are driving the economic case for decentralised logistics solutions. According to the International Energy Agency (IEA), global LNG supplies grew by nearly 7%, which is 38 bcm, in 2025, and the acceleration in growth of LNG supplies reached 10%, which is 28 bcm, in H2-2025 due to new supplies coming into play. In April 2026, U.S. LNG exports via ISO containers amounted to 0.1 Bcf and demonstrated a 16% year-over-year growth compared to April 2025, according to the U.S. Department of Energy.
Small-Scale LNG Market BCG Matrix: Company Evaluation
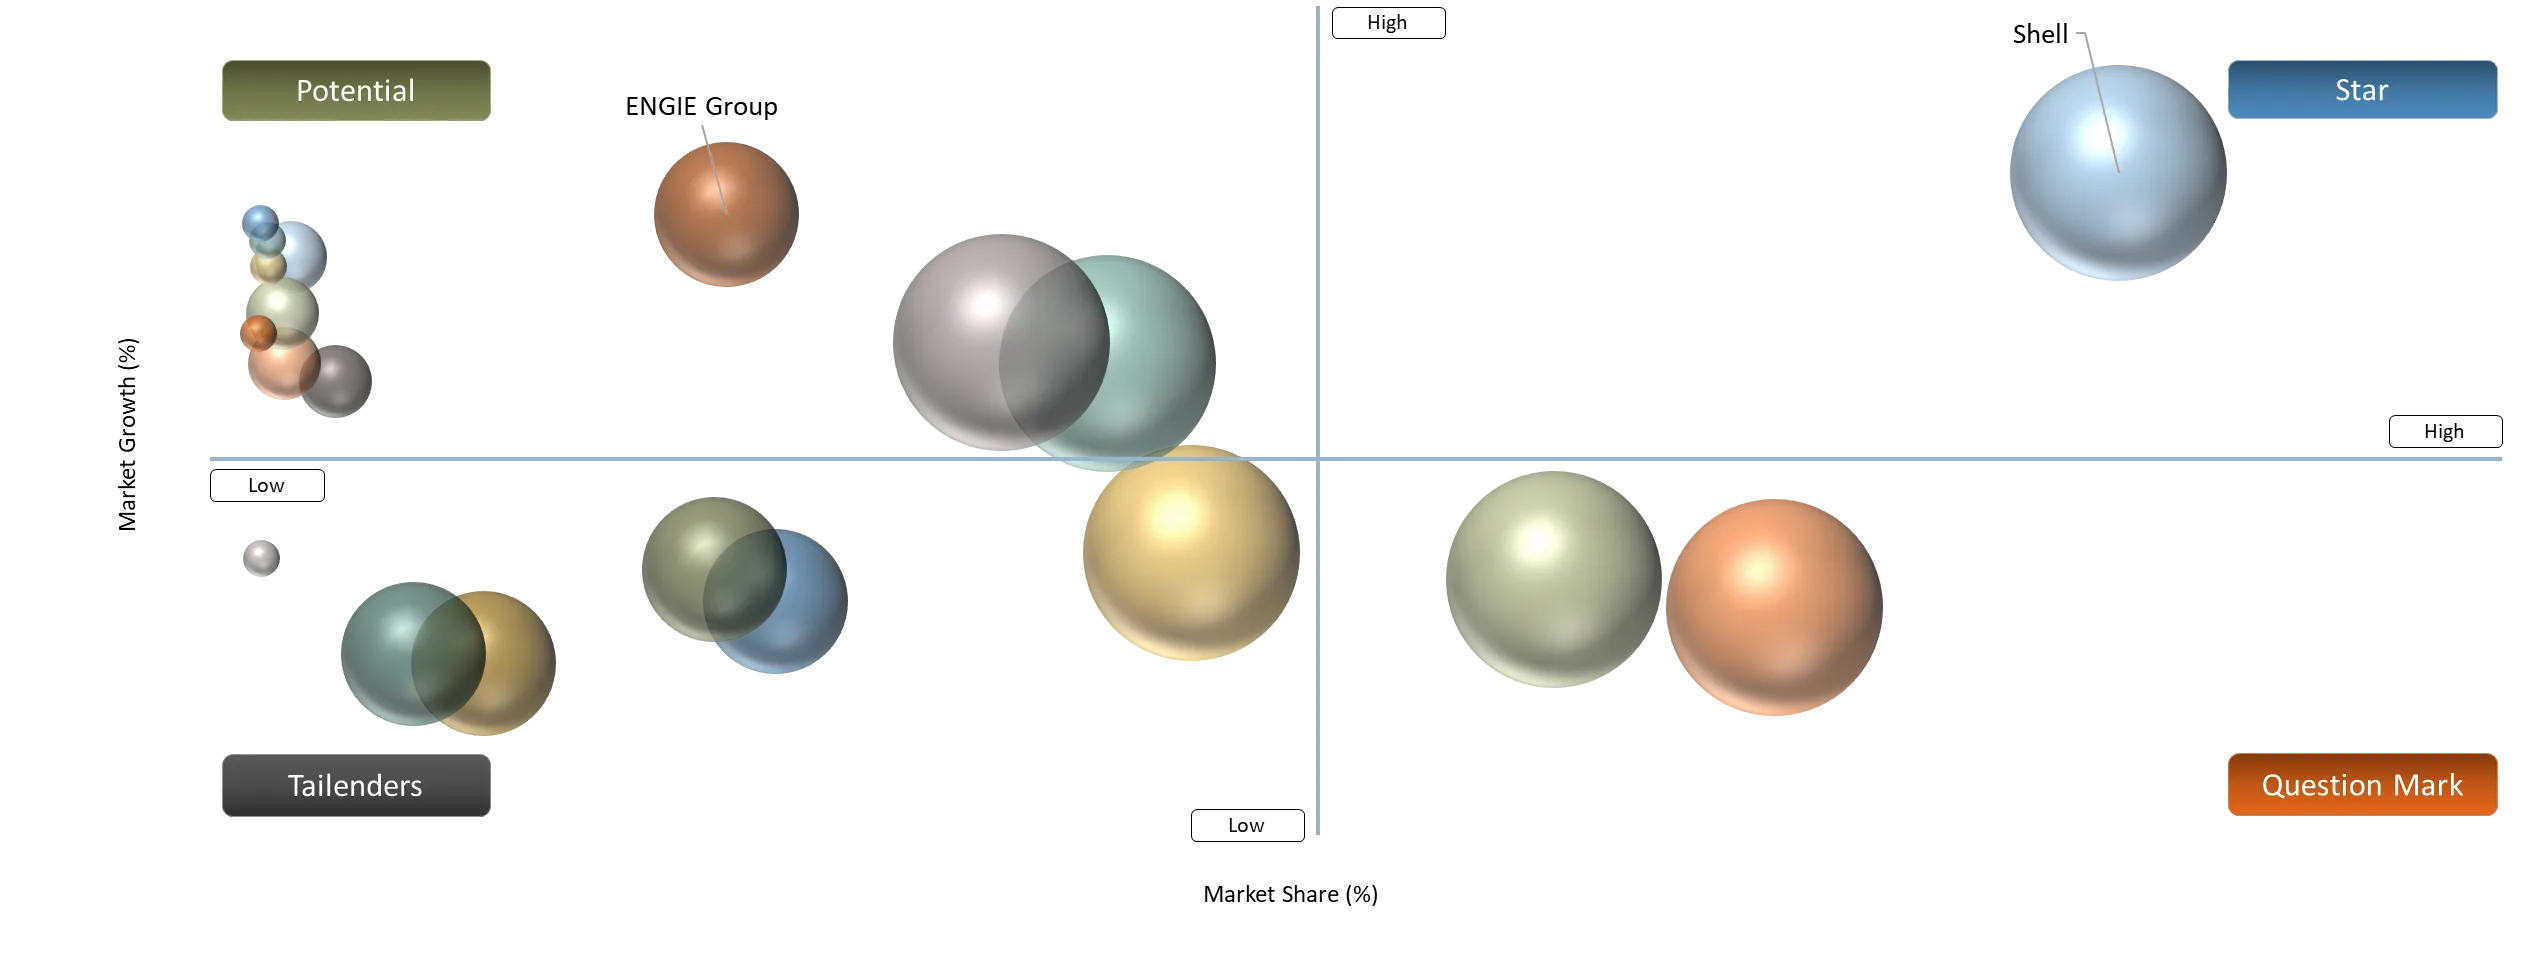
Stars include Shell, TotalEnergies, and Linde PLC because they have strong positions across LNG production, liquefaction, distribution, and small-scale LNG applications, supported by extensive infrastructure and established customer networks. Wärtsilä and Chart Industries are placed in the Question Mark category because they have strong technology and equipment capabilities in small-scale LNG, liquefaction, storage, regasification, and marine applications, while competing in a fragmented market where large integrated energy companies have stronger downstream positions.
The Potential category includes ENGIE Group, Eni S.p.A., and GAIL (India) Limited, which benefit from expanding LNG import, distribution, and downstream gas activities but have comparatively narrower exposure to the global small-scale LNG ecosystem than the leading integrated players. Stabilis Solutions, Inc., Galileo Technologies, and Sofregaz Company belong to the Tailenders category because their activities are more specialised or geographically concentrated within small-scale LNG, modular liquefaction, LNG distribution, or engineering services.
Small-Scale LNG Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Expansion of LNG bunkering is increasing demand for small-scale LNG supply infrastructure as shipping companies adopt LNG as a marine fuel. | 24% | Asia-Pacific, Europe, North America; major ports and shipping corridors | LNG bunkering, marine fuel supply, bunker vessels, ship-to-ship and truck-to-ship fueling | Encourages investment in bunker vessels, LNG storage, small terminals, and port-based distribution infrastructure to capture growing marine-fuel demand. |
Rising demand for LNG in remote and off-grid locations is driving small-scale LNG deployment where pipeline infrastructure is unavailable or uneconomical. | 22% | Asia-Pacific, Latin America, Middle East & Africa; remote industrial and power locations | Remote power generation, off-grid industrial facilities, mining, commercial energy supply | Expands the addressable market beyond pipeline-connected customers and supports modular liquefaction, satellite regasification, and virtual pipeline models. |
Growing LNG supply availability from new liquefaction capacity is improving access to LNG for regional and small-volume consumers. | 19% | Asia-Pacific and Europe, followed by emerging LNG-importing markets | Regional LNG supply, distributed power, industrial fuel switching, small-volume gas consumption | Improves supply security and enables suppliers to develop flexible procurement and distribution models for customers that cannot economically purchase large LNG volumes. |
Increasing truck-loading and small-volume LNG distribution infrastructure is supporting the supply of LNG to industrial and transportation customers. | 21% | Asia-Pacific, North America and Europe; areas with limited pipeline coverage | LNG trucking, virtual pipelines, heavy-duty transportation, industrial fuel supply | Strengthens last-mile LNG distribution and creates opportunities for LNG logistics providers, mobile storage operators, trucking fleets, and satellite regasification developers. |
Expansion of LNG bunkering is increasing demand for small-scale LNG supply infrastructure as shipping companies adopt LNG as a marine fuel
The expansion of LNG bunkering is increasing demand for smaller-scale LNG supply facilities as shippers incorporate more LNG-powered ships into their fleet, while ports develop specialised fueling facilities for marine operations. It has led to investments in bunker ships, LNG storage tanks, ship-to-ship transfer technologies, loading facilities, and local LNG distribution networks. The creation of such flexible facilities enables LNG suppliers to cater to the needs of marine customers at each port and shipping route independently of large-scale centralised LNG facilities.
In parallel, the rapid increase in LNG bunkering is boosting the need for small-scale LNG infrastructure. In January 2026, according to Kpler, the total amount of global LNG bunkering reached almost 4 million tonnes in 2025 and rose by 38% year-over-year despite there being just three new LNG bunker ships delivered over the year. The Asia region saw its LNG bunkering volumes increase by 45% year-over-year, while in the Americas region, the volume of LNG bunkering was up by 57%, and in Europe, LNG bunkering increased by 26%. Also, according to Kpler, more than 500 dual-fuel ships made the actual demand for LNG reach 4 mtpa, although the potential demand stood at around 11 mtpa, which left 7 mtpa of unfulfilled demand due to economic and logistical issues.
Small-Scale LNG Market Segment Analysis
The global small-scale LNG market is segmented based on infrastructure type, liquefaction technology, distribution mode, application, end-use, and region.
Modular Liquefaction Technology Enhancing the Scalability of Small-Scale LNG Infrastructure
The liquefaction plants segment dominated the small-scale LNG market by infrastructure type, accounting for a 61.47% market share in 2025. The dominance is driven by the essential role of liquefaction facilities in converting natural gas into LNG for subsequent storage, transportation, bunkering, and decentralised energy applications. The increasing adoption of small-scale liquefaction systems is particularly important in regions where pipeline infrastructure is limited, allowing LNG producers and distributors to establish localised supply networks and serve industrial, transportation, power-generation, and remote customers.
In parallel, the development of modular liquefaction technology makes LNG production infrastructure more scalable and financially feasible. In September 2025, according to Reuters, Baker Hughes offers modular LNG facilities with an output of 0.8-2 million tons per year (mtpa) each, thus making the production of LNG more economically feasible in case of small gas reserves and geographically distant areas. Furthermore, Reuters claims that Commonwealth LNG’s 9.5 mtpa project will utilise modular construction techniques with no more than 2,000 construction workers in the peak period of construction against 8,000-10,000 in the case of stick-built facilities, and more than 10 million man-hours of work are moved from site construction to fabrication shops.
Small-Scale LNG Market Geographical Penetration
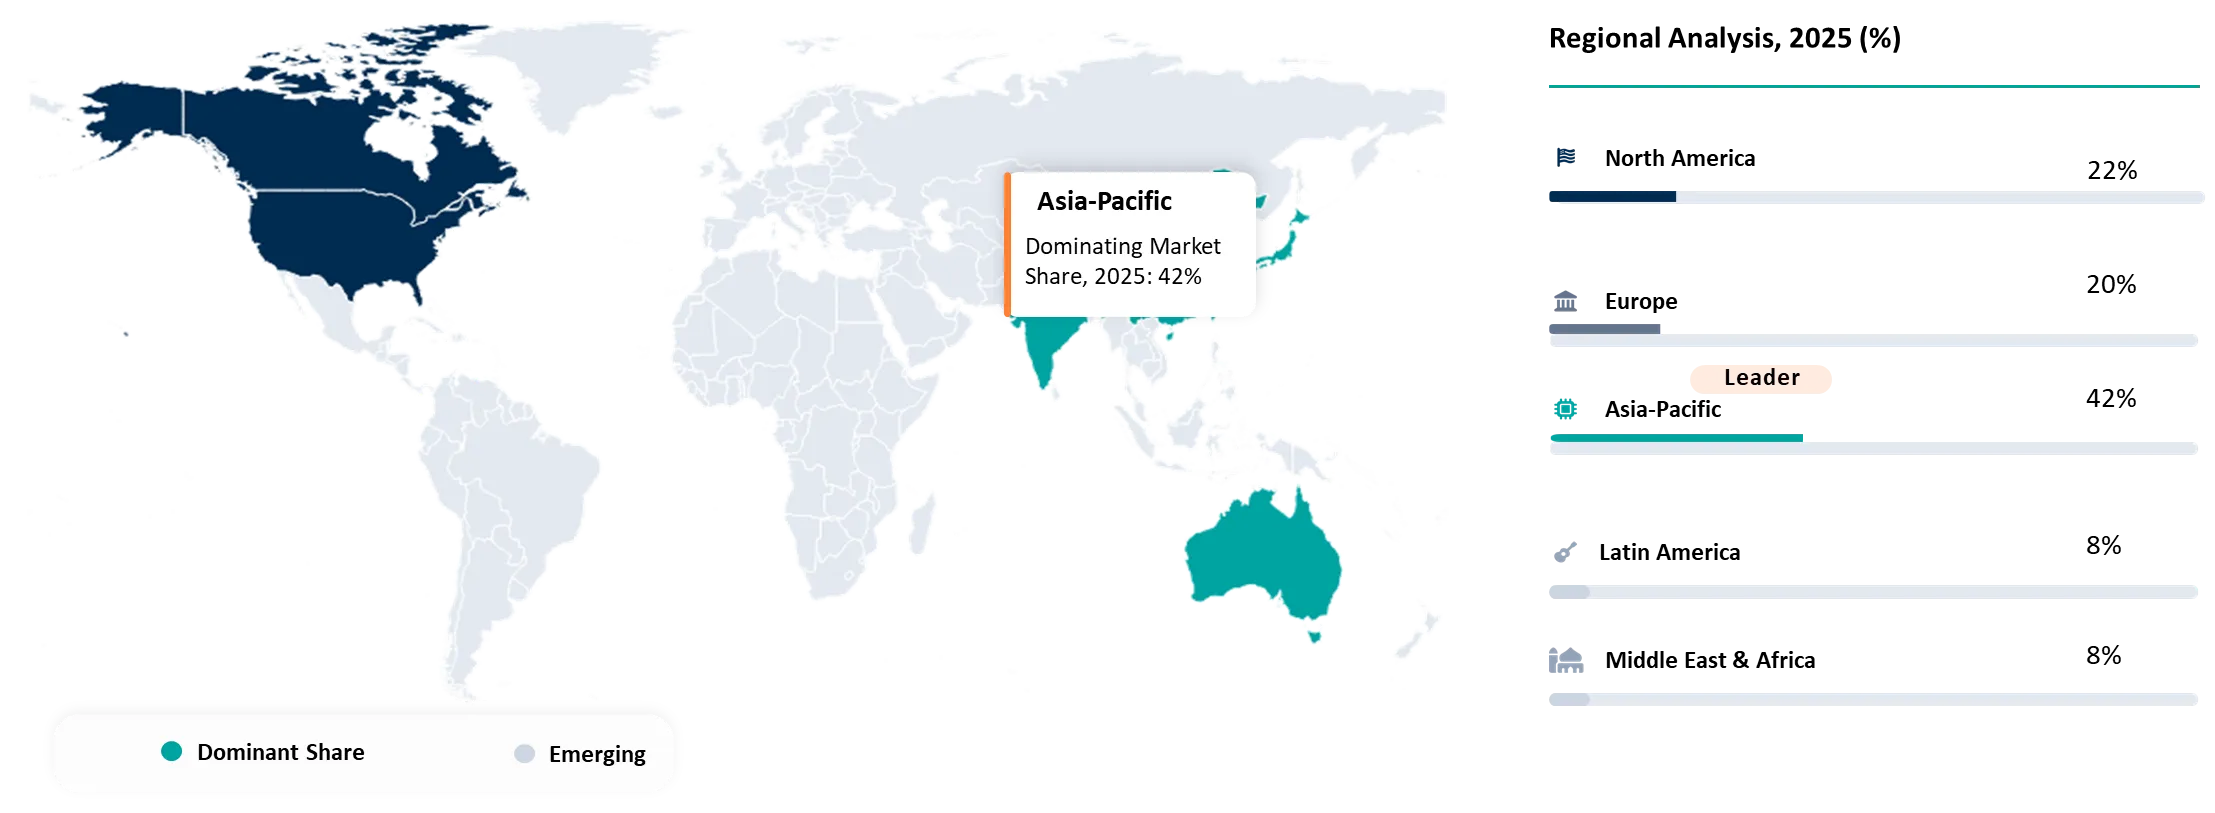
Rapid LNG Infrastructure Development and Decentralised Supply Expansion in Asia-Pacific
The Asia-Pacific region dominates the small-scale LNG market, accounting for a 42% market share in 2025, supported by its large and geographically dispersed natural gas demand base, expanding LNG import infrastructure, industrial fuel switching, LNG trucking, and growing marine-fuel requirements. The region's combination of major LNG importers and emerging gas markets is accelerating the deployment of small-scale liquefaction, satellite regasification, LNG storage, virtual pipelines, and bunkering infrastructure.
The partnership expands small-scale LNG infrastructure for off-grid power generation in the Philippines. In July 2025, Philippine National Oil Company (PNOC), the Philippines-based state-owned energy company, signed a framework agreement with Pertamina Gas, an Indonesian-based state-owned natural gas infrastructure and transportation company, to develop and supply small-scale LNG (ssLNG) to Basilan. The initiative targets underserved and off-grid areas of Basilan, where LNG is intended to support the hybridisation of existing diesel power generation and improve energy reliability.
China Small-Scale LNG Market Trends
China holds the dominant position in the Asia-Pacific small-scale LNG market, supported by its extensive LNG import and distribution infrastructure, large industrial gas-consuming base, expanding LNG trucking ecosystem, and rapidly developing marine LNG bunkering network. The country benefits from a broad ecosystem connecting LNG import terminals, storage facilities, transportation networks, industrial consumers, and maritime hubs, which enables LNG to be distributed beyond conventional pipeline-connected customers.
In May 2026, Shaanxi Heimao Coking Co., Ltd. (Shaanxi Heimao), a China-based coal-chemical and coking company, announced plans to absorb its wholly owned subsidiary Hancheng Heimao Gasification Co., Ltd., a China-based chemical and gasification company. The subsidiary’s planned product portfolio includes LNG, methanol, liquid ammonia, sulfur, and deep-processed chemical coke. As of December 2025, Hancheng Heimao Gasification reported RMB 59.68 million (USD 8.90 million) in total assets, RMB 52.38 million (USD 7.81 million) in net assets, and a RMB 4.88 million (USD 0.73 million) net loss, while Shaanxi Heimao reported RMB 10.13 billion (USD 1.51 billion) in 2025 operating revenue and a RMB 1.18 billion (USD 176.1 million) net loss attributable to shareholders.
Japan Small-Scale LNG Market Outlook
Japan is one of the major countries in the Asia-Pacific small-scale LNG market, supported by its mature LNG import infrastructure, established gas distribution network, extensive maritime activity, and strong focus on energy security. The country has continued to develop flexible LNG supply mechanisms that connect import terminals with power producers, industrial users, transportation operators, and marine customers.
The project expands satellite LNG infrastructure for industrial fuel conversion in Japan. In August 2025, Sakurambo Smart Energy LLC, a Japan-based energy services company, jointly established by Tokyo Gas Engineering Solutions Corporation (TGES), a Japan-based energy engineering and services company, Japan Petroleum Exploration Co., Ltd. (JAPEX), a Japan-based oil and gas exploration and production company, and YAMAGATA GAS Co., Ltd., a Japan-based gas utility, launched a natural-gas fuel conversion project at the Higashine Omori Industrial Park in Yamagata Prefecture with Resonac Hard Disk Corporation, a Japan-based electronic components manufacturer.
Sakurambo Smart Energy will install LNG satellite facilities and boilers at Resonac’s Yamagata factory, with construction starting in September 2025 and LNG supply targeted for May 2026.
Rapid LNG Export Expansion and Flexible Supply Infrastructure Strengthening North America's Small-Scale LNG Market
The North America region accounted for a 22% market share of the small-scale LNG market in 2025, supported by its abundant natural gas resources, established LNG infrastructure, expanding export capacity, and growing network of flexible LNG distribution channels. The region benefits from the combination of LNG liquefaction facilities, storage infrastructure, trucking networks, marine terminals, and emerging small-scale export routes, creating a well-developed ecosystem for supplying LNG to industrial, transportation, marine, and geographically dispersed customers.
The merger strengthens modular small-scale LNG production and distribution infrastructure across North America. In July 2025, United Energy LNG, a U.S.-based LNG infrastructure and development company, and Power LNG, a U.S.-based modular LNG project developer, announced a strategic merger to establish a scalable small-scale LNG platform serving industrial, power, and transportation markets across North America.
The combined company oversees three LNG production sites in advanced development, including projects in Houston, Texas, and Independence, Kansas, with targeted combined liquefaction capacity of up to 540,000 metric tonnes per annum (MTPA). The projects represent an estimated USD 240–270 million in capital investment and are designed around modular liquefaction units and virtual LNG pipeline logistics for distributed and underserved markets.
U.S. Small-Scale LNG Market Trends
The U.S. holds a dominant position in the North American small-scale LNG market, supported by abundant natural gas availability, extensive LNG liquefaction infrastructure, established storage and transportation networks, and growing demand for flexible LNG distribution. The country's combination of large-scale LNG production with truck-based distribution, containerised LNG, small-volume exports, marine bunkering, and decentralized gas supply provides a strong platform for small-scale LNG applications.
The acquisition expands small-scale LNG production, storage, and distribution capacity across the U.S. In September 2026, Sapphire Gas Solutions, a U.S.-based distributed energy infrastructure and mobile natural gas solutions provider, acquired assets from Spectrum LNG, a U.S.-based small-scale LNG producer, including the operating Desert Gas LNG Plant in Ehrenberg, Arizona, and a future expansion site in Stroud, Oklahoma. The Desert Gas facility has approximately 100,000 gallons of LNG storage capacity and 76,000 gallons/day of operational LNG production capacity, supplying municipal, commercial, and industrial customers across the Southwest U.S. and Southern California.
Small-Scale LNG Market Competitive Landscape
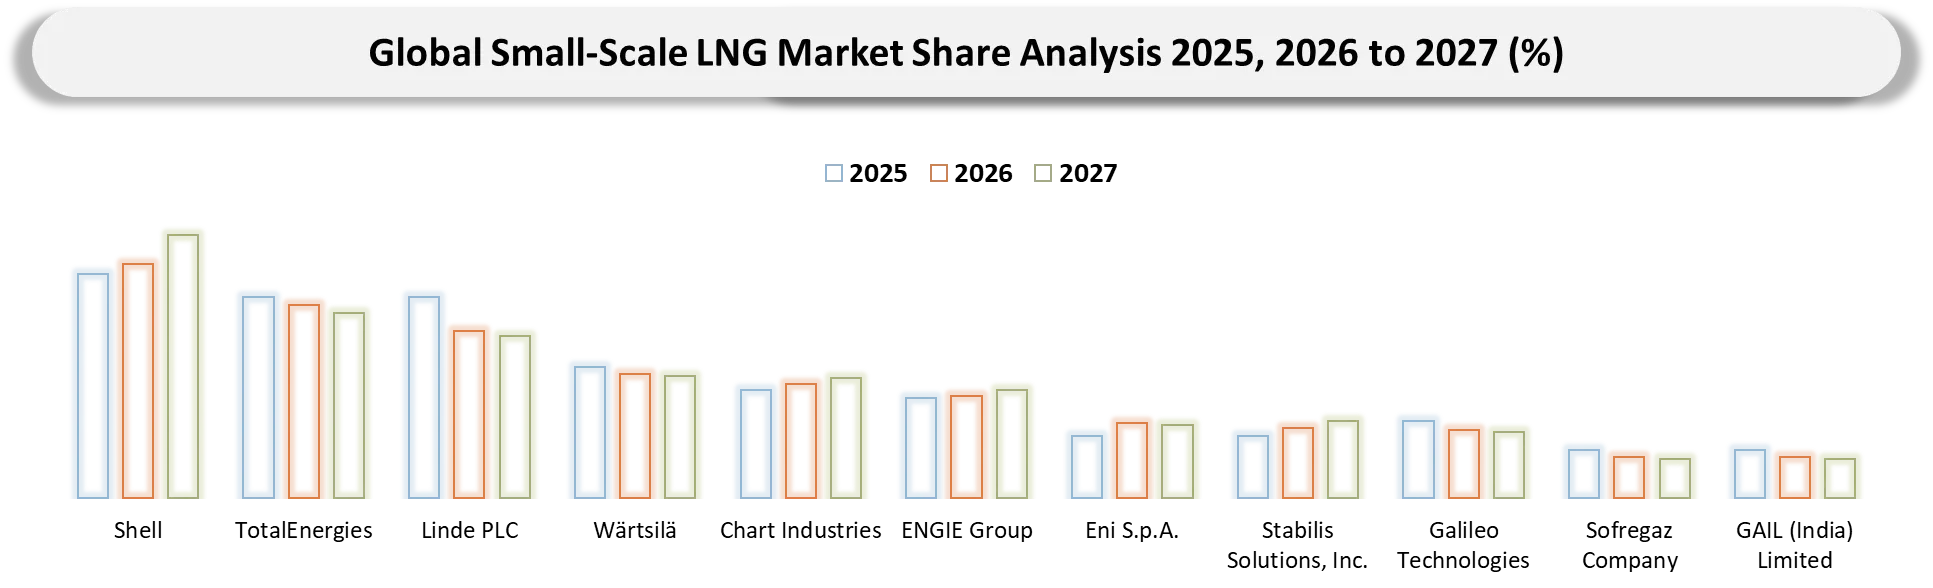
- The small-scale LNG market is characterized by three key participant groups: integrated LNG companies, small-scale LNG technology and infrastructure providers, and specialised LNG distribution and engineering companies. Shell, TotalEnergies, ENGIE Group, Eni S.p.A., and GAIL (India) Limited compete through LNG sourcing, liquefaction, storage, distribution, and marine-fuel supply; Linde PLC, Wärtsilä, and Chart Industries focus strongly on liquefaction, cryogenic equipment, LNG storage, regasification, and bunkering technologies; while Stabilis Solutions, Galileo Technologies, and Sofregaz Company specialise in decentralised LNG production, transportation, modular solutions, and engineering services. The competitive environment therefore combines vertical LNG integration, infrastructure scale, technology specialisation, and flexible last-mile distribution capabilities.
- Key players include Shell (United Kingdom), TotalEnergies (France), Linde PLC (United Kingdom), Wärtsilä (Finland), Chart Industries (United States), ENGIE Group (France), Eni S.p.A. (Italy), Stabilis Solutions, Inc. (United States), Galileo Technologies (Argentina), Sofregaz Company (France), and GAIL (India) Limited (India).
Key Developments
- September 2026: GasEntec Co., Ltd., a South Korea-based LNG technology and modular infrastructure company, and Samsung Heavy Industries Co., Ltd. (SHI), a South Korea-based shipbuilding and maritime engineering company, signed an MOU under which GasEntec will license SHI’s SENSE liquefaction technology for small-scale LNG applications ranging from 50,000 to 1 million tonnes per annum (MTPA).
- May 2025: Bosowa Energy Group, an Indonesia-based energy company, and BK LNG Solution Pte. Ltd. (BKLS), a Singapore-based LNG solutions provider, signed a strategic MOU to develop LNG infrastructure and accelerate Indonesia’s energy transition.
- January 2026: Reethau Group, an Indonesia-based clean-energy company, and Rieckermann, a Germany-based industrial engineering and technology services company, signed a development agreement for a mini-LNG liquefaction plant in Indonesia.
- April 2026: GTT (Gaztransport & Technigaz), a France-based LNG technology and engineering company, received an order from Beijing Petrochemical Engineering Co., Ltd. (BPE), a China-based petrochemical engineering company, to design a 10,000 m³ onshore LNG storage tank for the Yangjiawan LNG liquefaction plant in Yan’an, Shaanxi Province, China.
- March 2026: Stolt-Nielsen Limited, a Norway-based logistics and investment company, through its subsidiary Stolt-Nielsen Gas Ltd., agreed to sell 50% of Avenir LNG Limited to Nippon Yusen Kabushiki Kaisha (NYK Line), a Japan-based global shipping and logistics company, creating a strategic joint venture in small-scale LNG.
- September 2026: Sapphire Gas Solutions, a U.S.-based distributed energy infrastructure and mobile natural gas solutions provider, acquired assets from Spectrum LNG, a U.S.-based small-scale LNG producer, including the operating Desert Gas LNG Plant in Ehrenberg, Arizona, and a future expansion site in Stroud, Oklahoma.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organisations investing in the small-scale LNG market increasingly select suppliers based on their ability to provide reliable LNG liquefaction, storage, transportation, and regasification systems that can operate efficiently at smaller and geographically dispersed demand centres.
- The procurement decision-making process is increasingly influenced by the expansion of LNG bunkering, virtual pipelines, remote industrial gas supply, heavy-duty transportation, and decentralised power generation, requiring flexible infrastructure that can accommodate fluctuating LNG demand.
- Buyers evaluate suppliers based on LNG production capacity, storage capability, cryogenic equipment reliability, boil-off-gas management, energy efficiency, safety performance, and operational availability when selecting small-scale LNG technology and infrastructure providers.
Why Choose DataM?
- Technological Innovations: Explores advancements in small-scale LNG technologies, including modular liquefaction, skid-mounted systems, satellite regasification, cryogenic storage, ISO containers, mobile LNG systems, and LNG bunkering infrastructure, enabling flexible and decentralised LNG supply.
- Infrastructure Performance & Market Positioning: Evaluates how market participants differentiate through liquefaction efficiency, storage capacity, boil-off-gas management, regasification performance, transportation flexibility, safety, and scalability across industrial, transportation, power, and marine applications.
- Real-World Applications: Highlights deployment of small-scale LNG across LNG bunkering, heavy-duty transportation, remote power generation, mining, industrial manufacturing, commercial energy supply, and locations without access to conventional natural-gas pipeline infrastructure.
- Market Updates & Industry Changes: Tracks LNG infrastructure expansions, modular liquefaction projects, LNG bunkering developments, virtual pipeline networks, containerised LNG distribution, and regional investments across Asia-Pacific, North America, Europe, and emerging LNG markets.
- Competitive Strategies: Analyses how leading companies strengthen their positions through LNG infrastructure expansion, modular technology development, strategic partnerships, supply agreements, bunkering networks, and integrated liquefaction-to-distribution capabilities.
- Pricing & Market Access: Examines LNG pricing differences based on feedgas costs, liquefaction scale, transportation distance, storage requirements, regasification costs, and delivery method, while assessing access through LNG terminals, trucking networks, virtual pipelines, bunkering facilities, and decentralised supply systems.
- Market Entry & Expansion: Identifies opportunities arising from LNG demand growth in remote locations, marine transportation, heavy-duty mobility, industrial fuel switching, and distributed power generation, while outlining strategies involving modular infrastructure, localised supply hubs, flexible logistics, and regional partnerships.
Target Audience 2026
- LNG Producers & Suppliers
- LNG Infrastructure Developers
- LNG Transportation & Logistics Companies
- LNG Bunkering Operators & Marine Companies
- Industrial Energy Consumers
- Power Generation Companies & Utilities
- Heavy-Duty Transportation Operators




























































