Major Depressive Disorder Market Size and Overview
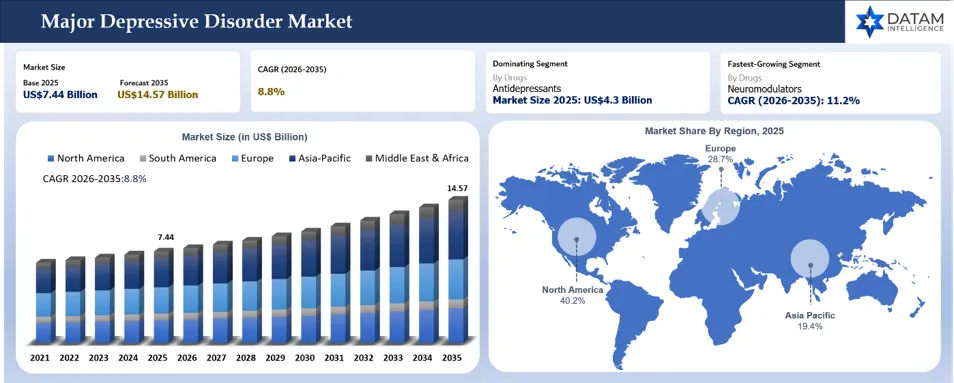
The major depressive disorder market reached US$7.44 billion in 2025 and is expected to reach US$14.57 billion by 2035, growing with a CAGR of 8.8% during the forecast period 2026-2035. The global Major Depressive Disorder Market is expanding as rising diagnosis rates, increasing mental-health awareness and persistent unmet need drive demand for more effective treatment options. The market is transitioning beyond conventional antidepressants toward differentiated therapies offering faster onset, improved remission rates and better outcomes for patients with inadequate response to first-line treatment. Selective serotonin reuptake inhibitors and other established oral antidepressants continue to support large prescription volumes, while adjunctive antipsychotics, intranasal therapies, neuromodulation and emerging neuroplastogen-based treatments are reshaping the competitive landscape.
Commercial opportunities are particularly strong in treatment-resistant and difficult-to-treat depression, where patients frequently require therapy switching, augmentation or advanced interventions. At the same time, safety, tolerability, treatment adherence, supervised administration requirements and reimbursement remain important adoption barriers. Competitive differentiation is increasingly centered on rapid symptom improvement, durable response, convenient dosing, reduced monitoring burden and stronger real-world treatment persistence.
Major Depressive Disorder Market Key Takeaways
- The global major depressive disorder market reached approximately US$7.44 billion in 2025 and is projected to grow at a CAGR of 8.8% during 2026-2033, supported by increasing diagnosis, treatment uptake and therapeutic innovation.
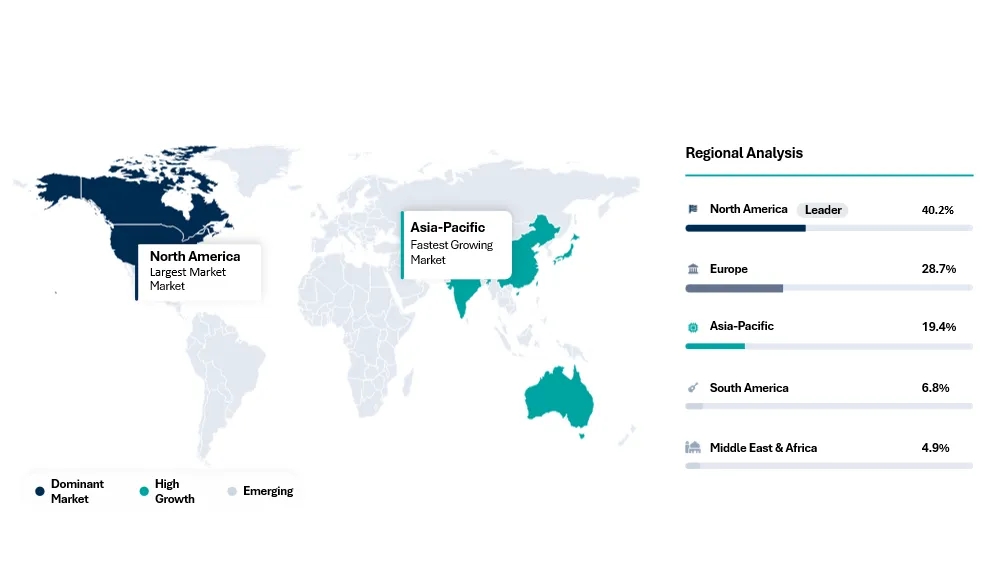
- North America remains the leading regional market, driven by high treatment penetration, strong reimbursement, rapid adoption of branded therapies and availability of advanced options for treatment-resistant depression.
- Market competition is shifting beyond conventional antidepressants toward rapid-acting therapies, adjunctive treatments, NMDA-modulating approaches, neuroplastogens and other differentiated mechanisms targeting patients with inadequate response.
- Treatment-resistant and difficult-to-treat depression represent major high-value opportunities, as these patients often require therapy switching, combination treatment, supervised interventions and more intensive clinical management.
- Future market leadership will depend on delivering faster symptom improvement, durable remission, favorable safety, convenient dosing and reduced monitoring requirements, while also addressing payer access, treatment adherence and affordability.
Major Depressive Disorder Market Scope
| Metrics | Details | |
| 2025 Market Size | US$7.44 Billion | |
| 2035 Projected Market Size | US$14.57 Billion | |
| CAGR (2026-2035) | 8.8% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Drug Type | Antidepressants, Atypical Antidepressants, Antipsychotics, Neuromodulators | |
| By Route of Administration | Oral, Intravenous, Parenteral | |
| By Distribution Channel | Hospital Pharmacies, Retail Pharmacies, Online Pharmacies | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Major Depressive Disorder Market White Space & Investment Opportunities
- Next-Generation Rapid-Acting Therapies Beyond Conventional Antidepressants: Invest in NMDA-modulating therapies, neuroplastogens, psychedelic-derived compounds and other novel mechanisms capable of delivering faster and more durable symptom improvement than conventional antidepressants. Opportunities are particularly attractive for therapies combining rapid onset, sustained efficacy, favorable tolerability and outpatient scalability across moderate-to-severe and difficult-to-treat MDD populations.
- Biomarker-Guided and Precision Treatment Selection: Develop predictive biomarkers, pharmacogenomic tools, digital phenotyping and AI-enabled clinical decision systems that help identify the most appropriate therapy for individual patients. Reducing trial-and-error prescribing could shorten time to response and remission, improve treatment persistence and support more efficient sequencing of antidepressants, augmentation therapies and advanced interventions.
- Convenient, Long-Acting and Lower-Burden Treatment Models: Invest in therapies offering less frequent dosing, simplified administration and reduced monitoring requirements compared with treatments requiring supervised administration. Long-acting oral, injectable, intranasal and other patient-friendly delivery approaches could improve adherence, expand outpatient utilization and reduce healthcare-resource requirements.
- Solutions for Partial Responders and Difficult-to-Treat MDD: Develop therapies specifically targeting patients who achieve inadequate response, residual symptoms or repeated relapse with standard antidepressants. Combination therapies, adjunctive treatments and differentiated mechanisms that improve remission rates without substantially increasing adverse effects represent an important unmet commercial opportunity.
- Integrated Digital and Hybrid Mental-Health Platforms: Invest in digital therapeutics, remote symptom monitoring, telepsychiatry and measurement-based care platforms that complement pharmacological treatment. Integration of clinical assessments, adherence monitoring and real-time patient-reported outcomes could support earlier treatment adjustments, improve continuity of care and expand access to MDD treatment across underserved populations.
Major Depressive Disorder Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Reduction in Depressive Symptom Severity
- Speed of Onset of Antidepressant Effect
- Remission and Response Rates
- Durability and Consistency of Treatment Response
- Safety and Tolerability Profile
- Dosing Frequency and Treatment Convenience
- Need for Supervised Administration and Monitoring
Major Depressive Disorder Market BCG Matrix: Company Evaluation
STAR
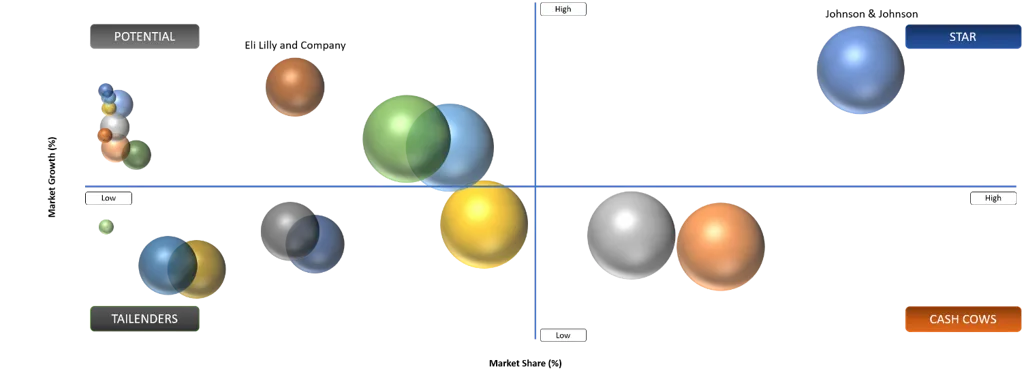
Johnson & Johnson, Axsome Therapeutics, Inc., AbbVie Inc., Otsuka Holdings Co., Ltd., H. Lundbeck A/S and Takeda Pharmaceutical Company Limited are positioned in the Star category based on their established MDD franchises, differentiated mechanisms and strong commercial presence. Johnson & Johnson has significantly strengthened its depression portfolio through SPRAVATO and CAPLYTA; SPRAVATO generated approximately US$1.70 billion in worldwide sales in 2025, representing growth of about 57% from 2024, while CAPLYTA received FDA approval in November 2025 as an adjunctive treatment for adults with MDD. Axsome Therapeutics continues gaining commercial traction with AUVELITY, a differentiated oral MDD treatment that generated approximately US$507.1 million in 2025 net product sales, up 74% year over year. AbbVie maintains a strong adjunctive-treatment position through VRAYLAR, which remains approved for adjunctive treatment of MDD. Otsuka and Lundbeck have an established position through REXULTI, while Lundbeck and Takeda participate through TRINTELLIX, an antidepressant specifically indicated for adults with MDD. Together, these companies combine marketed branded therapies, established physician adoption and continued investment in differentiated depression treatment approaches.
POTENTIAL
Eli Lilly and Company, Pfizer Inc., Biogen Inc., Supernus Pharmaceuticals, Inc., AstraZeneca PLC, GSK plc, Sanofi, Novartis AG, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Viatris Inc., Sun Pharmaceutical Industries Limited, Aurobindo Pharma Limited and Dr. Reddy’s Laboratories Limited are positioned in the Potential category based on a combination of emerging neuroscience pipelines, established antidepressant experience and broad capabilities in supplying conventional depression therapies. Eli Lilly represents one of the strongest innovation-led opportunities within this group following its September 2026 acquisition of AtaiBeckley, which added BPL-003, an intranasal rapid-acting neuroplastogen being developed for treatment-resistant depression. Pfizer retains an established MDD presence through PRISTIQ, an SNRI approved for adults with major depressive disorder, while AstraZeneca has historical participation through SEROQUEL XR as adjunctive therapy for MDD. Supernus strengthened its neuropsychiatry capabilities through the 2025 acquisition of Sage Therapeutics, adding the zuranolone platform and broader CNS development expertise. Biogen also brings substantial neuroscience development and commercialization capabilities. Teva Pharmaceutical Industries, Viatris, Sun Pharmaceutical Industries, Aurobindo Pharma and Dr. Reddy’s Laboratories primarily strengthen the competitive environment through broad generic pharmaceutical portfolios and manufacturing scale, while GSK, Sanofi, Novartis and Merck possess the R&D infrastructure and global commercialization capabilities to pursue future opportunities in depression and related neuropsychiatric disorders.
Major Depressive Disorder Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Rising Prevalence and Diagnosis of Major Depressive Disorder | 18.6% | Patient identification, treatment initiation and prescription volumes | Newly diagnosed and recurrent MDD patients | Increasing recognition of depressive symptoms, greater screening and improved access to mental-health services are expanding the diagnosed and treatment-eligible population, supporting sustained demand for antidepressants and advanced therapies. |
Growing Adoption of Rapid-Acting and Novel Depression Therapies | 16.9% | Treatment innovation, branded therapy uptake and refractory-patient management | Patients inadequately responding to conventional antidepressants | New mechanisms including NMDA modulation, neuroplasticity-targeting therapies and intranasal treatments are improving therapeutic options and creating premium growth opportunities beyond conventional antidepressants. |
Expansion of Adjunctive Treatment for Inadequate Antidepressant Response | 14.3% | Treatment escalation, combination therapy and patient persistence | Moderate-to-severe MDD patients with partial response | Increasing use of adjunctive antipsychotics and differentiated add-on therapies is broadening treatment pathways for patients not achieving remission with antidepressant monotherapy, supporting higher treatment intensity and pharmaceutical spending. |
Driver: Rising Prevalence and Diagnosis of Major Depressive Disorder
Rising prevalence and improving diagnosis of major depressive disorder are major drivers of market growth. Greater mental-health awareness, routine depression screening and increased recognition of recurrent and severe depressive episodes are expanding the population seeking clinical treatment. Improved access to psychiatrists, primary-care physicians, telepsychiatry and behavioral-health services is also supporting earlier diagnosis and treatment initiation. At the same time, persistent symptoms and inadequate response to first-line antidepressants are increasing demand for therapy switching, combination treatment and advanced interventions. These trends expand prescription volumes and create opportunities for both established antidepressants and differentiated next-generation therapies targeting difficult-to-treat patient populations.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Restricted Administration and Monitoring Requirements for Advanced Depression Therapies | 13.7% | Treatment accessibility, clinic capacity and therapy initiation | Patients receiving SPRAVATO and other supervised rapid-acting treatments | Complex administration requirements restrict scalability outside specialized treatment centers. SPRAVATO must be administered under healthcare-provider supervision, and patients are monitored for at least two hours following administration under the REMS framework, increasing infrastructure, staffing and patient-time requirements. |
Treatment-Related Adverse Effects and Safety Concerns | 11.9% | Treatment adherence, persistence and therapy switching | Patients receiving antidepressants, adjunctive antipsychotics and other pharmacological MDD therapies | Adverse effects such as sexual dysfunction, weight changes, sleep disturbances, gastrointestinal effects, sedation and other tolerability concerns can contribute to treatment discontinuation or switching. Safety monitoring requirements for certain therapies further increase clinical-management complexity, limiting long-term persistence and slowing adoption of some higher-value treatments. |
High Generic Penetration and Pricing Pressure on Conventional Antidepressants | 9.6% | Product pricing, branded-drug uptake and revenue expansion | Patients treated with established SSRIs, SNRIs and other conventional oral antidepressants | Widespread availability of inexpensive generic antidepressants creates substantial pricing pressure and raises the differentiation threshold for branded MDD therapies. New entrants must demonstrate meaningful improvements in efficacy, speed of response, tolerability or treatment convenience to secure premium reimbursement and physician adoption, constraining revenue growth across mature antidepressant categories. |
Restraint: Restricted Administration and Monitoring Requirements for Advanced Depression Therapies
Restricted administration and monitoring requirements for advanced depression therapies remain a significant restraint on Major Depressive Disorder Market growth. Treatments such as SPRAVATO require administration under healthcare-provider supervision, followed by post-dose monitoring, which increases staffing needs, clinic capacity requirements and patient time commitments. These operational demands can limit treatment availability outside specialized centers and may slow adoption among patients with limited access to psychiatric or infusion infrastructure. Providers must also manage REMS-related compliance, safety observation and scheduling complexity. As rapid-acting therapies expand, reducing monitoring burdens and improving administration convenience will be important for broader patient access and market scalability.
Major Depressive Disorder Market Segment Analysis
The global Major Depressive Disorder Market is segmented based on type, treatment type, and region.
Treatment Type: The antidepressant segment is expected to dominate the major depressive disorder treatment market
The antidepressants segment is expected to dominate the major depressive disorder (MDD) market, largely due to its central role in managing the condition and the broad range of medications available to treat various forms and severities of depression. These drugs, including SSRIs, SNRIs, atypical antidepressants, and others, are widely prescribed as the first-line treatment for MDD, offering proven efficacy and flexibility across different patient profiles.
Additionally, recent FDA approvals have further bolstered the segment's growth. For instance, in December 2022, the FDA approved VRAYLAR (cariprazine) as an adjunctive therapy to antidepressants for adult patients with MDD, as reported by AbbVie. Cariprazine, marketed as VRAYLAR in the U.S., is also FDA-approved for treating adults experiencing depressive episodes, acute manic episodes, and mixed episodes associated with bipolar I disorder, alongside schizophrenia.
Major players are conducting clinical trials in developing effective antidepressant drugs for the treatment of major depressive disorder. For instance, in May 2024, Johnson & Johnson announced positive topline results from the pivotal Phase 3 MDD3001 clinical trial, which evaluated the efficacy and safety of seltorexant as an adjunctive therapy to standard antidepressants in adult and elderly patients with major depressive disorder (MDD) who experience symptoms of insomnia.
These factors, combined with ongoing research and development efforts, are expected to keep antidepressants at the forefront of the MDD treatment landscape.
Major Depressive Disorder Market Geographical Penetration
U.S. Major Depressive Disorder Market Landscape
The United States represents a leading market for major depressive disorder therapies, supported by high disease burden, broad antidepressant utilization, strong reimbursement infrastructure and rapid adoption of novel treatments. NIMH estimates that 21.0 million U.S. adults experienced at least one major depressive episode, representing 8.3% of adults, while 61.0% of affected adults received treatment. Market development is increasingly driven by rapid-acting therapies, adjunctive treatments and neuromodulation. The FDA continues to support innovation in depression, including serotonin-2A agonists and other emerging neuropsychiatric approaches, while expanding treatment options for patients inadequately responding to conventional antidepressants.
Japan Major Depressive Disorder Market Outlook
Japan's major depressive disorder market is supported by increasing awareness of mental health, established psychiatric care infrastructure and continued demand for pharmacological treatment of depressive disorders. The Ministry of Health, Labour and Welfare emphasizes that mental health conditions are increasingly common in Japan and notes that approximately one in five people may experience a mental health disorder during their lifetime. Treatment continues to rely heavily on conventional antidepressants and specialist psychiatric care, while opportunities are emerging for therapies offering improved efficacy, tolerability and faster response. Japan's structured PMDA approval framework and expanding focus on mental-health awareness are expected to support future therapeutic innovation.
Major Depressive Disorder Market Competitive Landscape
- The Major Depressive Disorder Market is moderately concentrated, with competition centered on differentiated mechanisms of action, rapid onset of efficacy, treatment durability and the ability to address patients who fail conventional antidepressants. Johnson & Johnson holds the strongest direct commercial position through SPRAVATO, while AbbVie, Axsome Therapeutics, Otsuka Pharmaceutical and H. Lundbeck compete through established depression therapies used in patients with inadequate response to standard treatment. Large pharmaceutical companies benefit from strong psychiatry franchises, extensive physician networks and established commercialization capabilities.
- Competitive intensity is expected to increase as late-stage neuroplastogen and psychedelic-based therapies move toward commercialization. Eli Lilly, Compass Pathways, GH Research and Cybin are advancing differentiated candidates designed to provide rapid and potentially durable responses with less frequent dosing. Future market leadership is likely to depend on clinical efficacy in difficult-to-treat populations, safety and monitoring requirements, reimbursement access, treatment-setting scalability and the ability to differentiate from existing oral antidepressants and esketamine-based therapy. Strategic acquisitions, licensing agreements and pipeline expansion are expected to remain important competitive strategies.
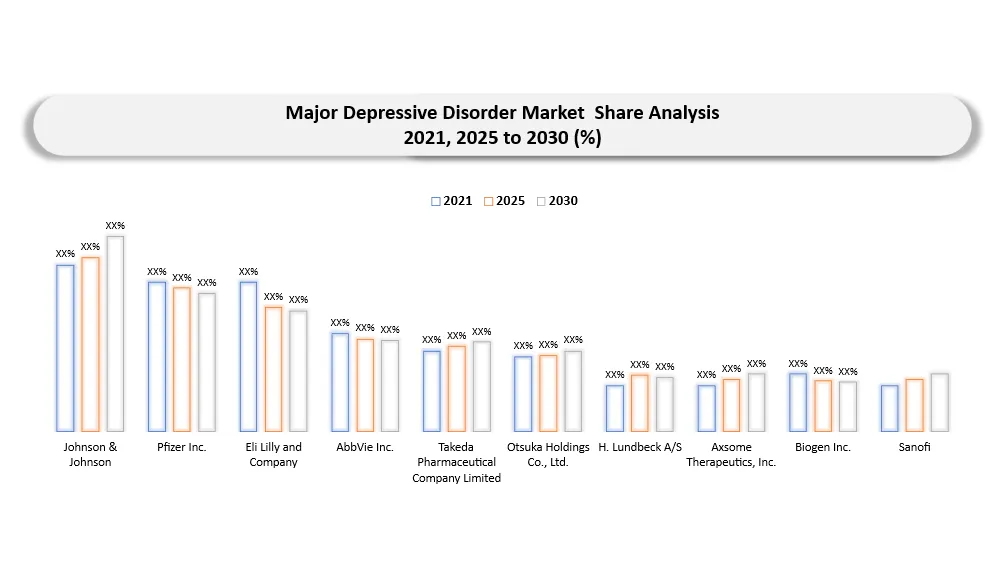
Key Companies of Treatment-Resistant Depression Market
- Johnson & Johnson (United States)
- Pfizer Inc. (United States)
- Eli Lilly and Company (United States)
- AbbVie Inc. (United States)
- Takeda Pharmaceutical Company Limited (Japan)
- Otsuka Holdings Co., Ltd. (Japan)
- H. Lundbeck A/S (Denmark)
- Axsome Therapeutics, Inc. (United States)
- Biogen Inc. (United States)
- Sanofi (France)
- AstraZeneca PLC (United Kingdom)
- GSK plc (United Kingdom)
- Novartis AG (Switzerland)
- Merck & Co., Inc. (United States)
- Teva Pharmaceutical Industries Ltd. (Israel)
- Viatris Inc. (United States)
- Sun Pharmaceutical Industries Limited (India)
- Aurobindo Pharma Limited (India)
- Dr. Reddy’s Laboratories Limited (India)
- Supernus Pharmaceuticals, Inc. (United States)
Major Depressive Disorder Market Recent Developments
- September 2026: Eli Lilly and Company completed its acquisition of AtaiBeckley Inc., expanding its neuroscience pipeline with BPL-003, an investigational intranasal mebufotenin therapy being developed as a rapid-acting treatment for treatment-resistant depression. The transaction was completed on September 11, 2026.
- August 2026: Compass Pathways reported that its two positive Phase 3 studies of COMP360 synthetic psilocybin demonstrated rapid onset and durable benefit through at least six months in patients with treatment-resistant depression. The company also confirmed that portions of its rolling New Drug Application had been submitted to the U.S. FDA, with completion of the filing targeted for the fourth quarter of 2026.
- August 2026: Compass Pathways announced a collaboration with the U.S. Department of Veterans Affairs for the PIVOT clinical trial evaluating COMP360 psilocybin in veterans with treatment-resistant depression, including patients with concurrent post-traumatic stress disorder. Compass is supplying the investigational treatment for the multi-site randomized controlled study.
- August 2026: GH Research reported progress toward pivotal development of GH001, its inhaled mebufotenin candidate for treatment-resistant depression. The company received written FDA feedback indicating that its chemistry, manufacturing and controls and device plans appeared Phase 3-ready and continued preparations to initiate its global pivotal program in 2026.
- July 2026: Compass Pathways announced six-month follow-up data from its second Phase 3 COMP360 trial, further supporting the rapid and durable clinical profile of its investigational synthetic psilocybin treatment for treatment-resistant depression.
What DATAM Uniquely Provides
- In-depth segmentation of the Major Depressive Disorder Market by drug type, route of administration, distribution channel and region, with additional assessment of antidepressants, atypical antidepressants, antipsychotics, neuromodulators and emerging next-generation depression therapies.
- Competitive analysis of leading major depressive disorder companies covering marketed product portfolios, mechanism of action, clinical efficacy, onset of action, dosing frequency, safety profile, treatment setting, regulatory status, pipeline maturity, commercialization strategy and geographic expansion.
- Comprehensive assessment of diagnosed and treatment-eligible patient populations, including patients with first-episode depression, recurrent major depressive disorder, moderate-to-severe depression, treatment-resistant depression, comorbid psychiatric conditions and other clinical characteristics influencing therapy selection and treatment outcomes.
- Detailed evaluation of the evolving treatment landscape, including selective serotonin reuptake inhibitors, serotonin-norepinephrine reuptake inhibitors, atypical antidepressants, adjunctive antipsychotics, intranasal therapies, neuromodulation approaches, rapid-acting antidepressants and emerging psychedelic and neuroplastogen-based treatments.
- Pipeline and clinical-trial intelligence covering Phase II and Phase III MDD candidates, regulatory milestones, New Drug Application progress, clinical efficacy endpoints, safety outcomes and emerging mechanisms of action that could reshape future treatment algorithms.
- Commercial and strategic assessment of prescription trends, branded-versus-generic competition, product uptake, treatment switching, patient persistence, physician prescribing behavior, payer coverage, reimbursement dynamics, formulary positioning and access barriers across major healthcare markets.
- Analysis of treatment-resistant and difficult-to-treat depression as high-value subsegments within the broader MDD market, including therapy sequencing, augmentation strategies, rapid-acting treatment adoption and opportunities for differentiated therapies addressing inadequate response to conventional antidepressants.
- Assessment of emerging innovation areas including NMDA receptor modulation, neuroplasticity-targeting therapies, psychedelic-assisted treatments, digital therapeutics, precision psychiatry, biomarker-driven treatment approaches and novel drug-delivery technologies.
- Strategic intelligence on partnerships, licensing agreements, acquisitions, co-development programs and commercialization alliances shaping the competitive structure of the major depressive disorder market.